

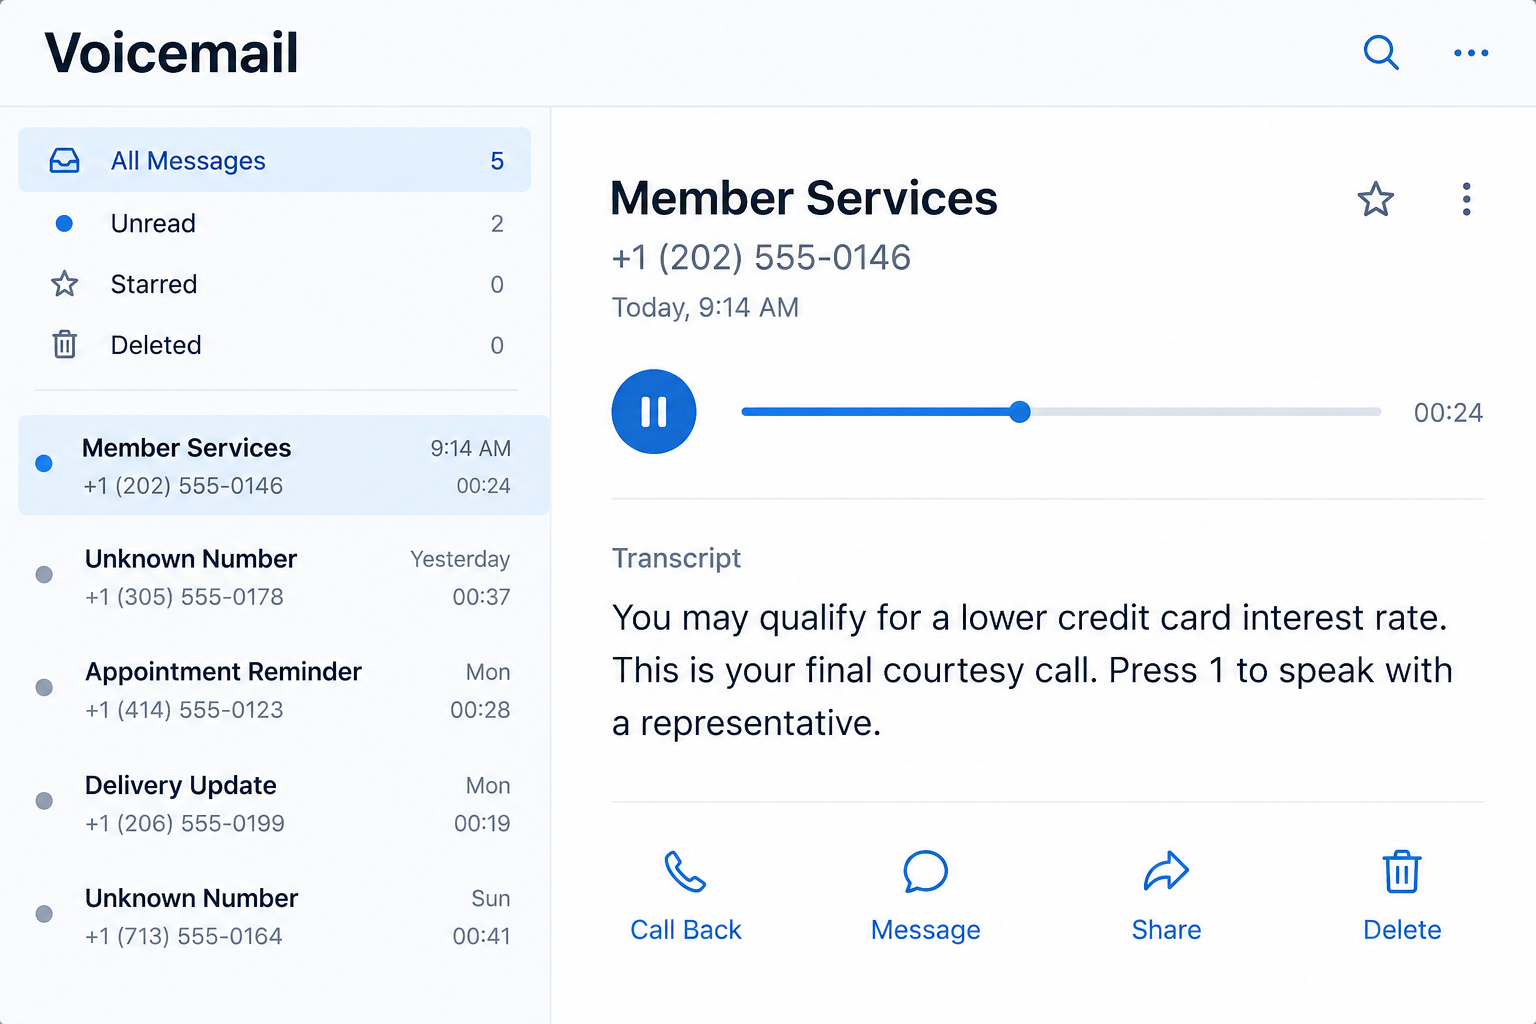
The voice sounds routine: Member Services is calling about your credit card. You might qualify for a better rate, but apparently there is little time left.
Member Services scam calls can sound remarkably ordinary. Before returning that voicemail, it helps to understand what the caller wants you to assume.
Overview
What the Member Services caller is offering
This scam uses a familiar department name to introduce an unsolicited financial offer. The caller promises lower credit card interest, debt relief, or special treatment.
Sometimes the recording says Card Member Services or Card Services instead. None of those phrases, by themselves, identifies the bank that issued your card.
The troubling part is the combination: vague affiliation, a supposedly urgent offer, requests for sensitive account details, and payment before any independently verified result.
Real organizations also have member services departments. This article concerns deceptive calls using that label, not every legitimate employee whose job involves helping members.
What is documented, and what remains unknown
The Minnesota Attorney General describes Card Services scams involving claimed banking connections, information requests, and promises that may not be delivered.
Federal regulators have also pursued businesses accused of deceptive interest-rate robocalls. That establishes a documented mechanism, not the identity of every caller using similar words.
There is no verified single operator, universal callback number, or standard fee behind all Member Services calls. A changing number does not establish a new organization.
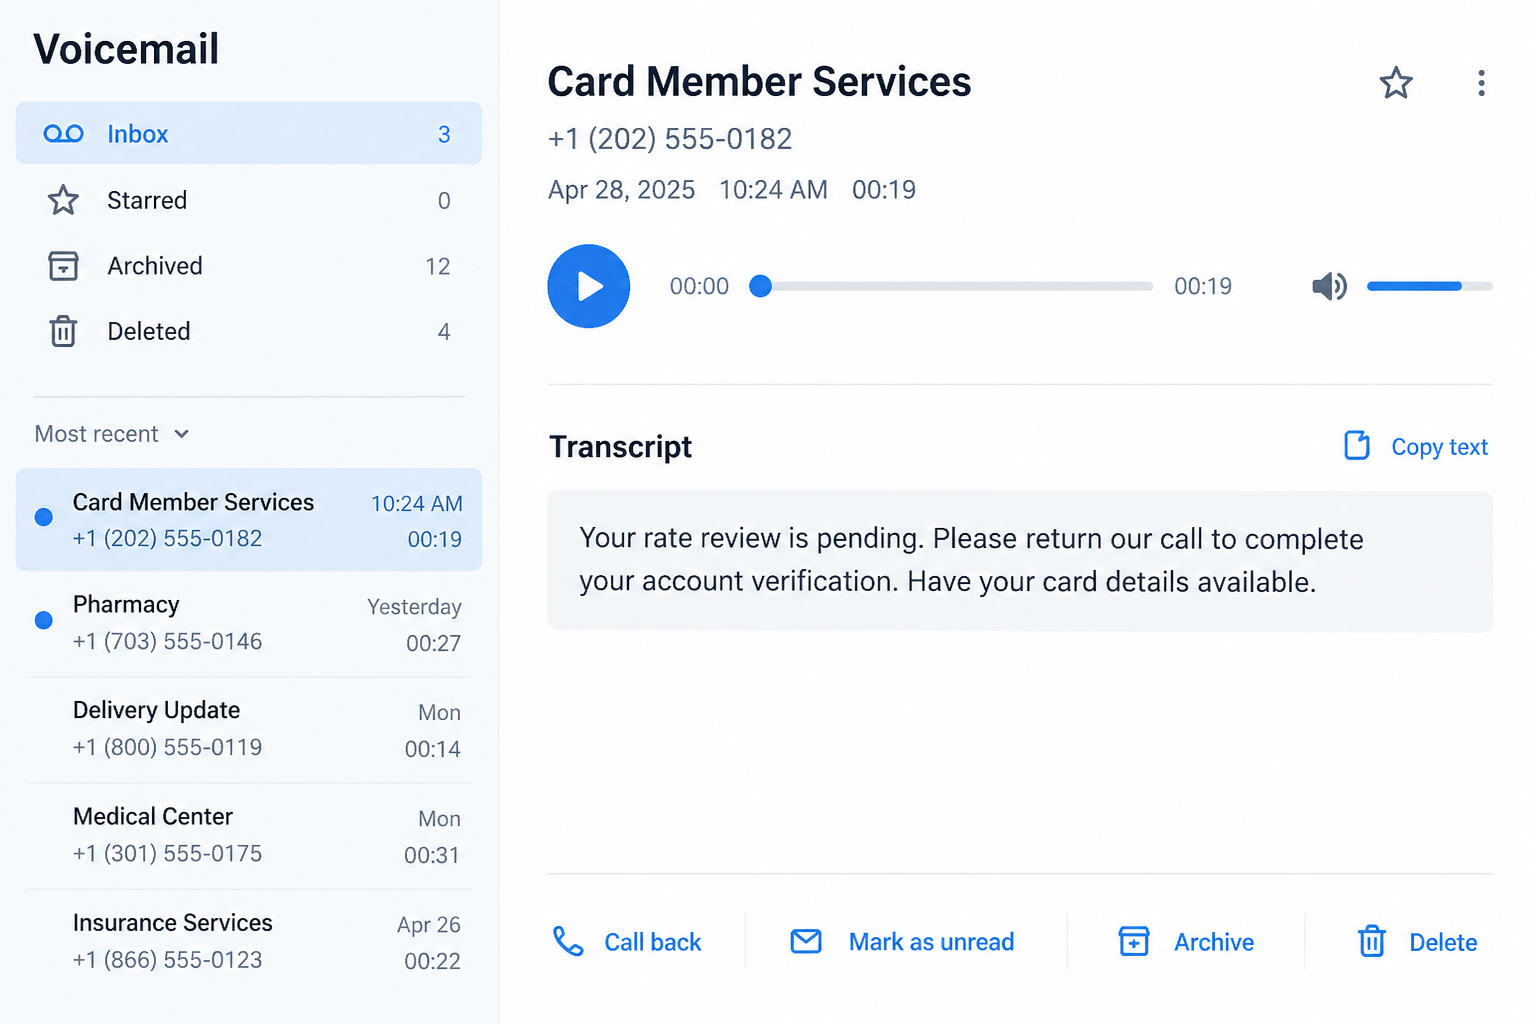
The voicemail interfaces in this article are illustrative reconstructions. Their fictional numbers and wording show the pattern; they are not recordings captured from an identified caller.
The warning signs worth remembering
- The caller names a department but avoids identifying your actual card issuer.
- A favorable rate is guaranteed before your account has been independently reviewed.
- You must act during the call to avoid losing the offer.
- The conversation shifts from general savings to card details or an advance payment.
- You are discouraged from contacting your bank through its published channels.
- The explanation becomes less clear when you ask who would receive your money.
You do not need to prove criminal intent during the conversation. Ending an unverified call is a reasonable precaution, even when the person sounds friendly.
Why a Generic Department Name Can Sound So Convincing
You supply the missing connection
Think about how often you hear terms such as account services, customer care, and member support. They describe functions inside many unrelated organizations.
A caller can leave the organization unnamed while you mentally connect the call to a card you already own. That assumption does much of the work.
Having several cards makes the ambiguity easier to overlook. You may concentrate on the promised savings instead of noticing that no specific account has been established.
A useful offer can distract from a bad source
Wanting a lower rate is entirely reasonable. An expensive balance can make an unexpected offer feel like welcome help rather than a sales approach.
But whether an offer sounds helpful and whether its source is trustworthy are separate questions. A sensible financial goal does not authenticate an incoming caller.
There is no need to debate the offer. You can investigate possible savings later, through a channel you choose and control.
How the Member Services Scam Works
Step 1: An unexpected call borrows the language of account support
The opening introduces Member Services or a similar label. It may arrive as a live call, a recorded message, or a voicemail inviting a callback.
The pitch can reference your payment history without identifying a specific statement or account. That creates familiarity while leaving important details unstated.
Do not treat a local number as verification. Caller ID is a display, not an independently checked introduction from your financial institution.
The FTC explains that scammers can manipulate the name and number shown on incoming calls. A recognizable display can therefore accompany an unrelated caller.
Step 2: A limited-time rate offer gives you a reason to stay
Next comes the promised benefit: less interest, smaller payments, or a chance to qualify before an offer closes. The exact wording varies.
The FTC’s robocall examples include an interest-rate pitch that combines favorable payment history with a final opportunity to respond.
That framing creates two competing feelings. You want to avoid a bad decision, but you also do not want to miss something useful.
A real review does not become more trustworthy because someone imposes a short deadline. Treat pressure as a reason to pause, not speed up.
Step 3: The caller moves from an offer to account questions
The representative may ask which cards you hold, what you owe, and what rates you pay. Those questions can make the conversation resemble a financial assessment.
Then the requested information becomes more sensitive. Card numbers, security codes, or identity details may be presented as necessary to check eligibility.
At this point, you are being asked to trust someone whose connection to your account has never been established. Answering more questions does not solve that problem.
Even correct information supplied by the caller is insufficient. Knowing a name or part of an account reference does not prove authority to handle the account.
Step 4: A fee or authorization becomes the condition for help
In the advance-fee version, the promised improvement depends on paying first. The fee may sound like enrollment, processing, or access to a special arrangement.
The FTC warns about lower-rate scams that claim special bank relationships and promise savings they cannot reliably deliver.
Its guidance also explains that companies selling debt relief by phone cannot charge before settling or reducing the debt. An impressive guarantee does not replace performance.
Do not provide payment authorization simply to learn whether the offer exists. Ask your actual issuer about available options through its official account-support channel.
Step 5: The promised result fails to match the sales pitch
Paying a third party does not automatically change the agreement with your card issuer. Your real statement remains the place to check the rate and balance.
A 2020 FTC complaint described alleged deceptive offers, additional fees, and applications made using collected personal information.
That historical case illustrates possible harm. It does not establish that every current Member Services caller applies for cards or uses the same method.
Possible outcomes include losing a fee, exposing financial details, or accepting a transaction you do not understand. The appropriate response depends on what actually happened.
Step 6: Follow-up contact keeps you engaged
A follow-up may refer to a pending review or unfinished verification. It can sound credible because you remember discussing the same subject earlier.
But continuity is not independent proof. The same person can repeat the same unsupported claim across several calls.
Do not keep paying to protect a payment already made. Save the communications and move the conversation to your genuine issuer or payment provider.
How to Verify the Call Without Sharing More Information
Use the number already associated with your account
End the incoming call, then use the number printed on your card or the support option inside your usual banking app.
Avoid calling a number dictated during the pitch. Likewise, a callback button attached to an unfamiliar voicemail does not independently verify the organization.
Tell your issuer what was offered and ask whether it came from them. You can describe the claim without first providing information to the unknown caller.
Separate a rate reduction from a new financial product
A change to an existing rate, a balance transfer, and a new credit account are different arrangements. The caller should not blur those distinctions.
Compare the annual percentage rate, fees, introductory period, and terms after that period. The CFPB’s credit card terminology explains these basics.
A lower advertised rate does not, by itself, establish lower total costs. Nor does a new application prove that your original issuer changed its terms.
Request the actual terms from the verified provider. Do not let a verbal savings estimate substitute for understanding what you would authorize.
Do not try to authenticate a caller by voice
A smooth conversation can come from an ordinary salesperson, a recording, or other technology. Sound quality is not a reliable way to establish identity.
There is no need to decide whether the voice is artificial. The safer test is whether the claim survives contact with your issuer through a separate channel.
That approach also avoids accusing a legitimate caller by mistake. You are verifying the request, not trying to judge someone’s accent or speaking style.
What to Do if You Have Fallen Victim to This Scam
- Stop the conversation and identify your actual exposure.
Write down whether you merely answered, disclosed card details, shared identity information, or approved a payment. These are different situations requiring different responses.
If you only listened and hung up, do not assume your accounts were accessed. Concentrate on blocking the contact and avoiding follow-up requests.
- Contact the card issuer about exposed card information.
Use your established support channel. Explain exactly what you disclosed and ask whether the card should be replaced or temporarily restricted.
Review recent activity with the issuer, including pending transactions. A clean statement today is reassuring, but it does not make exposed details safe indefinitely.
- Report the payment accurately and ask about recovery.
If you paid, tell the provider whether the charge was unauthorized or whether you approved it after a misleading pitch. Do not describe those situations interchangeably.
Request the available dispute or reversal process promptly. The FTC’s recovery guidance explains whom to contact for different payment methods.
Keep the case number, submission instructions, and deadlines supplied by your provider. Recovery is not guaranteed, so avoid anyone who promises a certain refund.
- Address exposed identity information separately.
If you disclosed sensitive identity details, consider a free credit freeze with Equifax, Experian, and TransUnion. Contact each bureau through its genuine website.
A freeze helps restrict access to your credit file for new applications. It does not cancel existing card transactions or replace reporting fraud to your bank.
The FTC explains freezes and fraud alerts, including their different purposes. Check your credit reports for unfamiliar accounts or inquiries.
- Preserve a clear record of the offer.
Save voicemail, call times, callback numbers, receipts, and written promises. Note the amount requested and what the caller said would happen after payment.
Distinguish the displayed incoming number from any callback number provided. They may differ, and neither automatically identifies the person responsible.
Keep sensitive records private. Publicly posting your complete card number or identity documents creates another problem without helping others recognize the script.
- Report the deceptive contact through official channels.
File a report at ReportFraud.ftc.gov when you lost money or have information about a deceptive business or caller.
For unwanted calls without financial loss, the FTC also directs consumers to DoNotCall.gov. Include specific details rather than just the generic department name.
A report creates useful evidence, but it is not a reimbursement application. Continue following the separate instructions from your bank or card issuer.
- Keep managing the real account.
Do not assume the caller paid your balance, changed your rate, or contacted your issuer. Check directly before making decisions about the existing account.
If you need payment assistance, explain your situation to the verified issuer. Ask what help is available without relying on a stranger’s promised arrangement.
Keep written confirmation of any genuine change. A voicemail from the original caller is not confirmation that your account agreement has been updated.
Reducing Repeat Calls Without Missing Everything Else
Use filtering as a practical aid
Check the call-blocking and labeling tools offered by your carrier and device. The FTC’s blocking guide explains options across different telephone services.
Blocking a number can reduce repeat contact from that display. It cannot prove that the next unfamiliar number belongs to a different caller.
Review filtering settings before enabling the strictest option. You may still need to receive calls from a clinic, school, delivery service, or new contact.
Keep a simple household rule
An easy rule is more useful than memorizing dozens of scammer names: no financial decisions during unexpected incoming calls.
You can always say you will contact the organization yourself. There is no obligation to explain further or remain on the line while someone objects.
If you help a relative manage accounts, agree on that rule beforehand. Make verification feel normal, so asking for help does not feel embarrassing.
Frequently Asked Questions
Is every call from Member Services a scam?
No. Genuine organizations use that department name. Verify the specific caller and request independently rather than treating a generic label as either proof or a verdict.
Can the number on my screen belong to my real bank?
Yes, a display can show a real number while the call originates elsewhere. End the call and initiate contact using your own trusted account-support details.
Can I ask my card issuer for a lower rate myself?
Yes. Contact your issuer directly and ask what options exist. Approval is not guaranteed, but you do not need an unsolicited intermediary to ask the question.
Does pressing 1 automatically give someone my card details?
No. Pressing a key is not the same as disclosing card information. Still, leave an unwanted sales call rather than entering a conversation designed to collect it.
Do I need antivirus software because I answered the call?
Answering a voice call alone is not evidence of malware. Card disclosure and deceptive payments require financial responses, not a claim that a scan reverses them.
Will the Do Not Call Registry stop dishonest callers?
It does not physically block calls or force criminals to comply. Treat registration as one measure, alongside filtering and independent verification of unexpected requests.
The Bottom Line
Member Services scam calls rely on an assumed relationship. A familiar department name and an appealing rate offer can hide the absence of a verified connection.
End the call and check with your actual issuer. If you already shared information or paid, respond to that specific exposure promptly, without panic or further payments.








