

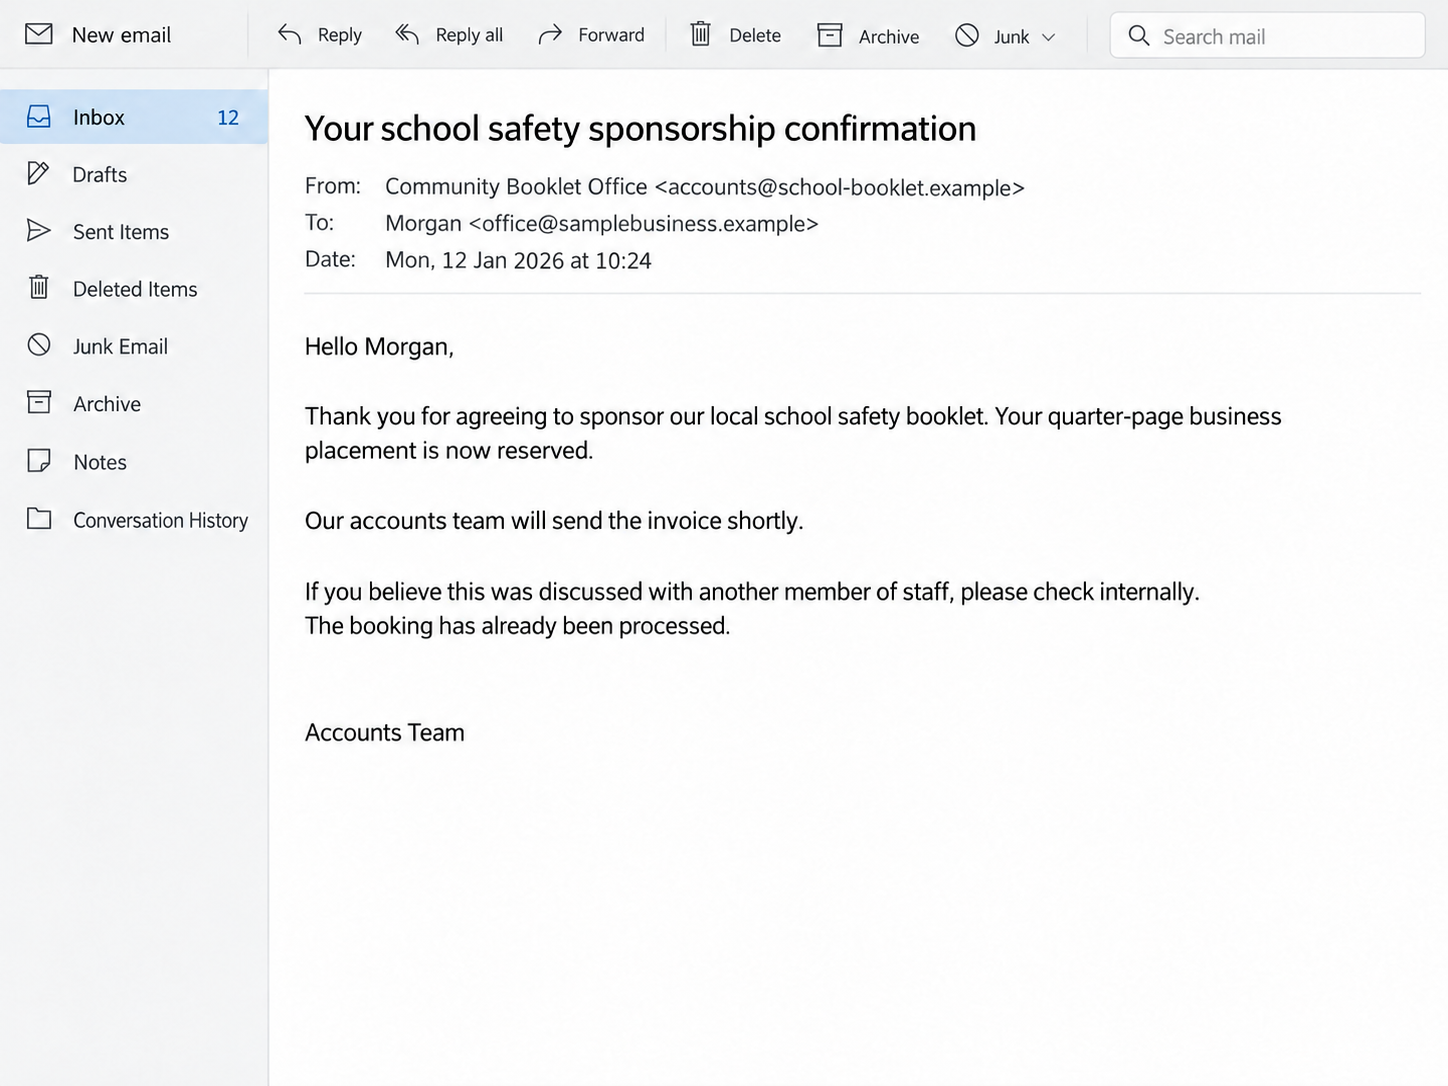
Your business gets an email thanking you for sponsoring a school safety booklet. The sender says the booking is complete, but nobody remembers making it.
The charity publication scam turns that awkward uncertainty into a payment demand. Before accounts settles the invoice, there are several facts worth checking.
Overview
The scam is an invented order or false affiliation
A caller or email sender claims your business agreed to buy advertising in a charity, school, or community-safety publication. An invoice follows as though the commitment exists.
In confirmed fraudulent versions, the order is fabricated or the claimed relationship with a beneficiary is false. A worthwhile cause becomes a reason to avoid questioning payment.
This is not a claim that every charity publication or advertising publisher is fraudulent. A genuine contract dispute needs different treatment from a deliberately invented booking.
Official warnings describe repeated business targeting
Royal Borough of Kensington and Chelsea guidance identifies publication scams that use supposed earlier agreements, other staff members, unsolicited invoices, and pressure to pay.
Warwickshire Trading Standards has warned businesses and schools about safety-booklet approaches, including misleading affiliation claims and disputed advertising commitments.
Those warnings establish a documented fraud pattern. They do not prove that a particular publisher mentioned in an online complaint committed fraud.
Check the order before accepting the debt
The essential question is whether an authorized person actually agreed to the stated service, price, and terms. An invoice cannot answer that question by itself.
- Identify the employee supposedly responsible for the booking.
- Check your own purchasing and sponsorship records.
- Ask for evidence supporting the claimed agreement.
- Verify the beneficiary separately using its established contact details.
- Keep a disputed demand out of the normal payment queue.
If the sender invented the agreement or falsely claimed official backing, that is the deceptive mechanism discussed here. Mere disappointment with advertising results is not enough.
Why a School Safety Booklet Is Such an Effective Pretext
Small businesses often support local causes. A school booklet about bullying, road safety, or drugs can sound like exactly the kind of modest sponsorship someone approved.
The caller does not need to persuade you that advertising is valuable. They need you to believe the decision was already made.
That changes the conversation from buying to administration. Instead of considering an offer, accounts is supposedly completing an overdue task.
A busy owner may assume a colleague handled it. A colleague may assume the owner agreed. The uncertainty is where the invoice gains traction.
The cause also creates social pressure. Questioning a bill can be made to feel like withdrawing support from children or a community organization.
None of that establishes a debt. You can support a genuine cause while refusing to pay a stranger who cannot substantiate the claimed booking.
A professional-looking PDF, familiar business name, or polite tone does not supply the missing agreement. Basic company information can be copied from public listings.
Focus on records you control and confirmation from the supposed beneficiary. Do not let an emotional description of the project replace those checks.
How the Charity Publication Scam Works
Step 1: A caller introduces a worthy local project
The approach may begin by telephone, email, or both. The project is described as helping schools, charities, emergency services, or a community-safety campaign.
The caller may talk about a small advertisement, sponsor listing, or booklet placement. Those are plausible services, which makes the opening less obviously suspicious.
Ask who runs the project and how the claimed relationship can be independently verified. Do not accept the caller’s chosen reference as your only confirmation.
An actual school or charity can tell you whether it knows the project. Contact it using details obtained separately, not a number supplied by the salesperson.
Step 2: A previous conversation is turned into an alleged commitment
The sender says you agreed earlier, that another employee confirmed, or that the placement is a renewal. Sometimes merely requesting information is presented as an order.
That claim needs evidence. A memory gap is not proof that your business booked advertising, and the sender’s confidence does not fill it.
Check internally before answering. Ask colleagues what was discussed, what documents were received, and whether anyone had authority to approve the stated purchase.
Do not assume a lack of signature automatically settles the matter either. Depending on the circumstances, agreements can arise without a signed paper contract.
Step 3: An invoice makes the invented booking look routine
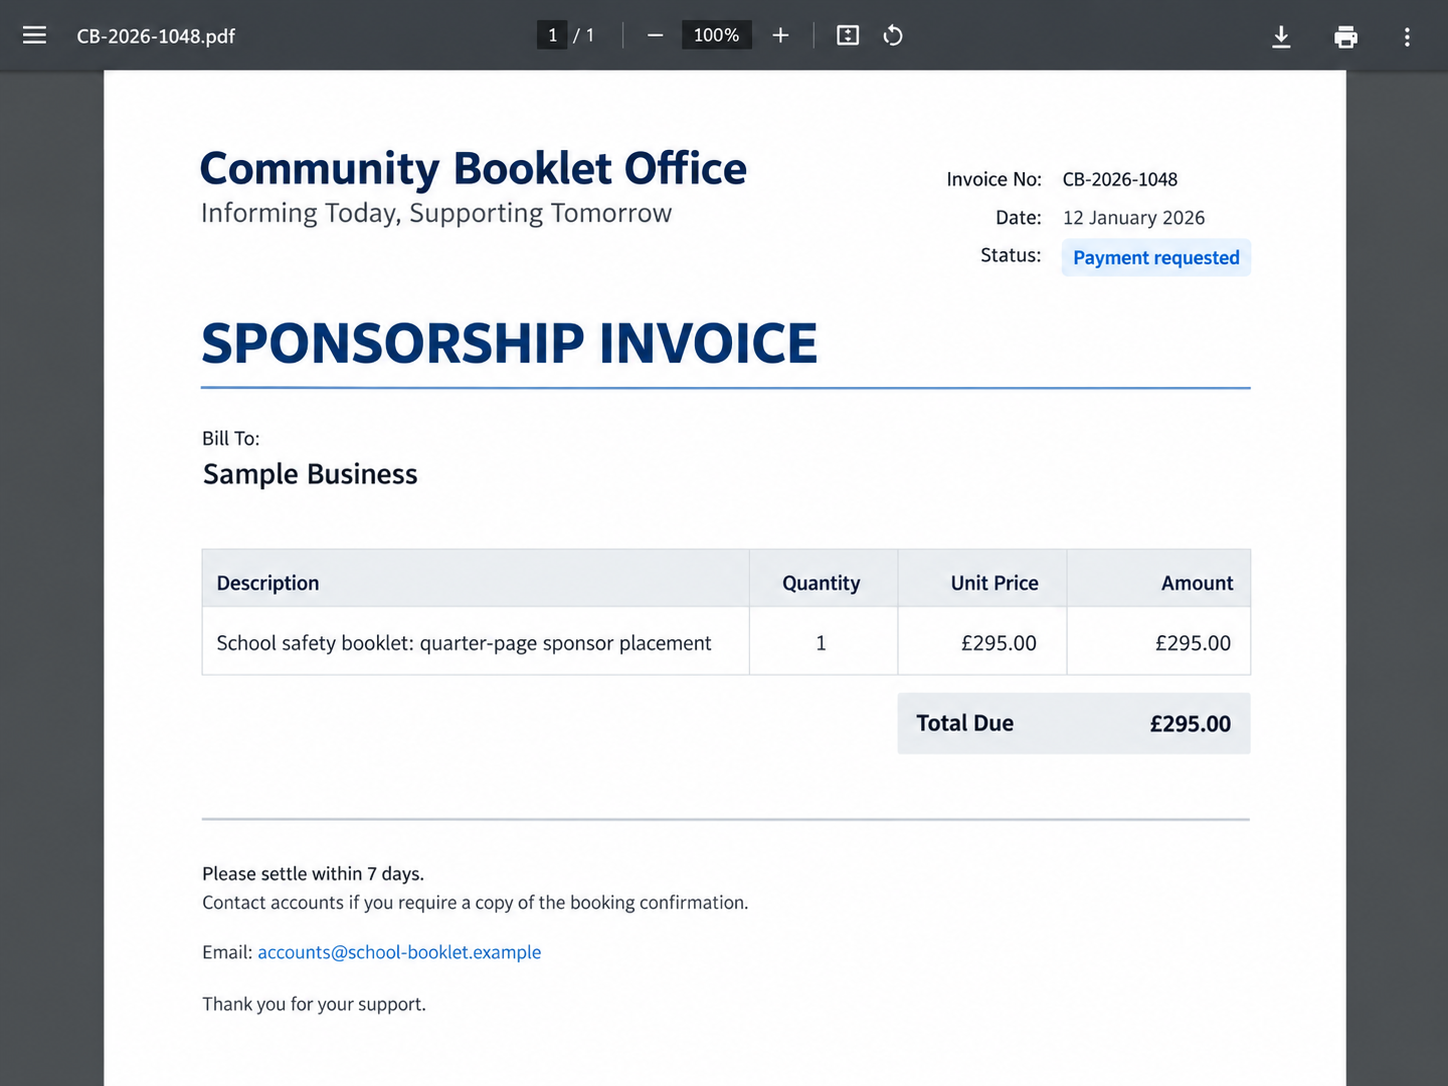
The invoice can include a reference number, business details, payment deadline, and description of the publication. Those elements resemble ordinary supplier paperwork.
Accounts may see a manageable amount and process it quickly. The original caller’s story disappears behind what now looks like a standard bill.
Our example email and invoice use fictional sender details. They show the paperwork sequence, not evidence against a real publisher or proof of a particular agreement.
Step 4: Questions are met with guilt, deadlines, or collection threats
A challenged demand may be described as already processed, noncancelable, or ready for collection. The sender hopes pressure will be cheaper than investigating the claim.
Some approaches invoke a charity’s supposed dependence on the payment. Others present legal action as inevitable without first supplying evidence of the order.
Do not confuse a threatening email with an actual court document. However, do not ignore genuine legal papers merely because the original invoice seemed fraudulent.
Separate the issues: dispute the unsupported claim, preserve the correspondence, and obtain appropriate advice if formal proceedings or deadlines appear.
Step 5: Payment can encourage another supposed renewal
If the first invoice is paid, a later demand may claim another placement, renewal, or outstanding balance. Paying once does not authenticate the next invoice.
The sender may refer to the earlier payment as evidence that your company participates. That still does not establish consent to additional services.
Review each demand against your own records. Make sure staff know the earlier invoice is under review so nobody pays a follow-up automatically.
This is a possible continuation, not a claim that every incident leads to repeated billing. The initial false booking is already sufficient reason to act.
A Poor Advertising Deal Is Not Automatically This Scam
A real publisher can provide disappointing circulation, weak design, or an advertisement that produces no customers. Those issues deserve scrutiny, but they do not automatically establish fraud.
Likewise, a disagreement over what a telephone conversation meant can be a contractual dispute. Evidence matters before accusing a named organization of inventing the transaction.
The clear fraud indicators are different: a nonexistent order, a knowingly false beneficiary relationship, fabricated approval, or a demand built on a deliberate misrepresentation.
A printed booklet does not prove the sponsorship pitch was truthful. Conversely, a booklet you have not seen does not by itself prove no publication exists.
Check the specific claim being made. If the caller says your local school requested the campaign, ask that school whether it actually did.
If the sender says a named employee booked it, check with that employee and request the complete evidence of the agreement.
If they promise distribution, ask for the relevant dates, recipients, and terms. Be precise about which representation cannot be verified.
Keeping these distinctions clear protects both the business and legitimate organizations. It also makes a fraud report more useful than a general complaint about feeling misled.
What to Ask When the Invoice Has No Matching Order
Start with your own records, not another sales call. Locate purchase orders, approval messages, diary entries, and any earlier correspondence about the publication.
Then request the basis for the demand in writing. Ask when the order was placed, who placed it, the exact service, and the agreed price.
If a recording is relied upon, request the complete relevant recording rather than a selected sentence. Preserve your own account of the conversation as well.
Ask for the terms supposedly accepted and how the sender says acceptance occurred. Do not acknowledge an agreement simply to obtain more information.
Verify any named school, charity, or public-service partner separately. A logo on a sales document does not establish permission to use that identity.
A registration record may identify an operating business, but registration does not prove this particular invoice or affiliation claim is accurate.
Do not turn the process into a hunt for suspicious addresses. The central evidence is the claimed order and beneficiary relationship, not assumptions about an office location.
If the evidence shows a genuine agreement, assess the dispute on that basis. If it shows fabrication, report the conduct without adding unverified allegations.
What to Do if You Have Fallen Victim to This Scam
-
Stop the payment workflow for the disputed demand. Tell whoever manages accounts that the invoice has no verified approval and must not be processed automatically.
Do not accidentally label it as an accepted supplier debt in your own records. Preserve the original invoice while marking the matter for review.
-
Speak with the employee named by the sender. Collect their recollection and any emails, notes, or documents before memories become confused.
Record whether they requested information, declined, or actually approved something. Keep uncertainty explicit rather than making an assumption favorable to either side.
-
Challenge an unsupported demand in writing. State that your records do not establish the alleged agreement and ask for the evidence supporting it.
Keep the response factual. Avoid threats, personal accusations, or wording that inadvertently accepts the booking while asking to cancel it.
-
Confirm claimed sponsorship relationships with the real school, charity, or agency. Use independently obtained details and retain their response.
If an organization says its identity was used without permission, include that confirmation in your report. Do not claim its response proves unrelated allegations.
-
If money has already been sent, contact the bank or payment provider promptly. Describe the fabricated-order or false-affiliation evidence and ask about recovery options.
Do not promise colleagues that the transfer can be reversed. The provider needs to assess the payment method, timing, and circumstances.
-
Save the invoice, email headers, caller details, claimed booking evidence, and payment record. Keep a brief chronology of contact and your internal checks.
Protect staff information when sharing evidence. A public post does not need personal telephone numbers, signatures, or complete banking details.
-
Report the suspected fraud to the relevant local authority or fraud-reporting service. In the UK, use the current Report Fraud route.
Seek appropriate business or legal advice if formal debt collection or court proceedings arise. Do not disregard verified documents or their response deadlines.
-
Brief your team about the specific pretext. Require future sponsorship invoices to match an authorized order before payment, even when the project sounds charitable.
Be alert to recovery offers claiming a fee will guarantee reimbursement. A convincing knowledge of the disputed invoice does not establish that the new contact is legitimate.
A Simple Accounts Rule That Breaks the Pressure
The useful rule is straightforward: sponsorship is a purchasing decision, not an exception to purchasing controls. Give it the same approval trail as any other expense.
Decide who may authorize a placement and what they must record. Include the service, price, beneficiary claims, and expected publication or distribution.
Reception staff should not have to investigate a persuasive caller in real time. Give them a normal route for passing offers to the authorized decision-maker.
Accounts should also know where approval records live. An invoice arriving before those records is a reason to pause, not a reason to invent an explanation.
A deadline from an unknown sender should not override that process. If the order is genuine, there should be a traceable basis for handling it.
When a caller claims another colleague agreed, contact that colleague internally. Do not let the caller supervise the verification or supply every answer.
These controls are useful even outside fraud. They reduce genuine misunderstandings and make it easier to support worthwhile projects deliberately rather than under pressure.
Frequently Asked Questions
Are all school-safety advertising calls scams?
No. Legitimate sponsorship and publishing exist. This warning concerns fabricated orders, false affiliation claims, and payment demands based on those deceptions.
Does a professional invoice prove we owe the money?
No. It states the sender’s demand, not independent proof of an agreement. Match it against authorized purchasing records and the evidence they provide.
Can a telephone agreement ever be binding?
It can, depending on the circumstances and applicable law. Do not rely solely on the absence of a signature; obtain advice for a genuine contractual dispute.
Should we pay a small amount to stop the calls?
Do not pay an unsupported demand merely to end pressure. Investigate and dispute it properly; payment may not prevent further contact.
What if a school really received the booklet?
That does not settle whether your business authorized the placement or whether the sales claims were truthful. Check the specific alleged agreement.
Should we ignore a threatened court claim?
Do not accept threats as proof of debt, but independently verify actual legal documents and get timely advice. A suspected scam does not erase court deadlines.
The Bottom Line
The charity publication scam uses a worthy cause to make an invented booking feel like an obligation your business has already accepted.
Verify the order and the claimed beneficiary relationship before paying. Genuine generosity should begin with a deliberate decision, not an invoice that rewrites your memory.








