

A signed note, a familiar business name, and a promised 20% return can make an investment feel more solid than a casual pitch.
Bright with Silver put those assurances at the center of its pitch. What happened behind the promise matters to anyone weighing a similar offer.
Overview
The offer crossed several investment themes
Bright with Silver, Inc. was used by Stanley Pophal to offer investments in areas including precious metals, cryptocurrency, real estate flipping, and artificial intelligence technology.
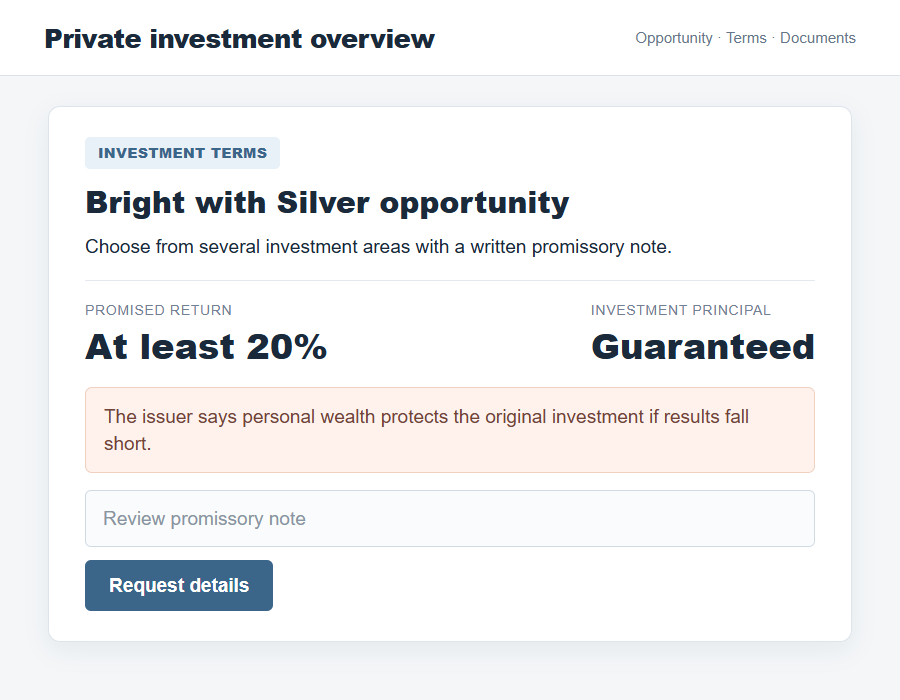
Many investors signed contracts styled as promissory notes. According to the U.S. Department of Justice, those notes guaranteed at least 20% returns.
Pophal also told investors their principal was safe because his own wealth could cover losses. That personal guarantee was central to the reassurance.
The DOJ says the claim was false: he never had enough funds to repay every investor’s principal personally.
What the criminal case established
Pophal pleaded guilty to wire fraud and money laundering and was sentenced in September 2026 to eight years in federal prison.
The court ordered $14.25 million in restitution. The DOJ says 190 investors were defrauded, including many people aged 65 or older.
Most investor money paid personal or business expenses, not the promised investments. New investor funds also supported payments presented to earlier investors as returns.
This is a documented fraud case, not a question about whether a normal investment simply underperformed. The guilty plea and sentencing establish that distinction.
What a reader should take from it
The red flag was not the word “silver” or any single asset class. It was a high guaranteed return paired with supposedly risk-free principal.
- The pitch covered several unrelated investment categories.
- Written notes promised at least 20% returns.
- Personal wealth was presented as a safety net.
- Early payments could make the arrangement appear to perform.
- Investor funds were used for purposes outside the promised investment plan.
A paper contract can document a promise. It cannot create the money needed to honor that promise.
The investment screens are illustrative reconstructions, not copies of any actual Bright with Silver investor documents or account pages.
Why the “Guaranteed Principal” Claim Was So Powerful
Investment returns can rise and fall. A claim that the investor will earn at least 20% while the original money cannot be lost changes the emotional calculation.
The buyer no longer feels they are choosing between risk and reward. The pitch suggests they can have both high returns and certainty.
Pophal attributed his promised performance to connections in finance, commodities, and real estate, according to the DOJ. That story supplied a reason to trust the unusual rate.
He also described past business success and significant personal wealth. The government says those claims were exaggerated or false.
Even a wealthy guarantor could fail to repay everyone in a severe loss. Here, investigators found the claimed wealth was not there to begin with.
When evaluating any offer, ask exactly who guarantees the principal, what assets support that guarantee, and whether independent records verify the claim.
How the Bright with Silver Investment Scam Worked
Step 1: A broad opportunity was offered
Prospective investors encountered offers under the Bright with Silver name. The themes ranged from gold and silver to crypto, property flips, and AI technology.
That variety let the same business story appeal to different interests. A reader focused on precious metals might hear a different emphasis from someone interested in AI.
The DOJ account does not give a single advertisement or conversation script. The consistent elements are the promised investment and the claim of unusually secure returns.
Step 2: A promissory note made the promise feel formal
Most investors signed contracts styled as promissory notes. A signed document can feel safer than a verbal pitch, especially when it states a return.
These notes guaranteed a rate of at least 20%, according to the government. The format did not make the underlying business able to produce that return.
Contracts matter, but their value depends on the issuer’s ability and willingness to perform. A document is not a substitute for verified finances.
Step 3: The principal was described as protected
Pophal told investors that even unsuccessful investments would not put their original money at risk because his personal fortune could repay them.
The DOJ says he did not have sufficient funds for that guarantee. The reassurance removed the very risk question investors needed to examine.
Guarantees should be tested with evidence, not confidence. Ask for independently verifiable financial statements and understand who holds the funds.
Step 4: Early payments made the account look productive
Some earlier investors received payments presented as investment returns or interest. The government says those payments came from newer investors’ funds.
That pattern can make a failing scheme look successful for a while. An early payout is evidence that money moved, not that a profitable operation exists.
People may reinvest after receiving a payment or tell friends about the apparent success. The visible return can become part of the pitch.
Step 5: Investor money supported unrelated spending
The DOJ says most funds went to personal and business expenses, including travel, a mortgage, private-plane rental, and vehicles.
Those expenditures did not match the broad investment story sold to participants. Investigators seized more than 600 items purchased or funded with investor money.
The exact path of each investor’s funds is not published in the DOJ summary. The case nevertheless establishes misuse at the scheme level.
Step 6: The gap finally reached court
Pophal pleaded guilty in April 2026. In September, a federal judge sentenced him to eight years and ordered $14.25 million in restitution.
Several victims described lost savings and retirement funds at sentencing. The court outcome does not mean every victim has already recovered money.
The case is a reminder that formal charges, a guilty plea, a sentence, and actual repayment are separate events.
Why Early Returns Did Not Verify the Investment
A person who receives a promised payment may reasonably believe the strategy is working. That is one reason Ponzi-style payments can be so persuasive.
To understand where a return came from, an investor needs more than a deposit in a bank account. They need trustworthy records of the underlying activity.
Was a property bought and resold? Were assets held in an independently verified account? Did audited results support the stated profit?
Those questions are difficult to answer when an operator controls both the pitch and the performance report. Independent custody and accounting matter.
In this case, the government says early payments were funded with new investor money, not profits from the advertised investments.
The Promissory Note Was Not the Same as Protection
A promissory note is a promise to repay under stated terms. It does not automatically place cash in a protected account for the investor.
Read what an offer says about the borrower, collateral, maturity date, and defaults. If those elements are unclear, the word “note” offers little comfort.
Even a detailed contract can be worthless if the issuer cannot pay. That is why independently verified assets matter more than a polished signature page.
Pophal told investors his personal wealth backed the principal. The DOJ says he did not have enough wealth to support that assurance.
A personal guarantee can sound reassuring, but it is only as strong as the guarantor’s actual resources and enforceability.
Ask whether promised collateral is legally recorded and whether someone independent can verify it. Do not accept a simple list of assets from the promoter.
Also ask how the business earns enough to pay every note. A guaranteed obligation requires cash flow regardless of whether the underlying investments succeed.
If the only clear source of payouts is new investor money, the model cannot continue indefinitely. Later investors carry growing risk as inflows slow.
In this case, the federal investigation established that earlier payments were presented as returns although they were financed by later investors.
What the Sentence Does and Does Not Resolve
The eight-year sentence addresses criminal responsibility. It does not reverse every transfer or restore every retirement account on the day judgment is entered.
The $14.25 million restitution order states an obligation to compensate victims. Actual collection depends on available assets and the legal process.
Investigators seized more than 600 items connected to investor funds, including vehicles and snowmobiles. Seizure is not the same as immediate distribution to victims.
Some assets may have to be valued, sold, or handled under forfeiture rules. That process can be slow and may not cover all losses.
Victims should keep contact information current with official case channels. Missing a notice can make an already stressful recovery process harder.
Be cautious of anyone promising a faster route because they know an investigator or have a private buyer for seized property.
The public DOJ summary does not provide every investor’s individual balance. Your own transaction records remain important even when the overall loss figure is known.
Someone who received an early distribution may still have a net loss. A qualified adviser can help separate principal, purported return, and later payments.
People who referred friends may feel guilty, especially if early returns made the offer appear credible. The case shows why visible payouts can deceive reasonable people.
Share accurate information with affected contacts, but avoid promising that any particular claim will be repaid. Direct them to official case updates.
How to Check a New Investment Without Becoming an Investigator
You do not need to reconstruct every trade yourself. You do need to know where your money will go and which independent party can verify it.
Search the operator’s regulatory and disciplinary history through the appropriate official databases. A clean search is useful, but it does not guarantee safety.
Ask for audited records and read the auditor’s name and scope. A self-created spreadsheet should not be treated as an audit.
Get written answers about risks and how losses would be allocated. If the answer is simply “you cannot lose,” request evidence for that extraordinary promise.
Take time before signing. The more a promoter resists independent advice, the more important that advice becomes.
What to Do if You Have Fallen Victim to This Scam
- Gather your investment records.
Keep promissory notes, wires, checks, account statements, emails, presentations, receipts, tax documents, and any record of payments received.
Organize deposits and withdrawals by date. Restitution and tax questions can depend on net amounts, so a clear timeline helps.
- Follow official case communications.
Use the DOJ or court’s official victim-information channels for updates. Confirm any new claim form or deadline through a verified government page.
Do not assume an email using a prosecutor’s name is genuine. Fraudsters may contact victims after a public case becomes known.
- Talk to your bank or brokerage.
Explain which payments went to the scheme and ask whether any transfer recall or fraud process remains available. Long-past payments may be difficult to reverse.
Keep written notes of the provider’s response. A denial today does not erase your right to document the loss for the case.
- Seek qualified tax and legal advice.
Investment losses, earlier distributions, and restitution can create complicated tax and civil questions. A qualified professional can assess your specific records.
Avoid anyone who promises a guaranteed deduction or full recovery before reviewing the facts.
- Secure accounts and identity information.
If you supplied sensitive information or reused a password on any related portal, change it and enable multifactor authentication.
Monitor financial accounts and credit reports for unfamiliar activity. A financial fraud can involve both money loss and data exposure.
- Reject recovery scams.
Restitution is not sold through an upfront “release fee.” Verify every caller and form independently, especially if they claim to have recovered frozen assets.
Do not send more money, crypto, or identification to a stranger who says they can move you to the front of a victim list.
Questions to Ask About Any Similar Offer
Begin with the return. If it is guaranteed, ask who guarantees it and what happens when the underlying investment loses money.
Ask who holds the principal and whether a regulated, independent custodian can confirm balances. A statement produced only by the promoter has limited value.
Request audited financials or transaction records tied to the strategy. A glossy presentation and a few satisfied investors do not prove a sustainable business.
Compare the promised rate with ordinary market risk. Exceptionally high returns with supposedly no downside deserve more scrutiny, not quicker commitment.
Understand whether you are lending to a company, buying an asset, or participating in a fund. Different structures bring different rights and risks.
Finally, ask what happens if you need your money back. A withdrawal promise is only useful if the operator can meet it from legitimate assets.
Frequently Asked Questions
Was Bright with Silver a real investment business?
It was the business name used in the scheme. The federal case established fraud in how investor money and promised returns were handled.
Did the promissory notes truly guarantee 20%?
The notes promised at least 20%, according to the DOJ. A written guarantee did not mean the operator had funds to honor it.
Why did some investors receive payments?
The government says early payments came from newer investor funds and were falsely presented as returns or interest from successful investments.
Has every investor received restitution?
The court ordered $14.25 million in restitution. An order does not by itself confirm how much has been collected or paid to each victim.
Is every 20% investment return a scam?
No. The problem here was a guaranteed high return, false safety claims, and misuse of funds. Evaluate each opportunity against independent evidence.
Should I pay a company that promises to recover my loss?
Be wary of upfront recovery fees and guarantees. Verify case information through official channels and consult a qualified adviser before sharing records.
The Bottom Line
The Bright with Silver investment scam paired broad investment themes with a written 20% promise and a false claim that principal could not be lost.
The guilty plea, sentence, and restitution order document the harm. If you invested, preserve your records and follow verified case and professional guidance.








