

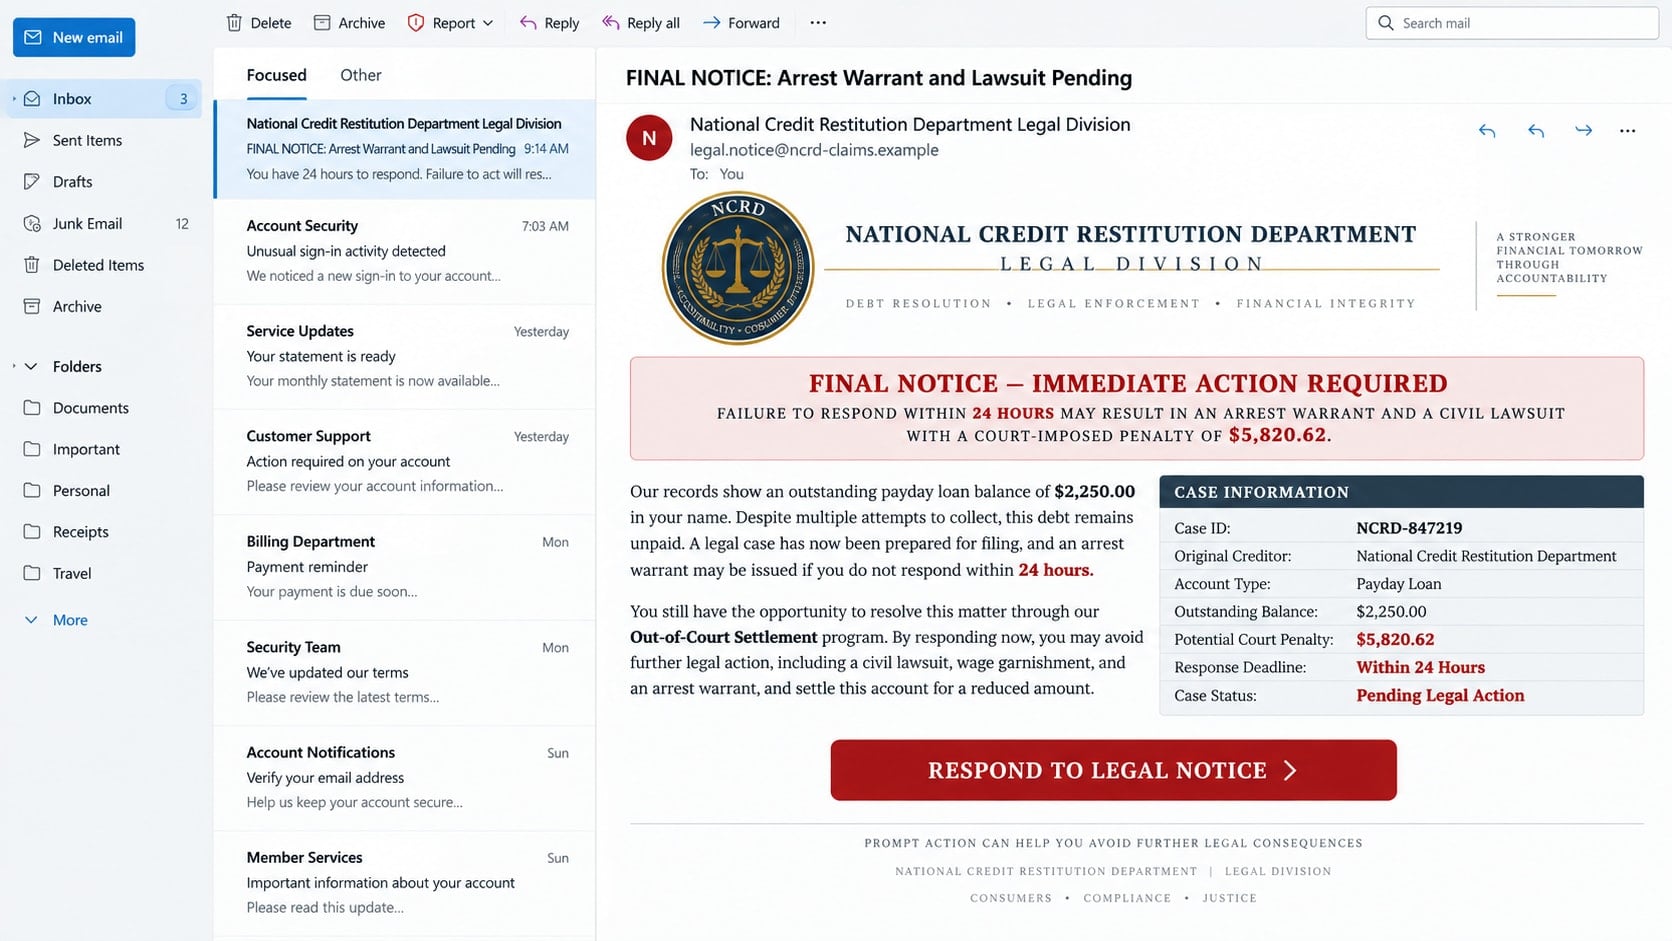
The email does not sound like a normal bill. It announces a lawsuit, lists criminal charges, and warns that an arrest warrant may be issued unless a forgotten payday loan is settled immediately.
That legal language is meant to make panic arrive before common sense. Once fear takes over, a made-up agency can start to look official.
Overview
The NCRD name is used to imitate a legal authority
The NCRD arrest warrant email scam claims to come from a “National Credit Restitution Department,” legal division, law firm, or debt enforcement office. The sender says an unpaid payday loan has become a criminal matter and may lead to court action or arrest.
The title sounds governmental, but a serious name is not proof that an agency exists. Scammers invent official-sounding departments because most recipients do not have time to research every unfamiliar institution.
A civil debt is turned into a frightening criminal story
The email may accuse the recipient of bank fraud, theft by deception, a worthless electronic check, or violating federal banking rules. It often claims that police, an employer, or the local courthouse will be contacted if payment is not made.
Those threats are the core of the scam. Legitimate collectors cannot simply have someone arrested for failing to pay an ordinary consumer debt, and real legal proceedings do not disappear because a stranger receives a gift card or rushed transfer.
The settlement offer is designed to capture money and identity data
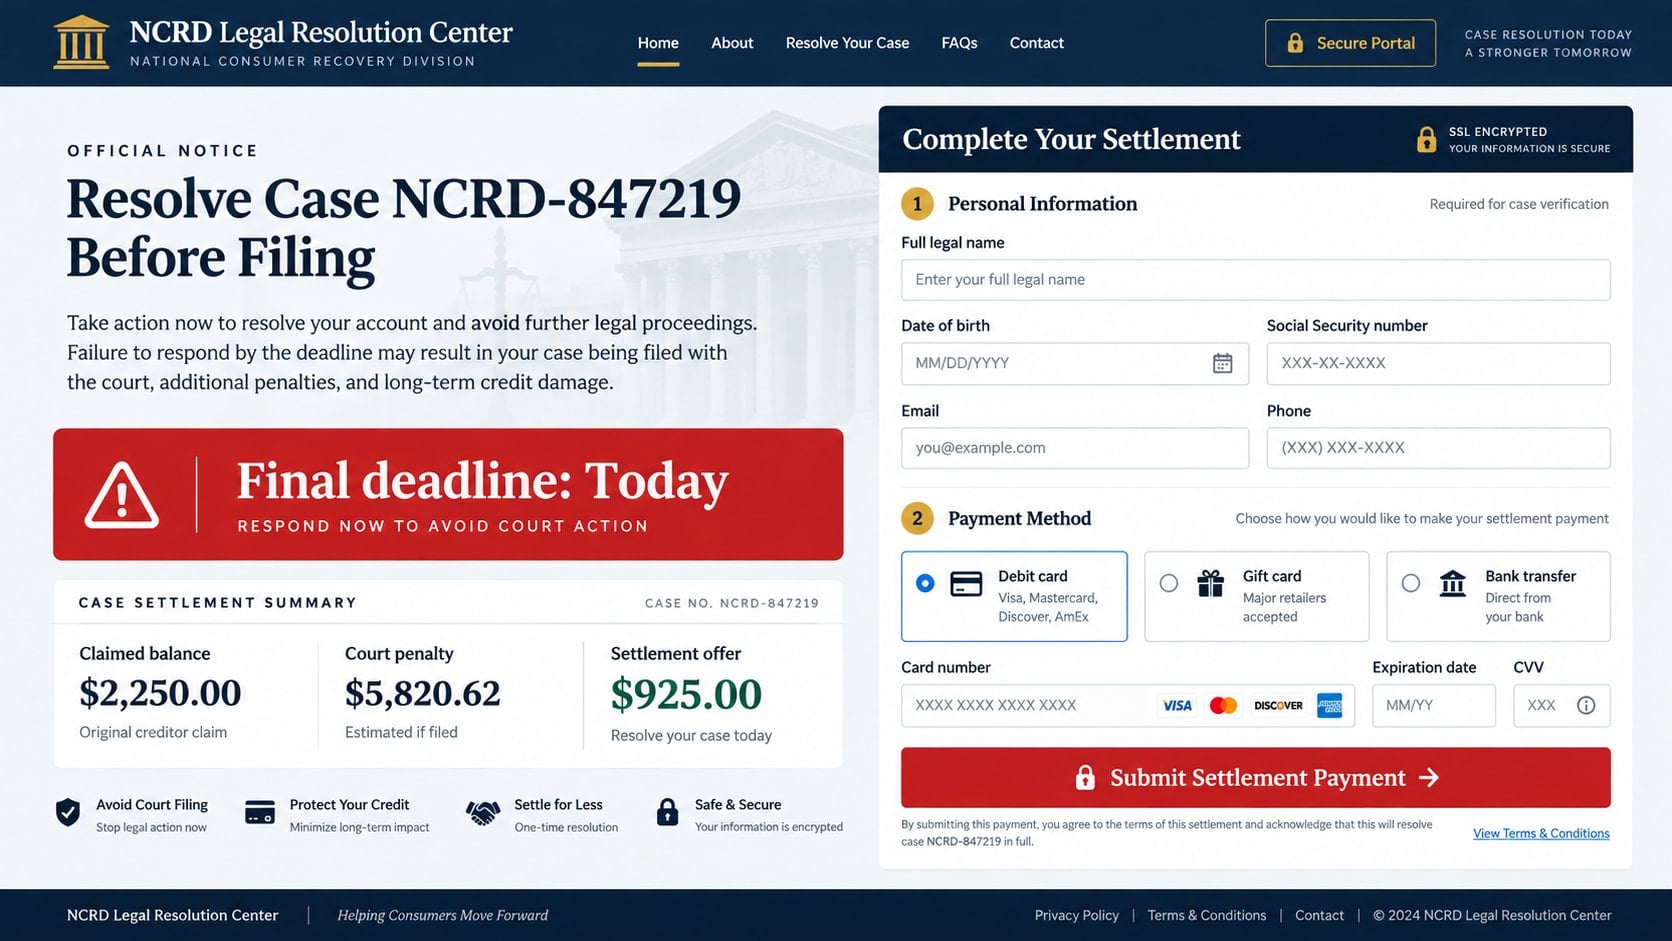
After presenting a much larger court penalty, the sender offers a reduced “out-of-court settlement.” The victim may be instructed to reply with personal information, follow a payment link, buy gift cards, send cryptocurrency, or provide bank details.
- An unexpected email alleges a payday loan you cannot identify.
- The sender threatens arrest, incarceration, job trouble, or immediate court action.
- A dramatic penalty is paired with a much smaller same-day settlement.
- The supposed legal office refuses to provide ordinary validation information.
- Payment is requested through gift cards, cryptocurrency, wire transfer, or a link in the email.
- The sender uses a free mailbox, vague address, invented legal language, or no verifiable phone number.
Why the Legal Threat Can Feel So Personal
A debt accusation can trigger fear even when the recipient does not recognize the account. People may wonder whether an old loan, identity-theft incident, relative’s debt, or forgotten payment has finally caught up with them.
The email exploits that uncertainty with case numbers, account numbers, affidavit headings, court dates, and references to laws. These details can be typed into a template in seconds. They are not evidence that a court, creditor, or enforceable debt exists.
Some messages contain a real name, former address, phone number, or partial Social Security number obtained from public records or a breach. Correct personal data makes the accusation more alarming, but it does not validate the debt or the sender’s authority.
The writing may alternate between formal legal phrases and obvious errors. Scammers are not drafting a real pleading; they are assembling words that sound severe enough to stop the recipient from asking questions.
How the NCRD Arrest Warrant Email Scam Works
Step 1: The email announces a case the recipient has never seen
The message claims that a creditor has filed or is about to file a lawsuit over a payday loan, electronic transfer, or returned check. It may present a case ID and say previous notices were ignored even though none were sent.
Starting at the final stage removes time for investigation. The victim is made to feel late, careless, and one step away from punishment before the alleged debt has been identified.
Step 2: Civil collection is disguised as criminal enforcement
The sender adds allegations such as theft, check fraud, or violation of banking regulations. The email may claim an arrest warrant will be issued, police will arrive at work, or a judge will impose jail time.
These claims are intended to silence skepticism. The FTC warns that threats of arrest over an unverified debt are a major sign of a fake or abusive collector.
Step 3: A large penalty makes the settlement look affordable
The message might say a $2,250 balance will become a $5,820.62 court judgment, then offer to close the case for a smaller amount. The contrast makes the settlement feel like the last reasonable exit.
Exact figures create a false sense of calculation. A random amount shown to the cent is still unsupported when there is no creditor name, loan agreement, payment history, or valid debt notice.
Step 4: The victim is pushed into a private reply or payment portal
The sender discourages calls to the original lender and says the matter can be handled only by email. A link may open a polished portal that repeats the case number and offers a one-time settlement.
The form can request a full name, date of birth, Social Security number, address, employer, bank account, or card details. The supposed verification process is actually another collection point for identity theft.
Step 5: Payment is requested in a hard-to-reverse form
Gift cards, cryptocurrency, money transfers, and person-to-person payments are popular because they can be difficult to recover. Some scammers accept a card first, then claim a system problem requires a different payment method.
Instructions may say not to mention the legal settlement to a cashier or bank. Secrecy protects the criminal from an employee who might recognize the scam and stop the transaction.
Step 6: The threats continue after the first payment
Paying rarely ends the story. The scammer may invent court filing fees, tax clearance charges, document costs, or another account. A victim who paid once is considered more likely to pay again under pressure.
If the victim refuses, the sender may intensify the language or pose as a lawyer, process server, police officer, or supervisor. These follow-ups are not proof of a real case; they are attempts to preserve the original lie.
Identity, Contact, and Payment Checks
Ask for debt validation before discussing payment
A legitimate collector should provide information identifying the collection company, current creditor, amount, and consumer rights. If the debt is unfamiliar, request written verification and do not fill in missing details for the sender.
Refusal to provide a mailing address, phone number, original creditor, or itemized balance is a serious warning. A case number created by the sender is not a substitute for documentation.
Check the claimed court through an independent source
Do not use a court number or website supplied in the email. Find the official court system for the jurisdiction yourself and ask whether the stated case number, parties, and filing exist.
A genuine lawsuit follows formal service rules. An unsolicited email containing a payment button is not automatically a summons, judgment, warrant, or proof that any filing occurred.
Contact the original creditor using known records
If the message names a lender, locate the lender through an old statement, credit report, or verified website. Ask whether the account exists, whether it was sold, and which company has authority to collect it.
Do not confirm your Social Security number, bank, employer, or former addresses to the email sender while trying to identify the debt. A scammer may use your answers to complete a profile.
Reject payment methods built around speed and secrecy
A demand for gift card numbers, cryptocurrency, wire transfer, or a person-to-person payment is not a normal way to resolve a court case. Instructions to stay on the phone, hide the reason for payment, or act before a bank closes are manipulation.
Even a card portal is unsafe when the organization behind it cannot be verified. A padlock only means the connection is encrypted; it does not prove that the recipient is a legitimate collector.
Warning Signs Hidden in the Email
The message may combine unrelated roles, claiming to be a collection agency, court, law firm, police unit, and internet crime center at the same time. Real organizations have defined responsibilities and do not share one anonymous inbox for every stage of a case.
Look for legal claims that do not fit ordinary debt collection. A recipient is not jailed merely because a consumer bill remains unpaid. A collector also cannot truthfully promise arrest, pretend to be a government official, or invent legal action that it does not intend or have authority to take.
Free email addresses are another clue, especially when the sender claims to represent a national legal department. Still, a custom domain alone does not establish legitimacy. Newly registered websites can imitate court seals and professional portals.
Unusual urgency matters most. A sender who refuses time for validation is trying to make fear do the work that evidence cannot.
What a Legitimate Debt Collector Should Be Able to Provide
A real collector should identify the creditor and explain the amount being sought. Federal consumer guidance says validation information generally includes the collector’s name, the creditor’s name, the consumer’s mailing information, an itemization of the amount, and details about dispute rights.
If you do not recognize the debt, you can dispute it and request verification. Keep the request and any response. Do not assume that ignoring every contact is wise, because a genuine debt may require attention, but verification should come before payment.
Legitimate collection does not depend on keeping you isolated. You can talk to the original creditor, a consumer attorney, a nonprofit credit counselor, or the appropriate regulator. A real collector cannot make your rights vanish because you asked for time to check.
If a court case truly exists, independently confirmed court records and formal documents will contain consistent parties, dates, and filing information. Compare those records carefully rather than trusting an image or attachment sent by the claimant.
What to Do if You Have Fallen Victim to This Scam
- Stop all contact and further payments. Do not send another fee to release, refund, or close the first transaction. Preserve the original email, full headers, attachments, payment instructions, receipts, account names, wallet addresses, and every message.
- Contact the payment provider immediately. Tell the bank, card issuer, money-transfer company, gift card issuer, cryptocurrency exchange, or payment app that the transfer resulted from a fake debt threat. Ask whether the transaction can be frozen, recalled, disputed, or traced.
- Secure exposed financial accounts. Replace compromised cards, change online banking credentials, review recipients and linked devices, and enable alerts for transactions and profile changes. Tell the fraud team if you shared a one-time code or allowed remote access.
- Protect your identity. If you disclosed a Social Security number, date of birth, driver’s license, address history, or similar data, place a fraud alert or credit freeze where available. Review credit reports and watch for unfamiliar loans, collections, and accounts.
- Change reused passwords. Begin with the email account because it can reset other services. Use unique passwords and multifactor authentication, and check forwarding rules, recovery addresses, active sessions, and recent sign-ins.
- Scan any device that opened an attachment. If you downloaded a document, enabled macros, installed software, or granted browser permissions, run a full scan with Malwarebytes. Remove detected threats, update the device, and avoid sensitive logins until the system is clean.
- Reduce contact with malicious pages. AdGuard can block known phishing domains, malicious ads, and deceptive redirects that lead to fake legal portals. It is a preventative layer and cannot reverse a payment or erase information already given to the scammer.
- Verify whether any real debt exists. Obtain credit reports, contact the alleged original creditor independently, and request validation from any legitimate collector. Keep the fraudulent demand separate from a real account that may coincidentally exist.
- Report the impersonation and threats. File a report with the FTC, Consumer Financial Protection Bureau, state attorney general, local police, and email provider as appropriate. Include the invented agency name, sender addresses, websites, payment destinations, and threats.
- Tell trusted people what happened. A relative, attorney, or financial counselor can help review follow-up messages and resist renewed pressure. Scammers often return as recovery agents who promise to retrieve the first loss for another upfront fee.
Frequently Asked Questions
Can I be arrested for not paying an ordinary consumer debt?
You cannot be jailed simply for failing to pay an ordinary bill. Fraud, contempt, and other legal matters are separate issues, but an email sender cannot create criminal authority by attaching those words to an unverified loan.
Is the National Credit Restitution Department a real government agency?
The name used in these scam emails is designed to sound official. Do not treat the title as proof. Verify any claimed organization through independent government directories and regulators before sharing information or paying.
What if the email includes my correct name and old address?
Personal details can come from public records, data breaches, marketing databases, or previous scams. Accurate background information does not establish that the debt, collector, lawsuit, or warrant is genuine.
Should I open the attached affidavit or court notice?
No unexpected attachment should be opened merely because it looks legal. It could contain malware or a link to a phishing page. Verify the alleged case independently and scan the file without enabling active content if professional review is necessary.
What should I do if I might actually owe a payday loan?
Contact the original lender using a verified number, review your records and credit reports, and ask any collector for validation information. A real debt should be handled, but a threat of immediate arrest is not a reason to pay an unverified stranger.
Can a scammer refund a payment after I complain?
Do not trust a promised refund that requires another fee, code, or remote-access session. Work through the original bank or payment provider. Recovery scammers frequently target people who have already paid once.
The Bottom Line
The NCRD arrest warrant email scam uses legal-sounding language to transform an unsupported debt claim into an emergency. Case numbers, seals, affidavits, and precise penalties can all be fabricated.
Pause before replying. Verify the creditor and any court case through sources you find yourself, insist on proper debt information, and never pay an arrest threat with gift cards, cryptocurrency, or a link inside the email.








