

Your card is still in your wallet, but the account shows a withdrawal you didn’t make. Nothing seemed unusual when you last paid or used an ATM.
A card skimming scam can leave that confusing trail. Understanding which information may have escaped makes the next conversation with your card issuer much easier.
Overview
Card data can be stolen while the card stays with you
Card skimming is the unauthorized capture of payment-card data at a compromised reader. The customer may complete an ordinary transaction and leave with the original card.
The copied information can be used for unauthorized payments. If the PIN is also exposed, the danger can include fraudulent cash withdrawals.
That explains why possession of the card doesn’t settle whether it was compromised. A criminal may need information rather than the physical item.
The FBI’s skimming guidance identifies ATMs, point-of-sale terminals, and fuel pumps as possible locations. A device can be attached externally or concealed inside equipment.
A suspicious charge does not identify the original theft
An unfamiliar payment is a reason to contact the issuer, not automatic proof that a particular store installed a skimmer.
Other routes include exposed shopping credentials, stolen card details, or a separate account compromise. The transaction record alone may not distinguish between them.
Likewise, a reader that looks normal can still be compromised. Visible damage is a warning sign, but the absence of damage is not a guarantee.
Focus first on stopping misuse. You do not need to solve the cause before reporting a transaction you didn’t authorize.
The protection and response depend on the exposure
A copied card number, an exposed PIN, and a stolen online-banking password are different problems. They may require different containment measures.
- Card data: discuss blocking the affected number and issuing a replacement.
- PIN exposure: tell the issuer where it may have happened and ask about a secure change.
- Unauthorized activity: identify specific transactions and follow the issuer’s dispute process.
- Suspicious equipment: stop using it and notify the operator or local authorities without removing anything.
Traditional physical skimming does not, by itself, infect your computer. A device scan cannot recall payment data already copied from a reader.
What a Skimmer Can and Cannot Tell a Criminal
Reusable card information is the attraction
A magnetic stripe holds card information that a compatible reader can collect. A concealed device can capture information when a customer performs an ordinary payment.
The criminal may try to reuse that information elsewhere. Which attempts succeed depends on the card, payment system, issuer controls, and the information obtained.
This is different from a person learning everything about your banking profile. A card-data exposure does not automatically include your password, email inbox, or every linked account.
A useful report therefore describes what you know: where the card was used, whether you typed a PIN, and which later transactions you don’t recognize.
A PIN can create a separate cash-withdrawal risk
The number typed at the keypad isn’t necessarily captured by the same device as the card data. A camera or altered keypad can be another part of the setup.
Keeping the keypad covered limits what an observer or camera can see. It doesn’t inspect the reader or fix concealed equipment.
Don’t give your PIN to someone offering to test the machine after a problem. A claimed repair or security check is not a reason to disclose it.
If you think the PIN escaped, say so directly to your issuer. That detail helps distinguish a card purchase dispute from a possible ATM-withdrawal exposure.
Chip and contactless payments are not magic shields
Chip and contactless technology provide stronger protections than a simple magnetic-stripe transaction. Using them can reduce exposure to traditional stripe-copying schemes.
That does not make a card immune to every form of fraud. A tampered terminal, stolen account credentials, or a deceptive payment request remains a separate concern.
A chip card also has a stripe on its back. If a terminal asks you to fall back to swiping, the fact that the card has a chip isn’t enough.
Use a supported secure payment method, but continue checking the amount and account activity. Better transaction protection and regular monitoring work together.
How the Card Skimming Scam Works
Step 1: A payment reader is compromised before the customer arrives
The criminal’s opportunity begins at equipment used by ordinary customers. The compromise may be visible as an attachment or hidden inside the reader.
A familiar merchant name doesn’t tell you what happened to an unattended terminal. The business itself may be another victim of the tampering.
You can look for unexpected changes without dismantling anything. A crooked opening, unusual keypad, damage, or an unexplained attachment is enough reason to choose another route.
Compare only what is safely visible. Do not handle a suspected device, pull wiring, or assume an undamaged machine has been professionally inspected.
If staff are available, tell them which terminal concerns you. A precise location is more useful than a general claim that every machine on site is unsafe.
Step 2: An ordinary transaction exposes information
The customer inserts or swipes a card and follows familiar prompts. A successful purchase or withdrawal can make the interaction seem entirely normal.
A receipt can show that your purchase went through. It can’t tell you whether a concealed device also copied information during the transaction.
A PIN request adds another possible exposure. Keep others from watching, and don’t allow an unsolicited helper to coach you through unexpected account questions.
At an ATM, a retained card deserves prompt attention. Contact the institution through an independently known channel rather than a sticker offering immediate recovery assistance.
Do not keep entering the PIN in response to unexplained errors. Move away from suspicious equipment and ask the operator how to handle the failed transaction.
Step 3: Copied details are reused away from the original reader
Unauthorized activity may appear later or somewhere you have never visited. That separation can make the original exposure difficult to identify.
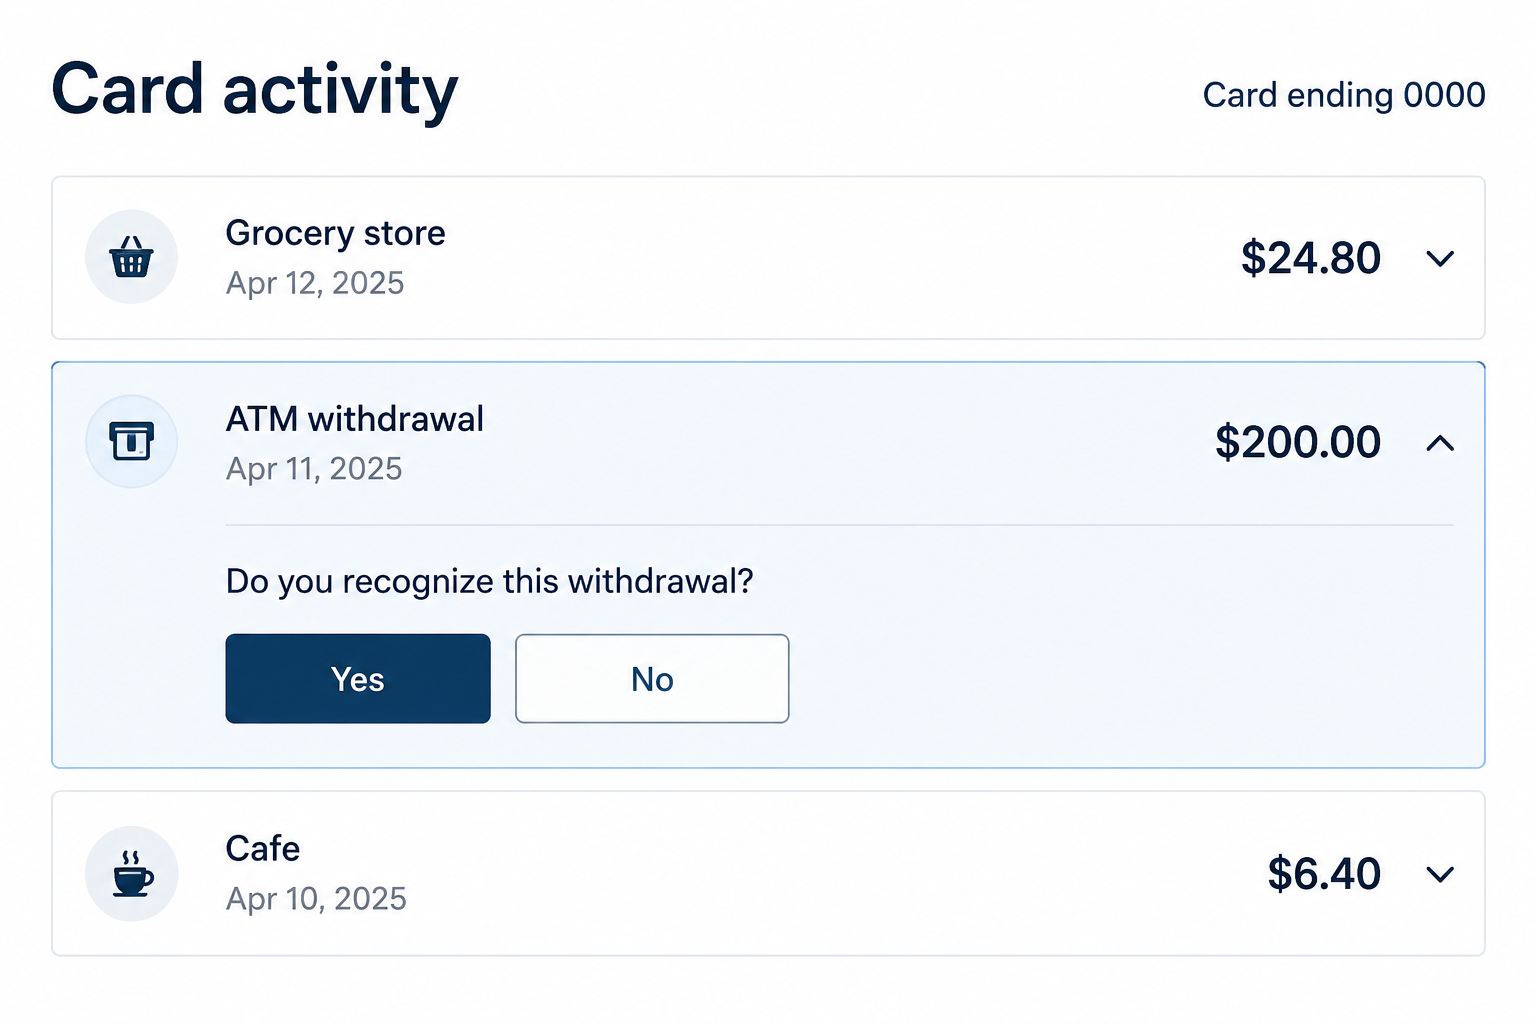
For an illustrative example, a normal grocery purchase could precede an unfamiliar ATM withdrawal. The sequence alone would not prove the grocery terminal caused the loss.
The issuer can investigate transaction details that are not obvious in the customer-facing statement. Your role is to supply an accurate history, not guess the criminal’s equipment.
The amount isn’t a reliable test of seriousness. A small unfamiliar debit still deserves a question, particularly if it is followed by additional attempts.
The CFPB’s card-data guidance advises watching even small unexplained activity. Fraudulent use can also appear well after the original exposure.
Step 4: The delay gives the criminal more opportunities
A person may wait because the card remains in their possession or the amount seems too small to matter. That pause leaves the affected number active.
Don’t wait for a second charge to make the first one feel important. Contact the issuer as soon as you identify activity you did not permit.
Blocking the card is containment, not the complete dispute. Existing transactions still need review, and the issuer may require additional written information.
Keep checking the account after replacement. Pending transactions and legitimate recurring payments can require attention even when the original number can no longer be used normally.
Warning Signs Before and After a Transaction
At the terminal, notice changes you cannot explain
Unexpected attachments, a different-looking keypad, or an unstable reader can justify walking away. You don’t need to prove that the object is a skimmer first.
Some payment devices vary legitimately, so appearance alone cannot identify a criminal. Report the concern and let the responsible operator assess the equipment.
Choosing a staffed alternative can be practical. It is not a reason to stop protecting the PIN or checking the transaction amount.
At fuel pumps, other tricks involve an open fueling authorization rather than copied data. Our gas-station scam guide explains that separate risk.
In the account, investigate unfamiliar activity
Merchant names can look different from the name above a shop door. Compare receipts and ask the issuer about an unclear descriptor before declaring it fraudulent.
Don’t approve a transaction merely because you are unsure. Tell the issuer which amount or location needs explanation, especially if you never authorized a cash withdrawal.
A charge you recognize doesn’t make nearby unfamiliar activity legitimate. Review each entry on its own facts instead of treating the statement as all safe or all compromised.
During a follow-up, keep card secrets out of the conversation
A caller may claim they noticed the suspicious terminal and now need your PIN or a security code. That creates another exposure rather than containing the first one.
End the contact and reach the issuer yourself. The person who raised the alarm should not be your only source for the number you call.
Do not send photos showing the full card to a merchant employee who offers to investigate. Relevant transaction records can be shared through the issuer’s approved process.
Preparing a Useful Card-Fraud Report
Build a simple transaction timeline
List your recent legitimate transactions and the entries you question. Add the date, amount, merchant descriptor, and any receipt you still have.
Record when you first noticed the problem and when you notified the issuer. Those are separate dates, and either may become important during follow-up.
For a terminal concern, include the location and machine identifier if you recorded it safely. Don’t return to a threatening situation to collect a missing detail.
Describe the exposure without inventing certainty
Tell the representative whether the card was lost, whether you entered a PIN, and whether anyone received a password or code during a separate conversation.
“My card was retained” and “my card is still with me” are different facts. A concise, accurate account helps route the report correctly.
You can say “possible skimming” and still be clear that you didn’t authorize the withdrawal. Let the issuer investigate how the information escaped.
Keep card replacement separate from reimbursement
A new number can reduce further misuse. It doesn’t automatically settle the question of who pays for transactions already recorded.
The CFPB explains debit-account reporting protections. Time limits and liability depend on circumstances, including whether the card or PIN was lost.
Report promptly and follow the institution’s process rather than treating a general article as a universal reimbursement promise. Credit and debit disputes are not identical.
What to Do if You Have Fallen Victim to This Scam
You can begin these steps without finding a skimmer or establishing which store was involved. The immediate priority is protecting the affected payment method.
-
Contact the issuer through an independent route. Use the trusted app, the contact information on your card, or the institution’s official website.
Explain the unrecognized transactions and any suspected reader exposure. If the card was retained, report that specifically instead of waiting near the machine for an unknown helper.
-
Ask for the appropriate block and replacement. A temporary lock may be available, but ask the issuer whether the compromised number needs permanent cancellation.
Find out whether cash withdrawals, wallet tokens, or other payment routes require additional action. Avoid assuming one control covers every type of transaction.
-
Address a potentially exposed PIN. Arrange a change through the institution’s secure procedure. Don’t tell a caller the old or new PIN.
Explain whether you typed it at the suspicious terminal. If online credentials were separately disclosed, ask about securing the banking profile as well.
-
Identify each disputed transaction. Provide dates, amounts, and descriptors. Distinguish payments you authorized from ones you didn’t, even if both appear near each other.
Ask about written confirmation, supporting records, and the next deadline. Save the case number and copies of anything submitted.
-
Notify the equipment operator safely. Give the terminal location, time of use, and observed problem. Ask the operator to preserve relevant records.
Leave any suspected attachment where it is. Do not remove equipment, confront staff with unsupported accusations, or try another transaction to test your theory.
-
Report suspected crime through official channels. Local police may handle physical tampering; the FBI directs skimming reports to the Internet Crime Complaint Center.
Keep reporting details consistent with what you observed. A police or fraud report supplements the issuer dispute; it doesn’t replace notifying the institution.
-
Review the replacement period. Track pending items and update necessary legitimate payments after the issuer explains what changed.
Ask about transactions that appear after a block instead of assuming every later posting proves a new breach. Posting dates and purchase dates can differ.
-
Escalate an unresolved banking complaint appropriately. If an institution’s response remains unclear, request its written explanation and preserve your correspondence.
In the U.S., the CFPB complaint process can help route a consumer-finance concern. It isn’t a guarantee of a specific outcome.
Frequently Asked Questions
Can a card be skimmed without being stolen?
Yes. The criminal may copy data while the genuine transaction completes. Keeping the physical card does not rule out exposure.
Does every unfamiliar charge mean an ATM skimmer was involved?
No. Card details can escape through different routes. Report the transaction and describe the suspected exposure without assigning a cause you cannot establish.
Is contactless payment completely immune?
No. It can reduce risk from traditional stripe skimming, but it does not eliminate account compromise, deceptive payments, or every form of terminal fraud.
Should I remove a suspected attachment?
No. Stop using the equipment and alert its operator or local police. Preserve the scene rather than handling a possible device.
Does skimming expose my online-banking password?
Not automatically. Report any separate password, code, or remote-access exposure. A physical reader theft and an online account takeover require different investigation.
Do I need antivirus software to recover copied card data?
Software cannot erase a criminal’s copy of payment data. For physical skimming, issuer containment and transaction review matter; investigate devices only if there was separate digital exposure.
The Bottom Line
Don’t use a reader that appears altered. A card skimming scam can take reusable information while leaving the card in your possession.
If you notice an unauthorized payment or withdrawal, contact the issuer promptly, arrange containment, and follow its dispute instructions. Solving the theft method can come afterward.








