


An invitation to a wealth club sounds different from a stranger promising quick cash. PRP Life uses the language of planning, diversification, and a more comfortable future.
For someone considering retirement savings or an extra income stream, that presentation can feel reassuring. Before joining, there is a much more important record to examine.
Overview
PRP Life appears on an official fake-platform warning list
New Zealand’s Financial Markets Authority lists PRP Life and prplife.com in its fake investment platform warning. The entry was added on October 28, 2026.
This is an official warning tied to the exact website, not merely a low automated score or an anonymous complaint about an unidentified investment.
Do not send money to PRP Life. An attractive presentation is not an adequate answer to a regulator identifying the same operation as a fake investment platform.
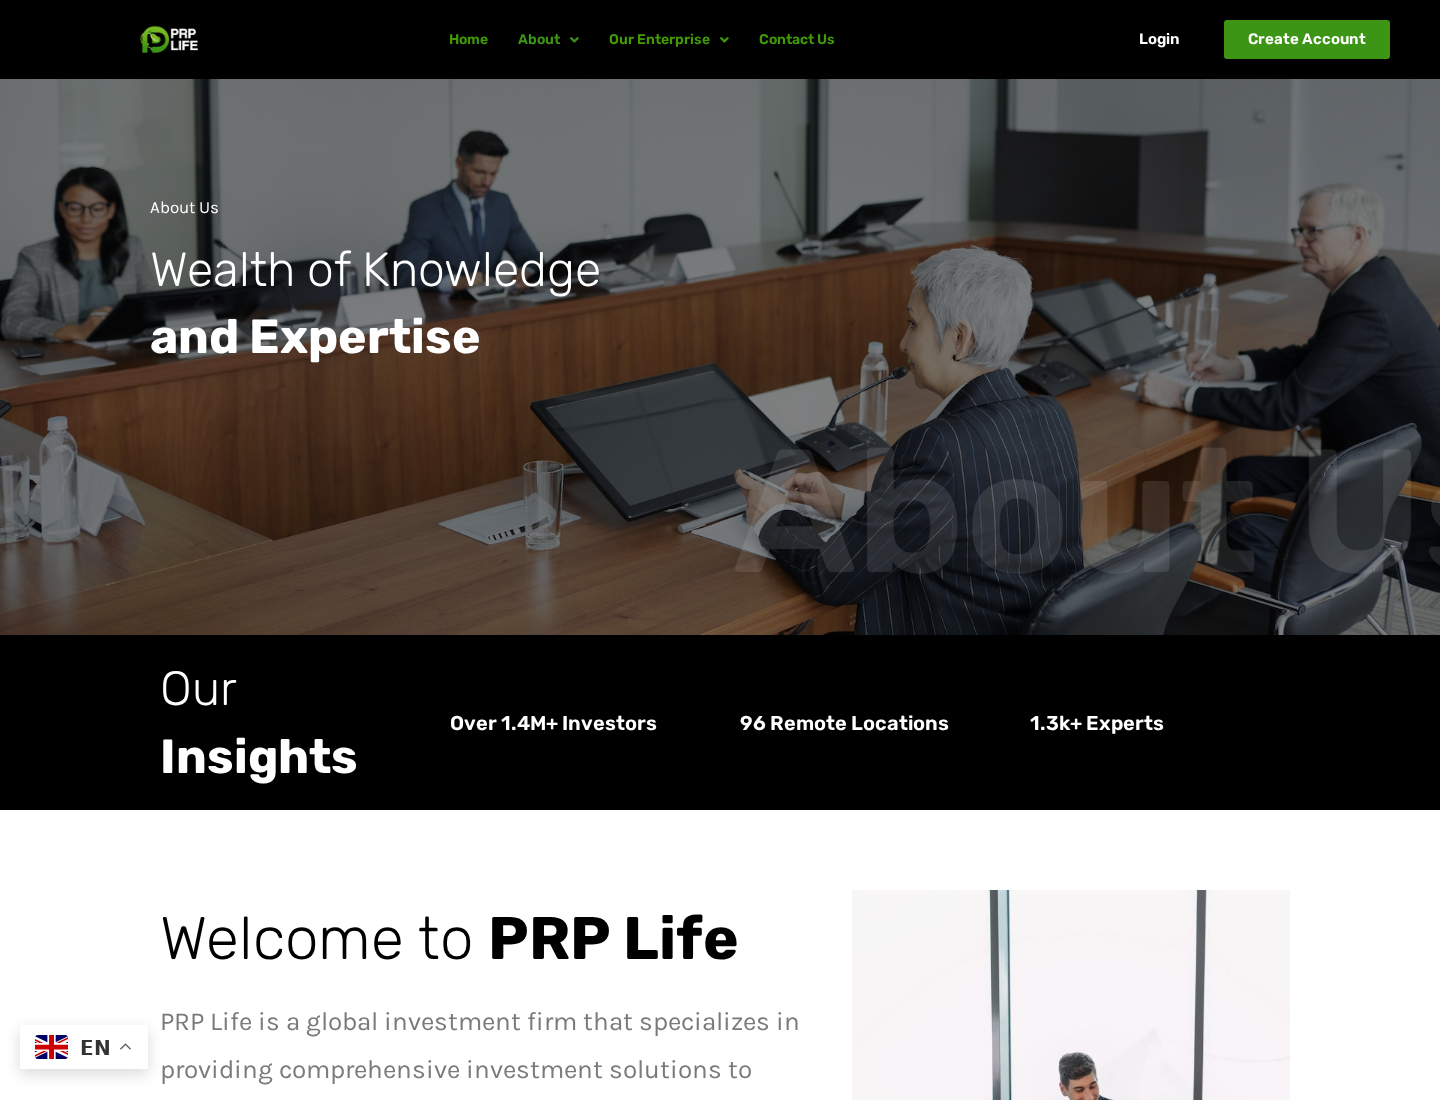
The public website presents a broad wealth-management business
PRP Life promotes an exclusive wealth club and describes investment areas including funds, property, securities, and retirement. Its registration buttons lead toward account.prplife.com.
That creates the appearance of an organized financial business with several divisions. It does not, by itself, verify assets, account custody, or permission to serve you.
Likewise, claimed historical performance needs an independently verifiable record. A percentage displayed by the business is not the same thing as audited customer returns.
Separate the warning from promises made to an individual investor
Australia’s Moneysmart investor alert list also identifies PRP Life, with prplife.com, as unlicensed. Its entry is dated January 22, 2026.
- The exact platform and domain match the regulatory records.
- A business presentation is not a financial-services authorization.
- An account balance is not evidence that the amount can be withdrawn.
- Further payments should not be used to test whether missing money can be released.
The warnings justify a decisive stop. They do not supply the transaction history, payment destination, or personal loss of every person who encountered PRP Life.
Why the Wealth-Club Presentation Can Lower Your Guard
The PRP Life homepage is not limited to one speculative token. It presents familiar financial categories that many people associate with professional wealth management.
Words about pensions, property, and diversification can make an offer feel more substantial than a trading tip in a messaging group.
That familiarity is not the same as verification. A description of an investment category does not demonstrate that the company owns the assets it discusses.
Nor does a photograph of a business setting establish who manages the money. The useful records concern the legal provider, custody arrangements, authorization, and financial reporting.
An exclusive club adds another persuasive element. You may feel that you have been offered access to an opportunity unavailable through ordinary channels.
That can turn questions into a social discomfort. You do not want to appear distrustful of a friend or lose the place supposedly reserved for you.
Resist that framing. Anyone seeking control of your savings should welcome independent checks, and no invitation makes a regulator’s warning less relevant.
If someone claims the warning refers to a different business, compare the domain and name. Here, the FMA entry expressly identifies prplife.com.
How the Investment Scam Pattern Works
The FMA explains a recurring pattern used by fake platforms. The stages below describe that warning framework, not a verified sequence experienced by every PRP Life user.
Step 1: An introduction gives the platform a trusted starting point
Investment approaches can arrive through advertisements, unsolicited contact, or a conversation with someone you already know. A referral can make an unfamiliar platform feel personally vouched for.
Ask what the person actually verified. Seeing an account, receiving a small payment, or knowing another member does not establish a licensed investment business.
If a friend introduced PRP Life, they may also be relying on what they were told. You can reject the offer without deciding that your friend knowingly deceived you.
Keep the relationship separate from the financial check. Independent records matter precisely because social confidence can bypass them.
Step 2: The website turns a conversation into an account
A professional-looking site gives the opportunity a place to live. Categories, staff descriptions, explanations, and registration buttons can make it resemble an established institution.
For PRP Life, the public site moves interested visitors toward an account subdomain. An account interface is infrastructure, not proof that invested funds are safeguarded.
Before registering anywhere, consider what personal information you would be supplying and why. Identity documents and banking details should not be handed over to resolve doubts.
With this platform, the regulatory warning is already a reason to stop before that handoff.
Step 3: An initial payment creates a reason to stay involved
In the FMA’s general pattern, a relatively small initial commitment can be followed by an apparent successful result. That experience encourages a larger transfer.
The psychological change is significant. Before paying, you are judging an offer. After paying, you may begin defending a decision and hoping it works.
A successful small withdrawal, if one occurs, verifies only that transaction. It does not prove the safety of future deposits or the platform’s financial position.
Do not send a trial investment to PRP Life as a safety experiment. The warning cannot be resolved by risking a smaller amount first.
Step 4: Apparent gains encourage a larger exposure
A platform can display a rising balance without demonstrating how the underlying return was generated. Numbers in a private account require independent support.
Separate your real transfers from the amount displayed as profit. A screen showing a gain is not a bank statement confirming money received under your control.
Also separate general market performance from your individual entitlement. An asset increasing in price does not establish that the platform bought it for your account.
If the next recommendation is to borrow, use pension money, or recruit relatives, stop. Pressure to increase exposure is not evidence that the investment improved.
Step 5: A withdrawal problem becomes another request for payment
The regulator warns that fake platforms may refuse withdrawals and demand additional fees or taxes. Such demands can turn one loss into several.
If this happens to you, do not treat the promised release as a reason to transfer again. Ask your bank, exchange, or local authority for help independently.
A fee stated inside the same platform is not self-verifying. Neither a document carrying a seal nor a message claiming regulatory authority makes the demand genuine.
Keep the exact demand, amount, destination, and explanation as evidence. Do not pay to find out whether the next promise is different.
Step 6: Recovery offers target the wish to undo the loss
Someone who knows you lost money may offer to trace it, unlock the account, or recover a balance. That knowledge does not establish an ability to help.
Be especially wary of guarantees paired with an advance payment, a wallet connection, or access to your bank account.
Legitimate reporting does not require sharing a wallet’s recovery phrase. Anyone asking for it is asking for control of the assets it protects.
Continue recovery through independently reached institutions. Do not let a new stranger take over the process simply because they sound more sympathetic than the original promoter.
Company, Contact, and Authorization Checks
Keep two versions of your evidence folder: a complete private record for institutions, and a redacted copy for any public warning you choose to share.
The private record can contain transaction references and account identifiers. A public post should not expose your passport, home address, account access, or another participant’s information.
If a promoter sends documents after you raise the warning, preserve those too. An explanation may help investigators understand the approach even when it does not resolve it.
The trading name must match the regulated provider
A financial check needs more than locating a business with similar lettering. The entity, domain, activity, and authorization must correspond to the actual offer.
PRP Life’s appearance on the FMA list is a direct domain match. A certificate for another company would not remove that warning.
Do not accept a screenshot of registration as the final answer. Search the regulator’s own record and use its independently published contact details if clarification is needed.
A contact number is not proof of investor protection
The PRP Life contact page publishes +1 602 428 6867 and info@prplife.com. These are listed contact details, not a tested support service.
A working telephone, if established, would show that someone can answer it. It would not demonstrate custody of assets, an authorized adviser, or a compensation scheme.
No phone call or inquiry was made for this article. People already involved should preserve any existing correspondence rather than rely on an undocumented conversation.
Ask who actually holds the assets
A website may discuss funds and securities while leaving customers unable to identify where their particular money sits.
Useful evidence would identify the account provider, custodian, relevant asset, ownership arrangement, and applicable protections. Brand imagery cannot substitute for those records.
Do not confuse the exchange you used to buy cryptocurrency with the investment platform receiving it. The first may be legitimate while the destination remains unsafe.
A warning is different from a criminal judgment
The FMA classifies the named operation in its fake-platform warning. Moneysmart separately records an unlicensed status. Those findings should be described accurately.
They do not establish an individual criminal conviction or every allegation circulating online. You do not need those additional claims to decline the investment.
The actionable conclusion remains firm: do not place funds with a platform matching these warnings, and stop increasing any existing exposure.
What to Do if You Have Fallen Victim to This Scam
-
Stop sending funds and pause referrals. Do not add money to meet a target, maintain a tier, solve a shortfall, or obtain an account release.
If you invited someone else, tell them about the official warning. Share the regulatory record without circulating private account information.
-
Record your actual transfers. List dates, amounts, currencies, payment methods, recipients, wallet addresses, and transaction identifiers.
Keep the advertised account balance in a separate column. That prevents a report from confusing money you transferred with gains displayed only by the platform.
-
Contact the institution used to send the money. Explain the suspected investment fraud to your bank, card provider, money-transfer service, or cryptocurrency exchange.
Ask whether the transfer can be recalled, reviewed, or flagged. Provide the receiving details promptly; recovery is uncertain and may depend on where funds have gone.
-
Preserve the account and communications safely. Save relevant statements, payment requests, promises, chat exports, and screenshots already available to you.
Do not transfer more, install new software, or connect another wallet merely to obtain evidence. Avoid exposing private keys, passwords, or identity documents in public posts.
-
Report to the relevant authority. New Zealand readers can report the platform to the FMA; Australian readers can use ASIC’s reporting routes.
Elsewhere, contact your financial regulator and appropriate fraud-reporting authority. A US internet-fraud report can be filed through IC3.gov.
Include the domain, the promoter’s contact route, and the payment timeline. Keep report references so later evidence can be added to the same case.
-
Protect any credentials or documents you supplied. Replace exposed passwords where they are used and review the affected accounts through their genuine services.
If identity documents were shared, ask the relevant issuer or local identity-theft service about proportionate protections. Do not assume that a password change retracts an uploaded document.
-
Deal separately with remote access. If someone operated your device, tell your bank and obtain trusted technical assistance before using it for further financial activity.
Reading an investment website alone is not evidence of malware. Device checks address a device exposure, not the missing investment or a blocked withdrawal.
-
Involve a trusted person before any further financial decision. A loss can create pressure to act quickly and privately.
Let someone help organize the records and screen follow-up approaches. You deserve practical support, not embarrassment or pressure to recover everything through another risky offer.
Frequently Asked Questions
Is the PRP Life warning about the same website?
Yes. The FMA entry names PRP Life and prplife.com. Compare that exact domain rather than relying on a similar company name supplied by a promoter.
Does an investment account prove my money is safe?
No. An interface can display information without establishing asset custody, authorized investment activity, or a customer’s ability to withdraw.
What does Moneysmart say about PRP Life?
Its investor alert list identifies PRP Life, prplife.com, as unlicensed. That is an authorization warning, not an endorsement of any claimed investment performance.
Should I make a small test deposit first?
No. Do not risk additional funds to test a platform already identified by regulators. Even an early payment back would not validate future investments.
Can paying a tax or unlocking fee guarantee recovery?
No. Stop and consult the sending institution independently. An additional payment demanded to release a displayed balance can deepen a loss.
What is the best first action if I already paid?
Stop further transfers, gather the real payment details, and contact the bank or exchange that sent the funds. Report promptly and reject paid recovery guarantees.
The Bottom Line
Do not invest through PRP Life. Its wealth-management presentation does not outweigh the FMA’s exact-domain fake-platform warning and Australia’s separate unlicensed listing.
If you already transferred money, stop adding to the exposure. Preserve transaction evidence, approach the sending institution, and pursue official reporting without paying another promised rescue fee.

Reviews & discussion
0 commentsShare a firsthand experience, or ask a question.
Community reviews
PRP Life
Moderated reader experiences, not an editorial verdict.
Start the conversation
Have a question or something useful to share? Add the first comment.