

The name sounds official: International Securities & Financial Compliance Authority. A contact using it may appear to know the language of regulation, verification, and financial paperwork.
Before you trust the title, check who is behind it. A genuine firm’s details can appear inside a completely unrelated approach.
The shf-isfca.com scam has a specific warning attached to it, and the distinction between the clone and the real business is essential.
Overview
The FCA explicitly identifies a clone
The UK’s Financial Conduct Authority lists International Securities & Financial Compliance Authority and shf-isfca.com in a clone-firm warning. Published July 24, 2026 and updated September 8, it says fraudsters are pretending to be an authorized firm.
The warning names shf-isfca[.]com, shf-ltd[.]com, and sec-holdings[.]org, along with +44 1972 222016 and +44 1690 888031. These are indicators listed by the regulator, not contact routes to use for verification.
The legitimate business is separate
The FCA identifies SHF Compliance Limited, reference number 1008590, as the genuine firm being impersonated. It explicitly states that the real business has no connection with the clone.
This is not a conclusion drawn from a poor review or an unhappy customer’s complaint. The regulator has identified impersonation. That is the basis for describing the clone as a scam.
A useful identity check compares several details together:
- The exact legal name in the official regulatory record.
- The reference number and what it applies to.
- The contact details you found independently.
- The website and address used by the person approaching you.
- The specific service or action the person is asking you to accept.
The warning does not establish every payment story
The FCA notice identifies the clone and its contact details. It does not provide a complete victim conversation, verified checkout, fee schedule, or universal sequence of payment demands. We have not independently captured those elements.
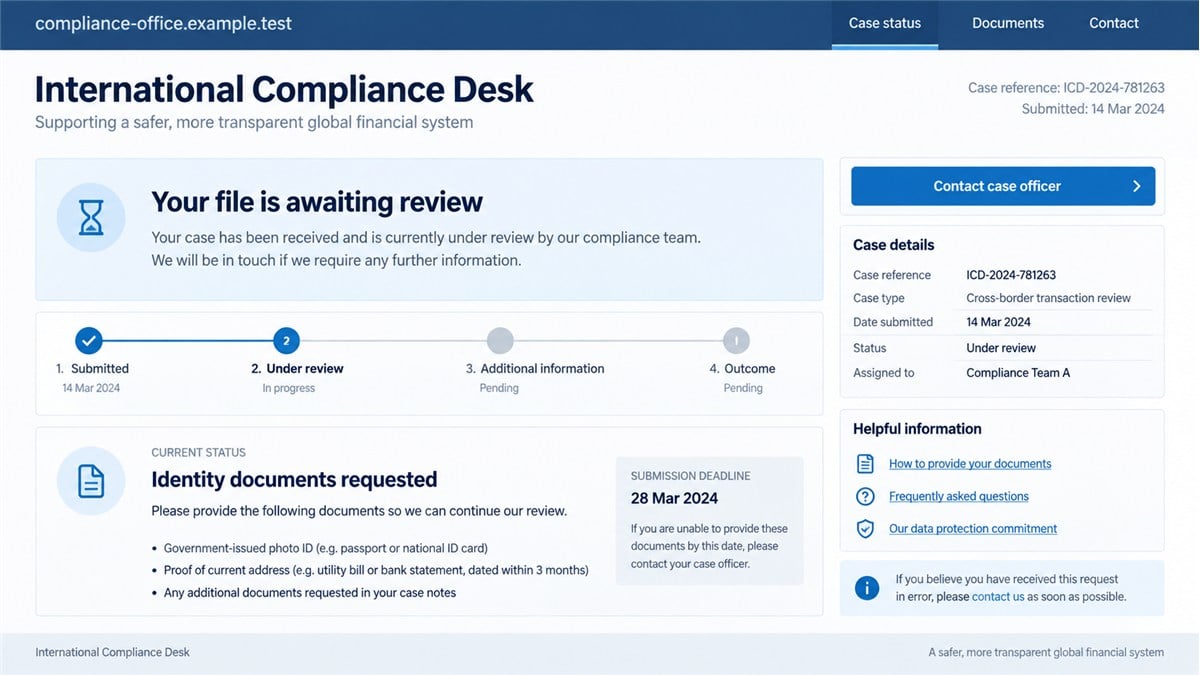
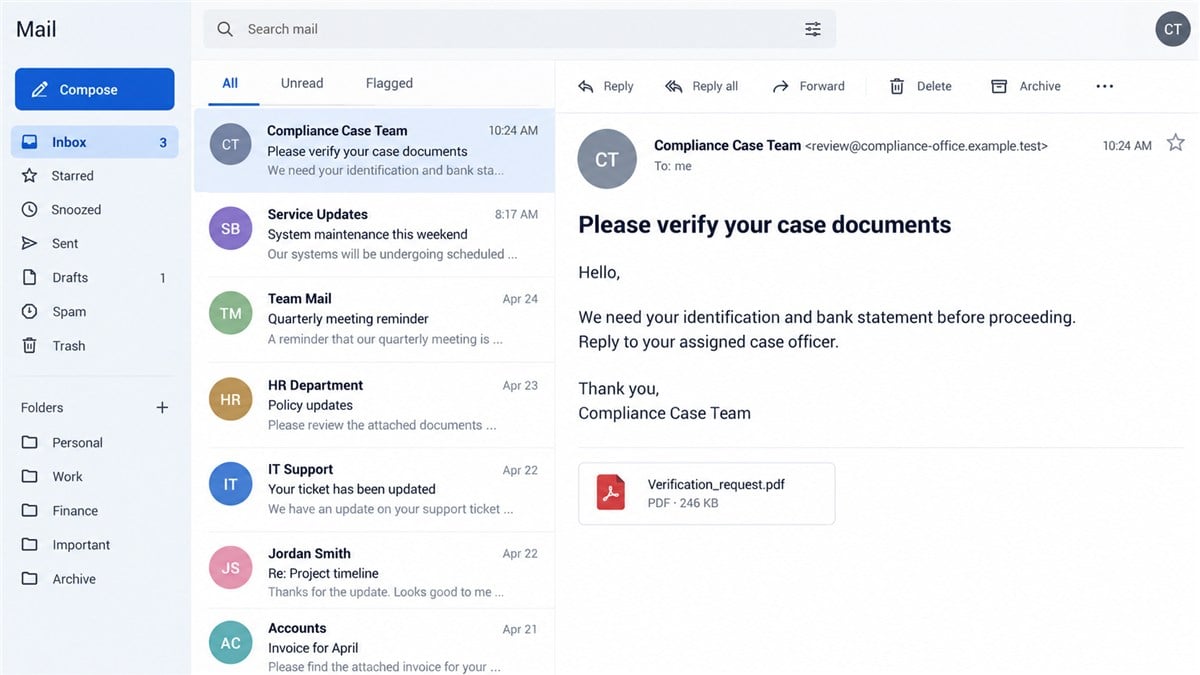
Accordingly, this article does not claim that every approach involves the same investment, recovery promise, or charge. The illustrations use fictional interfaces to explain impersonation. They are not screenshots of the named domains.
The practical issue is already clear: do not treat a contact from the named clone as a representative of the authorized firm. Verify any related approach through the regulator’s own records before providing information or money.
How a Clone Borrows Credibility
A clone does not need to invent an entire business history. It can borrow enough genuine information to survive a quick search. A recipient finds a real company or registration number and assumes that the person who supplied it must work there.
That assumption is the gap. A public record proves that the listed organization exists or holds a particular status. It does not prove that a stranger has permission to use its identity.
Think of a registration number like a name on a directory. Anyone who can read the directory can repeat the name. You still need to establish whether you are communicating with the person or organization listed there.
The word “Authority” can create a second shortcut. It sounds like a public body, so a recipient may treat a request as an obligation. A title chosen by the sender cannot establish official powers.
Do not let formal language move the conversation past the identity check. Before discussing documents, deadlines, or financial instructions, establish who is contacting you through a source they do not control.
How the shf-isfca.com Scam Uses Impersonation
Step 1: An official-sounding identity is presented
The named clone uses language associated with financial oversight and compliance. That presentation encourages the recipient to approach the contact as someone with expertise or institutional authority.
The FCA warning confirms the false connection to an authorized firm. It does not establish that every recipient first encounters the clone through the same channel. Apply the identity check whether the approach arrives by email, phone, message, or a website referral.
Step 2: Genuine details can be mixed with false contact routes
A person may supply a real firm’s name or reference number while directing you to a different website, email address, or telephone number. Finding one correct detail can distract from the mismatch in the others.
Use the regulator’s record as your starting point, rather than using the sender’s details to construct the search. Compare the entire identity, including the actual contact route and the permissions relevant to the proposed service.
Step 3: The conversation moves inside the clone’s own channels
A website, case officer, or email thread can make communication feel organized. But if all of those channels came from the same unverified source, they do not independently confirm one another.
Leave that loop. Open the regulator’s website yourself and use the listed contact details for the genuine firm. Ask whether the person and approach are known to it.
Step 4: A requested action creates the exposure
Depending on the approach, the risk may involve information, money, or access to an account. Do not assume that a document request is harmless merely because payment has not yet been mentioned.
This warning does not verify a particular document collection form or payment amount. The safe response is to pause any requested action until the identity is confirmed, rather than waiting for a specific script to appear.
Step 5: Continued correspondence can make withdrawal feel difficult
After exchanging several messages, people may feel that they have started a formal process. A case number or named contact can reinforce that impression. Neither creates an obligation to keep dealing with an impostor.
If the details match a clone warning, stop contact and preserve the evidence. You do not need to finish a supposed procedure, pay a closure charge, or disclose more information to justify leaving.
Company, Address, and Contact Checks
The legal name must match the relationship
SHF Compliance Limited is the genuine business named by the FCA as the impersonation target. Keep that distinction explicit if you report the approach. Say that someone claimed a connection to the firm rather than accusing the real firm of contacting you.
If another business name appears on a document or proposed payment, do not assume it is an affiliate. Ask the genuine organization to confirm any claimed relationship through its independently verified contact channel.
A real address does not locate the scammer
An address copied from a business record belongs to the record, not necessarily to the person writing the email. It should not be described as the scammer’s office without evidence.
The same care applies to maps and building photographs. They can show that a location exists while providing no connection to the contact. Do not travel to an address or contact its occupants to confront someone based on a copied footer.
Do not verify a number by calling that same number
The two numbers in the warning are evidence of contact details used by the clone. A person answering either one cannot independently establish the legitimacy of the operation.
Numbers can also be spoofed or change hands over time. Report the details and dates accurately. Avoid treating the identity of an unrelated subscriber or carrier as proof of who organized the fraud.
Trace any proposed transaction before authorizing it
A payment request needs its own verification. Check the recipient, purpose, and relationship to the genuine firm. Do not let a familiar company name elsewhere in the correspondence substitute for those checks.
If you already paid, preserve the account details and transaction reference for your bank. A recipient name can help an investigation, but it is not enough on its own to identify the organizer of the scam.
A Better Way to Check a Financial Contact
If someone forwards you the warning, compare the exact domain and contact details with the approach you received. Similar names can belong to unrelated businesses. The warning is a reason to reject the identified clone, not to accuse every company with similar initials.
For a different domain, save the evidence and check it separately. A new spelling might be another impersonation attempt, but that connection needs evidence. Do not assume that every financial email is part of this operation simply because it uses the word compliance.
Keep a private record of the first contact, the claimed organization, and any request that followed. That sequence helps a bank or investigator understand the approach. It is more useful than trying to discover the operator’s identity by continuing the conversation.
Be cautious about anyone offering to investigate or recover money afterward. The separate fake IC3 recovery scam shows how criminals can also borrow law-enforcement identities. An official-sounding recovery offer needs the same independent checks as the original contact.
Start with an independently opened regulator website. Avoid using a link supplied by the contact, even if it appears to lead to a register. A copied register page can look convincing while sending replies or inquiries elsewhere.
Search the exact firm name and reference number. Read what the record actually says. Registration, authorization, and permission for a particular activity are not interchangeable labels, and a stranger’s summary may omit the distinction that matters.
Next, use the contact details listed in the official record. Tell the genuine firm the name of the person who approached you and the service being offered. You can ask this without sending your passport or banking credentials.
Check warning lists as well. Absence from a warning list is not a guarantee because a new impersonation can appear before a notice is published. In this case, however, there is an explicit warning to use.
Finally, write down what was confirmed and by whom. A clear record prevents a later email from quietly changing the website, recipient account, or contact person while borrowing trust from the earlier check.
What to Do if You Have Fallen Victim to This Scam
-
Stop further contact and payments. Do not submit another document or pay a fee to close a case. Keep the correspondence available as evidence, but move any verification to channels you located independently.
-
Contact your bank if funds or payment details are involved. Explain that the FCA identifies the contact as a clone. Provide the payment date, amount, recipient, and reference. Ask the bank to assess recovery and account-protection options without assuming reimbursement is guaranteed.
-
List the information you disclosed. Distinguish between a name and email address, identity documents, account details, passwords, and authentication codes. That inventory helps the relevant providers decide what protective steps are appropriate.
-
Secure any exposed accounts. Change submitted passwords through official websites or apps. Review recovery details and unfamiliar sessions. If an identity document was shared, ask its issuing authority or an appropriate identity-support service about the next steps for your circumstances.
-
Preserve the evidence in one place. Keep emails, messages, attachments, website addresses, call times, and transaction records. Note the exact name used by the contact. Store sensitive documents privately rather than posting them in a public warning.
-
Report the clone to the regulator and local fraud-reporting service. Use contact routes from their official websites. Include a link or reference to the FCA warning and explain how the approach reached you. Reports of additional domains or contact details can be useful.
-
Check software if you installed anything. If a supposed compliance officer asked you to download a viewer or allow remote access, seek trusted technical help. Malwarebytes can assist in checking for malicious software. AdGuard can block some known malicious pages and ads, but cannot authenticate a financial representative.
-
Be alert to a second approach. A stranger who knows you lost money may offer recovery, compensation, or a new investigation. Verify that contact from scratch. Never treat detailed knowledge of your loss as proof that someone represents a regulator or law-enforcement agency.
Frequently Asked Questions
Is shf-isfca.com a confirmed scam?
The FCA explicitly identifies the name and domain in a clone-firm warning and says fraudsters are using the listed details. This is stronger evidence than an isolated complaint about service or investment performance.
Is SHF Compliance Limited the same organization?
No. The regulator identifies it as the genuine firm being impersonated and says it has no connection with the clone. Do not confuse the two when checking or reporting an approach.
Does a correct reference number prove the caller is genuine?
No. Public reference numbers can be copied. Verify the person and contact route through the official record, and check that any proposed activity matches the firm’s permissions.
What if the website is no longer available?
An unavailable site does not settle what happened earlier. Preserve existing messages, screenshots, and payment records. Use the regulator’s warning rather than trying alternate links sent by the same contact.
Can I get compensation automatically?
Do not assume that. The options depend on the payment and circumstances. Ask your bank and the relevant official service to assess your case. Avoid anyone promising guaranteed recovery for an advance fee.
Are the article images captures of the clone website?
No. They are fictional illustrations of official-sounding financial impersonation. They do not establish that the named clone used the exact wording, forms, or interface shown.
The Bottom Line
The shf-isfca.com scam borrows credibility from a real financial business. The FCA’s warning makes the separation clear: the clone and SHF Compliance Limited are not the same operation.
Use independently verified contact details before sharing information or authorizing payments. If you already interacted, preserve the record and involve your bank and the relevant reporting authorities promptly.








