

A Fluvius email says your annual charges were too high. There’s an apology, a specific refund amount, and a button to claim the money.
It looks like the sort of correction you might reasonably expect after an energy bill. The details around that button deserve a much closer look.
Overview
The refund comes from an impersonator, not Fluvius
The Fluvius refund email scam borrows the network operator’s branding to lure recipients into a false claim process.
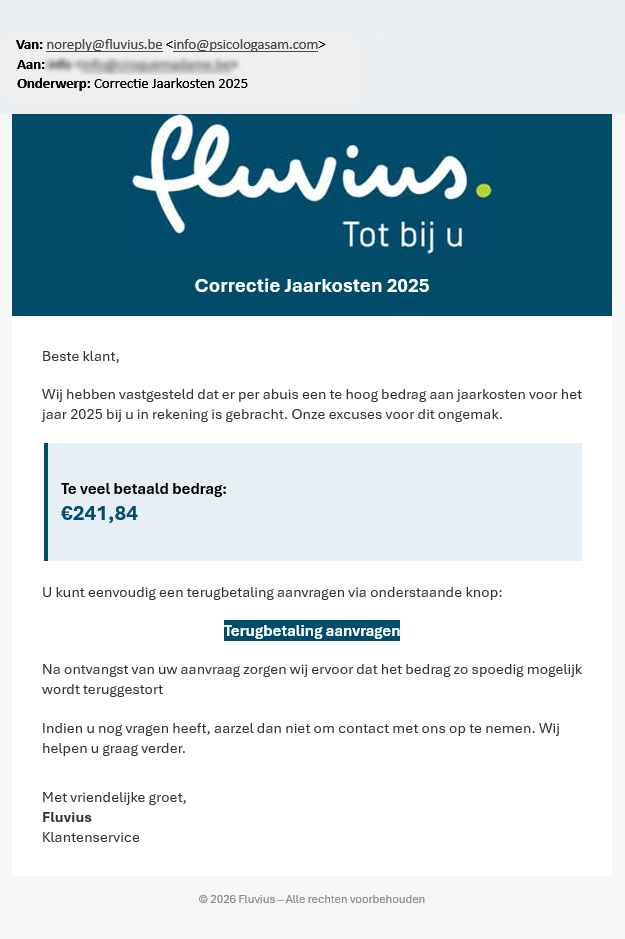
Fluvius publishes the message shown above among its confirmed phishing examples. The email offers €241.84 back for supposedly excessive annual charges.
The real Fluvius isn’t running this fraudulent offer. Criminals are using a familiar energy name to make a request for information seem routine.
A reassuring explanation hides the point where trust changes
The email explains a billing mistake and invites you to request repayment. It encourages action by promising money, rather than threatening a penalty.
At the top, the sender line displays a Fluvius-looking address alongside an unrelated address. The branding in the message doesn’t correct that mismatch.
The email shows the refund bait. If you followed its button, your next step depends on what the page asked for and what you supplied.
Real refunds still need an independently verified route
Fluvius says some prepaid customers can genuinely receive repayments. Its guidance distinguishes those situations from clicking an email link to supply financial details.
- Don’t begin the claim through an unexpected refund button.
- Open the operator’s official site separately if you need to investigate.
- Ask about your actual account or case rather than trusting a generic correction story.
- Keep bank passwords, card codes, and approval requests out of the refund conversation.
- Contact your bank quickly if you already supplied financial access or approved a payment.
What the Fake Annual Charges Email Actually Shows
The message is designed to look unremarkable. There’s a Fluvius logo, a customer-service tone, and an explanation that too much was charged for an earlier billing year.
The supposed overpayment appears in a prominent box. The amount is precise enough to feel calculated, rather than a vague promise of free money.
That precision isn’t evidence of a calculation involving your home. Anyone writing an email can choose an amount with two decimal places.
The request button follows the explanation. By the time you reach it, the message has already encouraged you to accept both the mistake and the repayment as genuine.
The sender header is more revealing than the polished body. A familiar display address beside an unrelated address should interrupt the story, not be overlooked because the logo matches.
Don’t rely on that single visual flaw as a permanent test. Another fraudulent version could hide its sender more convincingly or use a different pretext.
The safer question is whether you can verify the refund without using the email. If the repayment is real, an independent contact route can address it.
How the Fluvius Refund Email Scam Works
Step 1: An apparent billing correction reaches your inbox
The sender adopts the voice of customer support and presents the refund as money already owed. You don’t need to enter a contest or buy anything first.
That makes the request different from an obvious prize. The story depends on something ordinary, a billing adjustment, happening in your favor.
You may also be expecting energy-related correspondence. That doesn’t authenticate this email or prove the sender knows your actual payment history.
Step 2: The message supplies the reason and the amount
The displayed example attributes the repayment to excessive annual charges. The named amount becomes the focus, while the identity of the sender receives less attention.
Pause before accepting the explanation. Does the claim fit a real case you recognize, and can the operator confirm it through its established customer channels?
Knowing your name or address wouldn’t settle that question either. Personalization can make a fraudulent request more persuasive without making it authorized.
Step 3: The refund button moves you away from the trusted relationship
The email asks you to begin through its own button. That is the handoff: the recipient lets an unsolicited message choose where financial information will be entered.
Visible button text isn’t the destination. A reassuring word such as repayment can cover a link to an unrelated website.
Don’t open the page simply to see whether it looks professional. A copied logo and a convincing form are inexpensive substitutes for a genuine relationship.
Step 4: The claim becomes a reason to request sensitive information
A false refund page can seek information that helps criminals impersonate you or reach financial accounts. The exact fields may differ between versions.
Receiving a repayment isn’t a reason to disclose your banking password, a card PIN, or a code authorizing an unrelated action.
If a banking screen appears, read the actual transaction or login request. Don’t let the promised incoming money distract you from an approval that sends something out.
After Following the Refund Button
The next action depends on what happened after the email. Merely seeing it is different from entering login details, supplying card information, or accepting an approval.
Keep those events separate when speaking to support. The bank needs the actions you completed, not only the amount the fake email promised.
Don’t wait for a refund confirmation from the sender before reporting exposure. A further reassuring message can’t undo information already disclosed.
The Refund Exception That Scammers Can Exploit
A real energy refund is possible. The reason to reject this email is its fraudulent claim route, not a rule that customers never receive money back.
Fluvius specifically explains that prepaid customers may have paid too much and can receive an email about reimbursement.
The important distinction is the route used to provide financial information. Fluvius says it doesn’t ask customers to click a link for that purpose.
You can use its independently obtained contact information to ask about a repayment. You don’t need to continue through the message that raised the question.
Nor does a real refund somewhere on your account validate every email mentioning one. A genuine entitlement and a fraudulent claim page can exist at the same time.
If someone helps manage your energy payments, check with them before acting. They may recognize the actual billing arrangement or know that no adjustment was requested.
For rented accommodation or shared meters, don’t submit another person’s financial information to resolve uncertainty. Ask the party responsible for the account through your usual contact.
Check the Message Without Feeding the Claim Page
Start with your own account context
Look at existing records you already trust, not documents attached to the suspicious email. A real case number should have a relationship to an actual interaction.
An unexpected promise aimed at a noncustomer is especially questionable. Still, being a customer doesn’t make an incoming message genuine.
Don’t give the sender more identifying information to see whether they can find your case. That lets a supposed verification exercise become another collection step.
Read addresses as addresses, not familiar words
For email, the visible sender name and the underlying address can differ. Expand the details if your mail app makes that possible without opening links.
For a website, a company name somewhere in the address isn’t enough. In fluvius.refund-review.example, the controlling domain isn’t fluvius.be.
That fictional address illustrates the distinction; it isn’t a live campaign destination. Don’t search for a fraudulent link when the real operator’s site can answer your question.
Don’t turn uncertainty into a test payment
If a supposed refund asks for a fee or a confirming transfer, stop. Don’t send a small amount to find out whether the larger repayment will follow.
Such a request would require its own verification, not an assumption that the email’s logo makes it safe.
Similarly, don’t accept an unexpected identity or banking prompt as a harmless check. Confirm the action through a service you opened independently.
What to Do if You Have Fallen Victim to This Scam
-
Stop using the email’s claim route. Close the page, don’t complete additional fields, and don’t reply with documents or account information.
Save the message before removing it if you need to report the attempt. Avoid forwarding a working link to family members as a warning.
-
Describe your exposure accurately. Note whether you only clicked, entered contact details, supplied financial information, shared credentials, or confirmed a banking request.
You don’t need to know what the criminals did afterward before asking for help. Your completed actions are enough to start the assessment.
-
Call your bank when financial access was involved. Explain the false Fluvius refund and any codes, card details, or approvals you supplied.
In Belgium, use Card Stop for relevant payment-method blocking when appropriate, while discussing banking-app access directly with your bank.
Ask about suspicious transactions and possible recovery without assuming that a promised repayment ever existed.
-
Replace any password entered on the false page. Open the real service yourself on a trusted device and review available account-security settings.
If you reused that password, replace it wherever else it was used. Prioritize the email account that receives password-reset messages.
-
Check for unwanted downloads or permissions. If the page prompted an installation or you opened an unexpected file, address that software exposure separately.
Malwarebytes can help examine a supported device for threats. Don’t confuse a software scan with revoking stolen credentials or reversing an authorized payment.
AdGuard may reduce some future contact with malicious sites and ads. Keep checking the destination yourself; no filter can certify every refund form.
-
Verify any genuine repayment directly with Fluvius. Reach its official site or established support rather than the contact details included in the suspicious offer.
Tell support which message you received and ask about your real situation. Don’t let embarrassment stop you from clarifying an actual account issue.
-
Report the attempt and retain the useful evidence. Keep the sender details, email, website address if available, and any financial references.
Belgian recipients can send suspicious messages to verdacht@safeonweb.be. If funds were stolen, report the loss to the police as well as the bank.
Who Can Actually Confirm the Refund?
If a message includes a meter or customer identifier, compare it with your own records. Don’t let a recognizable number replace verification of the requested action.
Those details can make a conversation sound personal, but they aren’t banking authorization. A real account reference doesn’t entitle an email sender to your card codes.
Keep the energy operator’s role separate from your bank’s role. The operator can clarify a repayment; the bank can explain or stop a suspicious financial action.
Calling one doesn’t automatically notify the other. If you supplied banking access while pursuing the refund, make both contacts through their genuine channels.
For a joint household account, tell the other person what happened before they receive another message about the supposed adjustment.
They can help compare records and spot follow-ups, without reopening the claim page or submitting the same information a second time.
Help Someone Who Is Still Waiting for the Refund
Someone who entered their details may keep refreshing their bank account, hoping the money arrives. That can delay the call that actually protects them.
Shift the conversation from the promised amount to what they submitted. Did they type a password, read a code, or confirm an action?
Offer to help reach genuine bank support immediately. Don’t ask them to reopen the claim page to reconstruct every detail first.
If only basic information was exposed, explain the possibility of convincing follow-up messages without suggesting that financial loss is inevitable.
A second caller may refer to the refund and claim to fix a processing problem. Treat that as another unverified approach, even if the story sounds connected.
Keep one trusted incident record so the person doesn’t need to retell the experience to every stranger who claims to help.
Frequently Asked Questions
Is the €241.84 Fluvius annual charges email authentic?
Fluvius includes that message in its phishing examples. Don’t use its refund button or provide financial details through the claim route it supplies.
Can Fluvius ever refund a customer?
Yes. Its guidance describes genuine repayments for some prepaid customers. Verify your own situation independently rather than treating an unsolicited claim link as authorized.
Does a Fluvius logo prove the email is genuine?
No. The example uses recognizable branding despite an unrelated sender address. A polished design doesn’t establish who controls the message or its destination.
What if I clicked but entered nothing?
Leave the page and don’t continue. Check whether anything downloaded or any permission was granted; clicking alone doesn’t prove banking details were stolen.
Should I approve a bank request to receive the refund?
Don’t approve an unexpected request on the email’s instructions. Read the action carefully and ask your bank through verified contact if anything is unclear.
Who should I contact after providing financial information?
Contact your bank promptly and explain exactly what you shared or confirmed. Use genuine Fluvius support separately to establish whether any real repayment is due.
The Bottom Line
Don’t claim a Fluvius refund through this unsolicited email. The documented message uses a believable billing correction to move you toward an untrusted financial-information request.
Verify any actual repayment directly with Fluvius. If you already exposed banking access, contact the bank now rather than waiting for the promised money.

Join the discussion
0 commentsShare your experience or ask a question about this article.
Discussion
Start the conversation
Have a question or something useful to share? Add the first comment.