

A message says your OTC card needs verification before you can use it again. When that card helps with everyday essentials, an interruption sounds urgent.
The first thing to check is not the form in the message. It is whether the request has any connection to your actual plan.
Overview
The scam turns a real benefit into a reason to disclose information
An OTC card scam uses an over-the-counter benefit, or the promise of one, to obtain card details, account access, or personal information through deception.
The legitimate card or health plan is not the scam. The problem is a stranger pretending that their message, call, or form is an authorized benefits process.
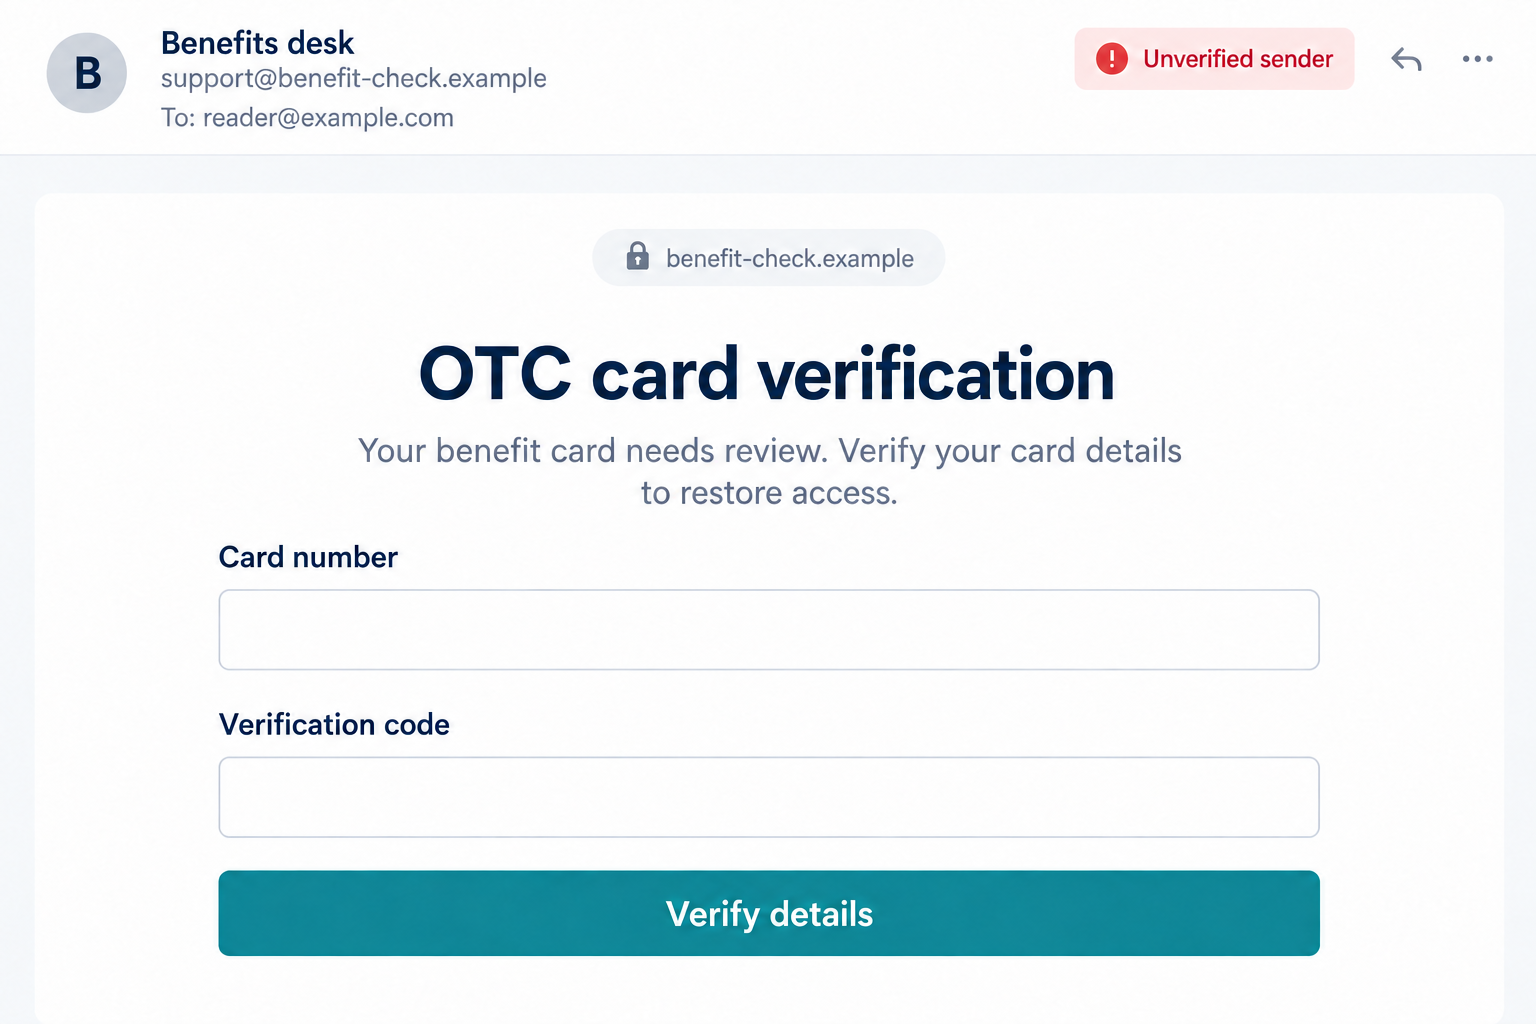
The lead image is an illustration of that approach, not a captured plan notice. Its example address and empty form do not connect to a real account.
A benefit-card problem and a medical claim are different issues
A card can provide access to restricted benefit credits. A Medicare or member number identifies a person within a health-coverage system. Those credentials should not be treated interchangeably.
Which information you share affects the response. Missing card credits need the card’s transaction process; unfamiliar medical billing needs the relevant claims process.
A genuine benefit also has rules. A declined purchase, an eligibility question, or a changed allowance does not by itself establish fraud.
The plan’s established channel is the place to start
Before responding to an unexpected verification request, ask yourself:
- Do I already have this card through a known plan?
- Does my own account show the problem being described?
- Which number is requested: card, member, Medicare, or bank account?
- Am I being asked for a password, code, payment, or document?
- Can member services confirm the request without using the sender’s contact details?
You can answer those questions without filling in the form. Start with the plan paperwork or account you’ve already used.
What a Real OTC Benefit Card Does and Does Not Establish
Coverage depends on the actual plan
Some health plans provide credits for eligible over-the-counter products. Other allowances or rewards may share a card, but their rules and eligible purchases can differ.
UnitedHealthcare’s official UCard information, for example, describes member tools for balances, participating stores, and plan-dependent benefits.
That is an example of a real program, not a promise that everyone qualifies. Another issuer may use different systems, terms, or card features.
Do not assume an advertisement’s food, utility, or cash claim describes your coverage. Ask the plan about the particular benefit and eligibility rules.
The Medicare card is not a general shopping account
Your Medicare number and a supplemental spending benefit serve different purposes. A caller should not blur them together to make a request seem routine.
Medicare’s card guidance explains how to protect the Medicare number and distinguish it from a health plan’s card.
If an OTC-shopping question turns into a demand for your Medicare number, pause. Ask your own plan why that number would be needed.
Use verified channels for legitimate administrative checks. Refusing an unknown caller’s demand does not mean refusing to resolve a genuine issue with your benefits.
How the OTC Card Scam Works
Step 1: A card problem or extra allowance creates an opening
The approach claims something useful is waiting or something important will stop. A card needs activation, access is supposedly blocked, or additional benefits require confirmation.
These stories work because they resemble questions real members have. If a purchase recently failed, a message about a blocked card may seem to explain it.
The coincidence does not establish a connection. Keep the genuine purchase problem separate from the explanation introduced by an unexpected sender.
Step 2: The contact presents itself as your benefits administrator
A message may use health-plan language, while a caller introduces themselves as a benefits representative. Familiar terminology can make the exchange sound like routine customer service.
A person knowing your name or plan does not prove they are authorized. Do not complete the identity check by supplying the missing sensitive details.
UnitedHealthcare’s Medicare fraud guidance acknowledges legitimate plan contacts while warning about impersonators and requests for valuable personal information.
The useful response is independent contact, not arguing about the incoming number. End an uncertain conversation and call the plan using your established materials.
Step 3: Verification becomes a request for credentials
A linked page or supposed representative asks for card or account information. The request may be described as restoring access, confirming ownership, or checking eligibility.
What matters is where the information goes. Calling a field verification does not make the recipient a legitimate administrator.
A password or code may provide access to an online account. Card details may enable misuse where accepted. Do not assume every card system works identically.
Some cards use features that others lack. There is no universal OTC PIN, online checkout, or transaction-approval sequence that makes an unsolicited form trustworthy.
If a benefits form suddenly wants your bank login, stop there. Checking a spending allowance shouldn’t require handing an unknown website the keys to a separate account.
Step 4: The promise expands beyond the original card question
A supposed bonus or free medical item can introduce new requests for insurance details. You may think you are confirming a benefit while disclosing a different credential.
Health-plan fraud warnings describe free-gift and medical-item offers used to obtain personal information. An item sounding useful does not establish that its sender is authorized.
Confirm actual coverage before accepting an order. Do not let a stranger turn a question about shopping credits into permission for an unfamiliar service.
Not every version includes medical equipment or billing. Keep those possibilities separate from a confirmed card transaction, and report only what actually happened.
Step 5: Missing credits or account changes reveal the exposure
The first sign of misuse may appear in genuine transaction history rather than the original conversation. Review the actual record, not a balance displayed by the suspicious page.
Compare unfamiliar entries with receipts and household purchases before drawing conclusions. A different merchant description deserves checking, not an immediate accusation against the retailer.
If an entry remains unexplained, contact the issuer promptly. Give it the transaction details and your account of the suspicious interaction.
Do not return to the sender for a refund. That gives an unverified contact another opportunity to ask for codes, documents, or payment.
Check a Missing Balance Without Falling for a Second Trap
Use the genuine transaction history
Open the member app or website through the route supplied with your card. Look at the relevant credit category, recent transactions, and available balance.
A plan may separate different credits or rewards. Check which balance a purchase used before deciding that the overall account is wrong.
Keep the date, amount, merchant description, and any reference visible in your private record. Do not post a screenshot containing the card number or member details.
If you cannot access the account, use member services from the card or original plan paperwork. A newly received search advertisement is not a replacement for that route.
Ask about ordinary reasons a purchase failed
A product, store, balance category, or coverage rule may explain a decline. Ask the plan to check the specific purchase instead of assuming the card needs reactivation.
Use your receipt or attempted-purchase details to describe the problem. Avoid sending an unredacted card photograph to a contact who has not been verified.
Real benefit rules can change. Confirm the applicable plan year and your own documents rather than treating another person’s allowance as a promise about your account.
Check medical records only when that exposure is relevant
If you disclosed a Medicare or member number, ask the appropriate program about claims monitoring. A card balance and a medical claim are not the same record.
Look for services or supplies you do not recognize, and ask about discrepancies. Do not assume that every unfamiliar code is evidence somebody stole your identity.
If you only disclosed a benefit-card credential, tell the issuer that precisely. It can help determine which systems need attention without spreading the problem across unrelated accounts.
Ask how to access legitimate benefits during replacement
A replacement process can interrupt ordinary purchases. Ask the plan whether another authorized method is available and which instructions apply while the card is unavailable.
If you pay another way, retain the receipt. Do not assume the expense will be reimbursed; ask about eligibility and any required approval before relying on repayment.
Be wary of a new caller offering a faster replacement. A genuine support reference does not authorize an unrelated person to collect additional card or banking information.
What to Do if You Have Fallen Victim to This Scam
-
Stop disclosing information to the suspicious contact. Do not complete another verification page, repeat a code, or accept a transfer to a supposed supervisor.
Save the message or voicemail and note when you responded. You do not need to remain in contact to obtain more evidence.
-
Contact the plan or card administrator immediately. Use the number printed on your genuine card or an established member-service route. Explain that information may have reached an impersonator.
Ask whether the card can be restricted, replaced, or otherwise protected. Do not assume a lock option exists or protects every type of credit on your particular card.
If the card is also used for other plan functions, ask how replacement affects those functions. Obtain instructions for accessing legitimate benefits while the matter is reviewed.
-
Report questionable transactions individually. Give the date, amount, merchant, and reference for each entry you cannot explain. Keep the complaint number and any documents requested.
A published UCare cardholder agreement illustrates why the specific terms matter: it provides reporting procedures without guaranteeing reimbursement.
Ask your own issuer about deadlines, investigation steps, and whether written follow-up is required. Do not borrow another plan’s time limits or assume ordinary bank-card protections apply.
Request a written explanation of the outcome when available. Keep receipts and communications together so you can answer questions without retelling the entire incident from memory.
-
Secure an exposed benefits account. Change its password through the genuine service and address reuse on other accounts. Review recovery contacts and available sign-in protections.
If you provided a code, tell support which message it came from and what it appeared to authorize. Avoid guessing that the code was harmless.
If your card uses a PIN, follow the issuer’s verified reset routine. Never choose or confirm one on a page supplied by an unknown sender.
-
Protect insurance identifiers if those were shared. Notify the health plan about a disclosed member number. For Medicare-number misuse or related threats, use Medicare’s own assistance route.
Ask how to review claims and flag unfamiliar activity. Keep the card-credit complaint separate but cross-reference it if the same interaction exposed both credentials.
A disclosure does not prove a claim has already been submitted. Continue checking the relevant records rather than waiting for the sender to tell you what happened.
-
Contact your financial provider if bank details or money were involved. Explain the deception, the information provided, and any payment you approved.
Ask about the options for that account or payment method. The FTC’s recovery guidance can help organize this part of the response.
A bank cannot necessarily restore restricted health-plan credits. The issuer handling a benefit-card transaction and the bank handling a separate payment may need different reports.
-
Make an identity-recovery plan when necessary. If you disclosed a Social Security number, identification document, or broader personal record, visit IdentityTheft.gov for exposure-specific guidance.
Keep sensitive numbers out of public warnings and unrelated complaints. Describe the type of information involved before sending documents through an official reporting process.
-
Prepare for follow-up and get help if needed. Tell a trusted person what happened if you want assistance reviewing statements or contacting the plan.
With your permission, they can help record questions and reference numbers. They do not need to publish your records or take over decisions.
Reject unsolicited offers to restore benefits or recover credits for a fee. Work through the actual issuer, and report the impersonation through its verified fraud channel.
Frequently Asked Questions
Are OTC benefit cards themselves a scam?
No. Genuine plan-based cards exist. The scam is an unauthorized contact or page using that benefit to obtain information or money.
Does everyone on Medicare receive the same spending card?
No. Benefits depend on the plan and eligibility. An advertisement cannot establish your entitlement to a particular card or allowance.
Does a declined OTC purchase prove that someone stole my credits?
No. Check the balance, item eligibility, participating store, and plan rules. Ask the issuer to investigate transactions you still cannot explain.
Should I enter a code to restore the card?
Not in an unsolicited link or for an unexpected caller. Use the genuine process your issuer confirms independently.
Will the issuer automatically refund missing benefit credits?
Do not assume that. Report promptly and ask about your agreement’s dispute process, deadlines, and possible remedies.
Can a genuine health plan call about my benefits?
Yes. That is why independent verification matters. End an uncertain call and contact the plan through information you already trust.
The Bottom Line
Do not verify an OTC card through an unexpected message or caller. Check your actual benefit and transaction record through the plan’s established channels.
If information was disclosed or credits are missing, contact the issuer promptly. Protect any separate account or insurance identifier involved, and keep the relevant reports and evidence.

Join the discussion
0 commentsShare your experience or ask a question about this article.
Discussion
Start the conversation
Have a question or something useful to share? Add the first comment.