

A voicemail mentions back taxes, missed filings, and a resolution program that may not stay available. You start wondering whether an old tax problem slipped past you.
The Tax Help and Filing Adjustment Office scam uses that uncertainty as its opening. Before returning the call, separate the message’s official tone from its actual authority.
Overview
A department-like name makes a sales call sound official
Reported tax-themed calls use names such as Tax Help and Filing Adjustment Office, with similar labels including Tax Health Office.
The language suggests an existing file, unresolved taxes, or eligibility for relief. A recipient may hear a government concern even when the caller has not established one.
A department-like name does not identify an IRS office or show that the speaker has access to your tax records.
The scam warning concerns deceptive calls and their requests. It does not establish that every real business with a similar name committed fraud.
The hook combines a problem with a shortcut
“Back taxes” creates anxiety. A “limited-time program” offers relief. Together, the phrases encourage a callback before you have checked whether either applies to you.
The IRS warns about tax impersonators and misleading debt relief pitches, including pressure for money or personal information.
There may be a real tax issue underneath your concern. That does not make the person who left the voicemail a legitimate way to resolve it.
Nor does sounding like a helpful private adviser excuse falsely implying government authority or a guaranteed outcome.
Focus on what the caller can substantiate
Before discussing payment or sharing records, identify the claim you are being asked to accept:
- Which tax year, notice, or balance is supposedly involved?
- Is the caller claiming to be government staff or a private service?
- What legal business name and professional identity can be checked independently?
- Is the proposed fee for private work or represented as a tax payment?
- Can you review written terms without losing the supposed opportunity?
If the caller cannot answer clearly, do not let the frightening opening supply the missing facts. Check your real position elsewhere.
What the IRS Actually Says About Contact and Relief
“The IRS never calls” is not an accurate rule
The IRS normally makes initial contact by mail, but it also describes legitimate phone contact and some automated messages.
Opt-in electronic communications exist too. The useful distinction is not whether any call or text is possible, but whether this request can be independently authenticated.
A genuine-looking voicemail can still be deceptive. Conversely, a brief message that omits private account details is not automatically proof of a scam.
Do not rely on tone, the presence of a recording, or the word “office.” Compare the claimed matter with your own records and an official channel.
A threat of immediate arrest unless you pay the stranger is a different matter. The IRS identifies such threats and urgent demands as scam warning signs.
Tax relief is not a guaranteed phone discount
An offer in compromise can allow eligible taxpayers to settle for less than the full debt. Eligibility depends on financial circumstances and program requirements.
A caller cannot establish that outcome from a generic voicemail. Your income, expenses, assets, and compliance situation matter to the actual process.
Be wary of a large savings promise that arrives before anyone has properly assessed those facts. A confident percentage is not a decision from the IRS.
You can explore official options directly. Paying an unknown intermediary is not a required first step simply because the message says a relief window is closing.
A fee needs a purpose, not just a warning label
Private tax professionals can charge for legitimate work. The IRS’s own offer process also has application and payment requirements, with relevant low-income exceptions.
The current official page lists a $205 application fee. That does not authenticate a caller requesting a similar amount or make every upfront professional fee fraudulent.
Ask what the fee buys, who receives it, and what happens if you do not qualify. A vague payment to “activate your file” needs more explanation.
How the Tax Help and Filing Adjustment Office Scam Works
Step 1: A voicemail introduces a tax concern you did not request
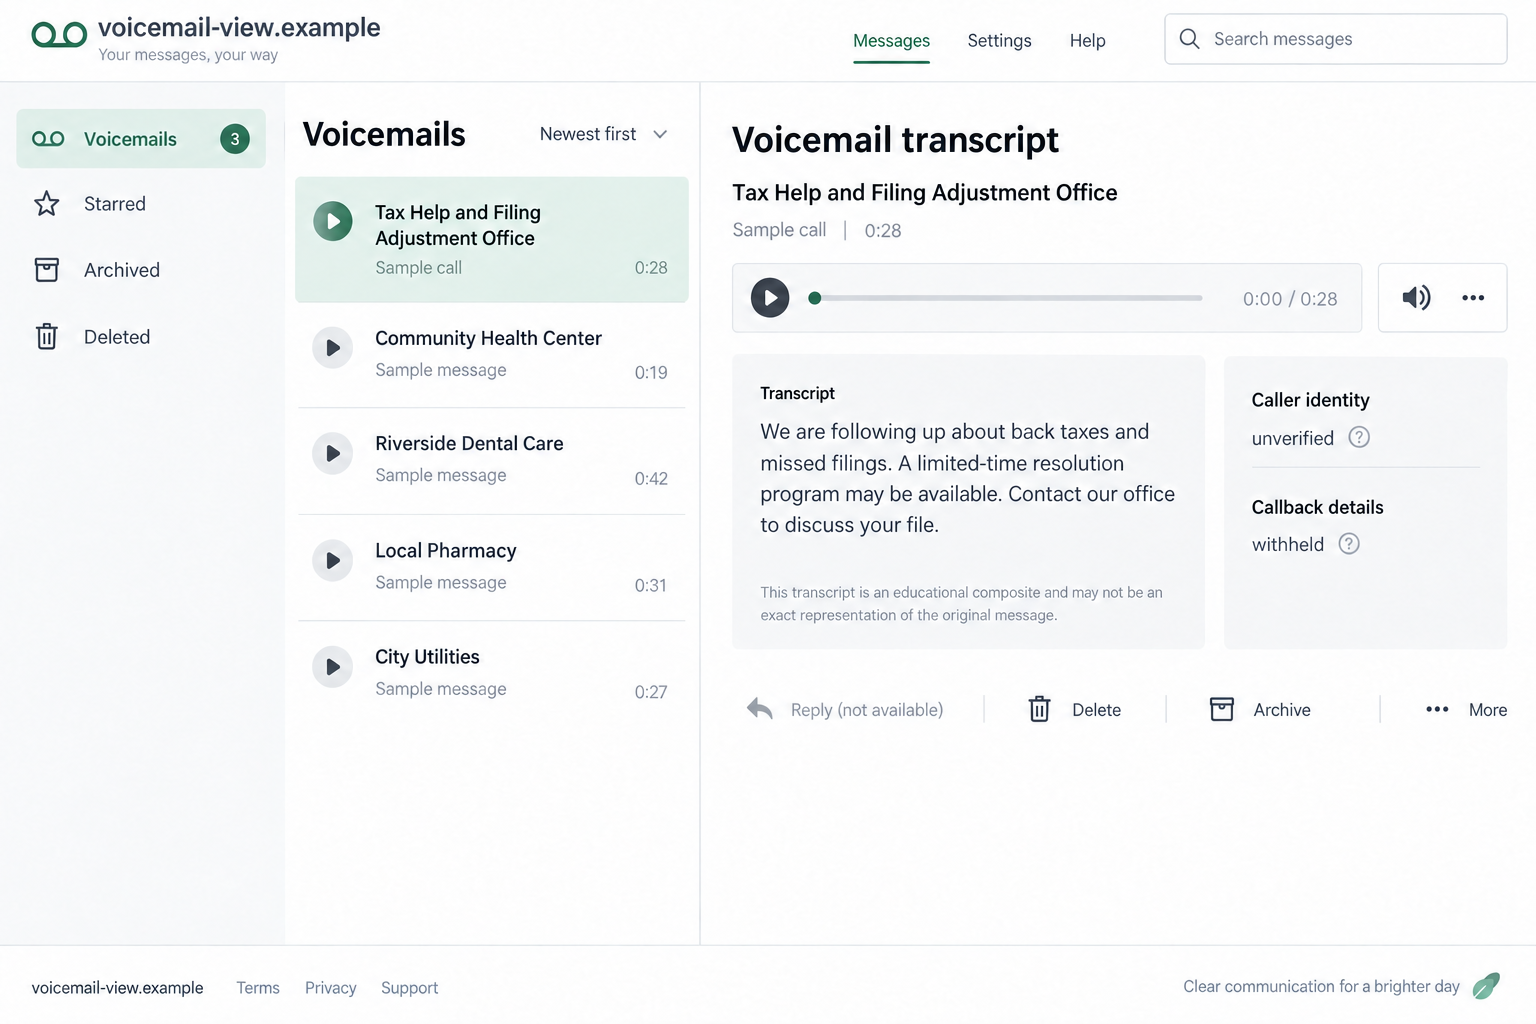
The message refers to back taxes, missing returns, a pending review, or a resolution opportunity. It may sound like a follow-up rather than a first approach.
That wording encourages you to assume some previous contact or existing file must be involved. You begin searching your memory before questioning the sender.
A first name and an office label can add familiarity without adding verifiable authority. Neither tells you which organization actually placed the call.
Caller ID does not settle that question. Numbers can be spoofed, and a callback number in a recording should not be treated as an official IRS contact.
The illustration above is a composite of the pressure pattern, not a recording from a verified employee or evidence about one particular number’s owner.
Keep the original voicemail if you want to document it. You do not have to call back to understand whether the alleged tax issue exists.
Step 2: The message turns uncertainty into a deadline
The caller says the opportunity is limited, your file needs attention, or matters may worsen if you wait. That makes independent checking feel like wasted time.
Someone with an actual unpaid balance may be especially receptive. The message appears to offer a path out of a problem they already find stressful.
Someone who owes nothing can still worry about a lost notice or identity misuse. A vague claim reaches both groups without needing accurate account knowledge.
A real notice can have a deadline, so do not dismiss every date automatically. Find the actual notice and establish the deadline through official records.
The stranger’s countdown should not become your only source of information. A threat that prevents checking is a reason to stop the call.
Step 3: A callback creates a private information interview
If you respond, the next person may ask questions framed as locating your file or evaluating relief. Sensitive details can enter the conversation gradually.
There is a legitimate reason a professional needs financial facts after a verified engagement. There is no reason to supply them before identifying the recipient.
A Social Security number, tax return, or identification image contains information useful well beyond the claimed relief application.
Do not read a complete return aloud to an unexpected caller or upload it to a portal they introduce before you have checked the firm.
A legitimate identity check should occur within a process you deliberately initiated with a verified service. It should not rescue an unverified voicemail’s missing credibility.
If the speaker says they already know your balance, ask the actual tax authority about it. One apparently correct figure does not authenticate the whole conversation.
Step 4: The supposed solution becomes a fee or commitment
The pitch may turn toward a paid consultation, enrollment fee, ongoing service, or payment supposedly needed to secure relief. These are different commitments.
Ask whether money goes to the tax authority or a private company. An adviser’s invoice and a payment toward your actual tax balance are not interchangeable.
Misleading relief sellers can charge for work unsuitable for the taxpayer’s circumstances. The IRS has warned about businesses promoting offers to people who do not qualify.
For your own call, insist on an assessment and written scope before committing. A promised settlement needs to fit your circumstances, not just the sales pitch.
Do not accept a guaranteed result merely because payment is described as refundable. Find the actual refund terms and the conditions attached to the promise.
A refusal to provide written details leaves you unable to compare the charge with the work. You can decline rather than negotiate under pressure.
Step 5: The original tax issue can remain unresolved
A payment to a deceptive caller does not necessarily reach the IRS or satisfy a real filing obligation. The phone conversation can create a second problem.
The taxpayer may believe help is underway while a genuine deadline continues. That is why checking official records remains important even after stopping contact.
Do not rely on the seller’s statement that your case is approved, paused, or settled. Obtain confirmation through the proper authority or your independently verified representative.
If another fee appears to “finish” the process, pause. Compare it with the original agreement and evidence of work actually performed.
Where the caller was an impostor, stop sending money. Where a real contracted service is disputed, preserve the agreement and seek an appropriate billing or professional review.
Check the Firm Before Buying Tax Relief
Identify the private business behind the office label
Ask for the legal business name, website, service address, and identity of the professional responsible for your work. An office-sounding phrase is not a substitute.
Check those details through independent sources rather than a link supplied during the call. A polished site may repeat the sales claim without establishing professional authority.
Do not accuse a similarly named firm based on a voicemail alone. An impostor could borrow a name without the real firm’s involvement.
Find the actual assessment and deliverables
A useful engagement explains what records will be examined, which options will be considered, and what work the professional will perform.
“We will clear your taxes” is not a defined deliverable. Ask what happens if the assessment finds that a promised settlement is unsuitable.
An honest answer may involve several options or no reduced settlement. That is more useful than a guaranteed result untethered to your circumstances.
Match the payment recipient to the written agreement
Before paying, compare the merchant or account receiving money with the company named in the engagement. Ask about any unexplained difference.
Read the total fees, installment schedule, renewal terms if applicable, cancellation process, and refund conditions. Do not assume every firm uses recurring billing.
Also establish whether any quoted amount is a professional fee or an official application payment. Keep receipts for both purposes separate.
Understand what access you authorize
A verified tax representative may need a properly completed authorization. Read what access or authority it grants before signing.
Do not give your personal account password to an unexpected caller as a shortcut. Ask how the verified professional works through appropriate authorization procedures.
If you have already signed something questionable, get independent guidance about reviewing or revoking it. Deleting the voicemail does not withdraw an existing authorization.
How to Check a Real Tax Concern Without the Caller
Use your own records as the starting point
Look for the actual tax year, filed return, payment record, or notice. A general reference to “missed filings” does not identify which obligation needs attention.
Navigate to IRS.gov independently for federal matters and use the genuine state tax agency for state matters. One agency’s account does not answer every jurisdiction’s question.
If you need professional help, choose the provider yourself and verify its credentials through the relevant professional authority. Do not inherit the voicemail’s recommended contact.
Do not confuse rejection of the caller with rejection of a notice
Ignoring a deceptive voicemail can be sensible. Ignoring an independently verified tax notice because you dislike the voicemail is a different decision.
Keep genuine deadlines and correspondence organized while evaluating the contact. If the issue is unclear, ask the verified agency or professional what needs a timely response.
These steps establish the real problem before you buy help. They also make it easier to explain what was misrepresented if you already paid.
What to Do if You Have Fallen Victim to This Scam
-
Stop using the caller’s process. End conversations, decline new fees, and avoid portals or software introduced by the unverified contact.
Save the voicemail, callback details, messages, payment instructions, and agreement if one exists. Record what you understood the service or payment to be.
-
Contact the relevant payment provider quickly. Explain the misleading claim and distinguish a professional service charge from a supposed tax payment.
Ask about stopping pending activity, disputing a card charge, or recalling a transfer. Supply receipts and written terms where available.
Do not promise yourself a refund before the provider assesses the facts. Do not send another payment to the caller to unlock recovery.
-
Secure any accounts or information you exposed. Replace shared credentials through the genuine service and check relevant recovery or authorization settings.
For Social Security numbers or substantial identity disclosure, use IdentityTheft.gov to organize the appropriate protections.
The IRS victim guidance explains tax-related identity steps, including options involving an Identity Protection PIN. Follow the route matching your actual exposure.
-
Check your real tax position independently. Confirm whether a return, balance, notice, or deadline needs action through the actual tax authority.
Do not assume the caller filed an application or settled a debt. Ask a verified professional to review documents if you purchased representation.
If someone submitted incorrect information, get advice about the proper correction. Do not silently repeat the same claim on a later return.
-
Review agreements and authorizations you signed. Request a clear account of work performed, charges, cancellation terms, and any submissions made in your name.
Where the company is identifiable, keep cancellation or dispute correspondence in writing. Seek independent help for unresolved contractual or professional issues.
Do not send additional identity documents merely because the same caller says they are needed to close your file.
-
Address device exposure only if it happened. Disconnect an active remote-control session and stop using the affected device for sensitive accounts.
Malwarebytes can help inspect a suspicious download or installation. AdGuard may reduce exposure to known malicious pages and advertising.
Neither tool resolves a tax balance or removes copied identity information. A voicemail alone is not proof your device contains malware.
-
Report the conduct through the appropriate route. TIGTA’s complaint page distinguishes IRS or Treasury impersonation from other tax-related issues.
Describe the authority claimed, requests made, and amounts paid. An ordinary private-service dispute should not be mislabeled as a verified government employee’s misconduct.
Keep report references and watch for fresh callers offering guaranteed compensation. Check genuine follow-up independently rather than trusting the next official-sounding voice.
Frequently Asked Questions
Is Tax Help and Filing Adjustment Office an IRS department?
The caller’s label does not establish an IRS department or employee. Verify any claimed federal tax matter through IRS.gov and your own records.
Does the IRS ever make phone calls?
Yes. It describes legitimate calls and some automated messages, while normally using mail for initial contact. Independent verification is more useful than a blanket rule.
Does the voicemail prove I owe back taxes?
No. A generic message is not an account record. Check the relevant tax year, notice, and balance through the actual authority.
Is every upfront tax professional fee a scam?
No. Legitimate services can have fees, and official processes may have payments. The recipient, scope, eligibility assessment, and written terms need to make sense.
Can a caller guarantee an offer in compromise?
A private promise is not an IRS approval. Eligibility and acceptance depend on the actual financial circumstances and program requirements.
What if I paid and still have a real tax deadline?
Contact the payment provider about the charge and separately address the verified tax issue. A scam report does not automatically pause your filing or payment obligations.
The Bottom Line
Do not pay or share tax records because an official-sounding voicemail mentions a closing relief window. Establish the real tax issue and the caller’s identity separately.
If you already paid or disclosed information, contact the payment provider, secure the relevant records, and check genuine deadlines. The tax relief pitch is not proof of relief.








