

An unclaimed life insurance letter arrives from a lawyer who says a wealthy client with your last name died without an heir.
A policy worth millions is waiting, and the firm proposes a confidential claim. The envelope, legal language, and overseas postmark make the opportunity feel oddly concrete.
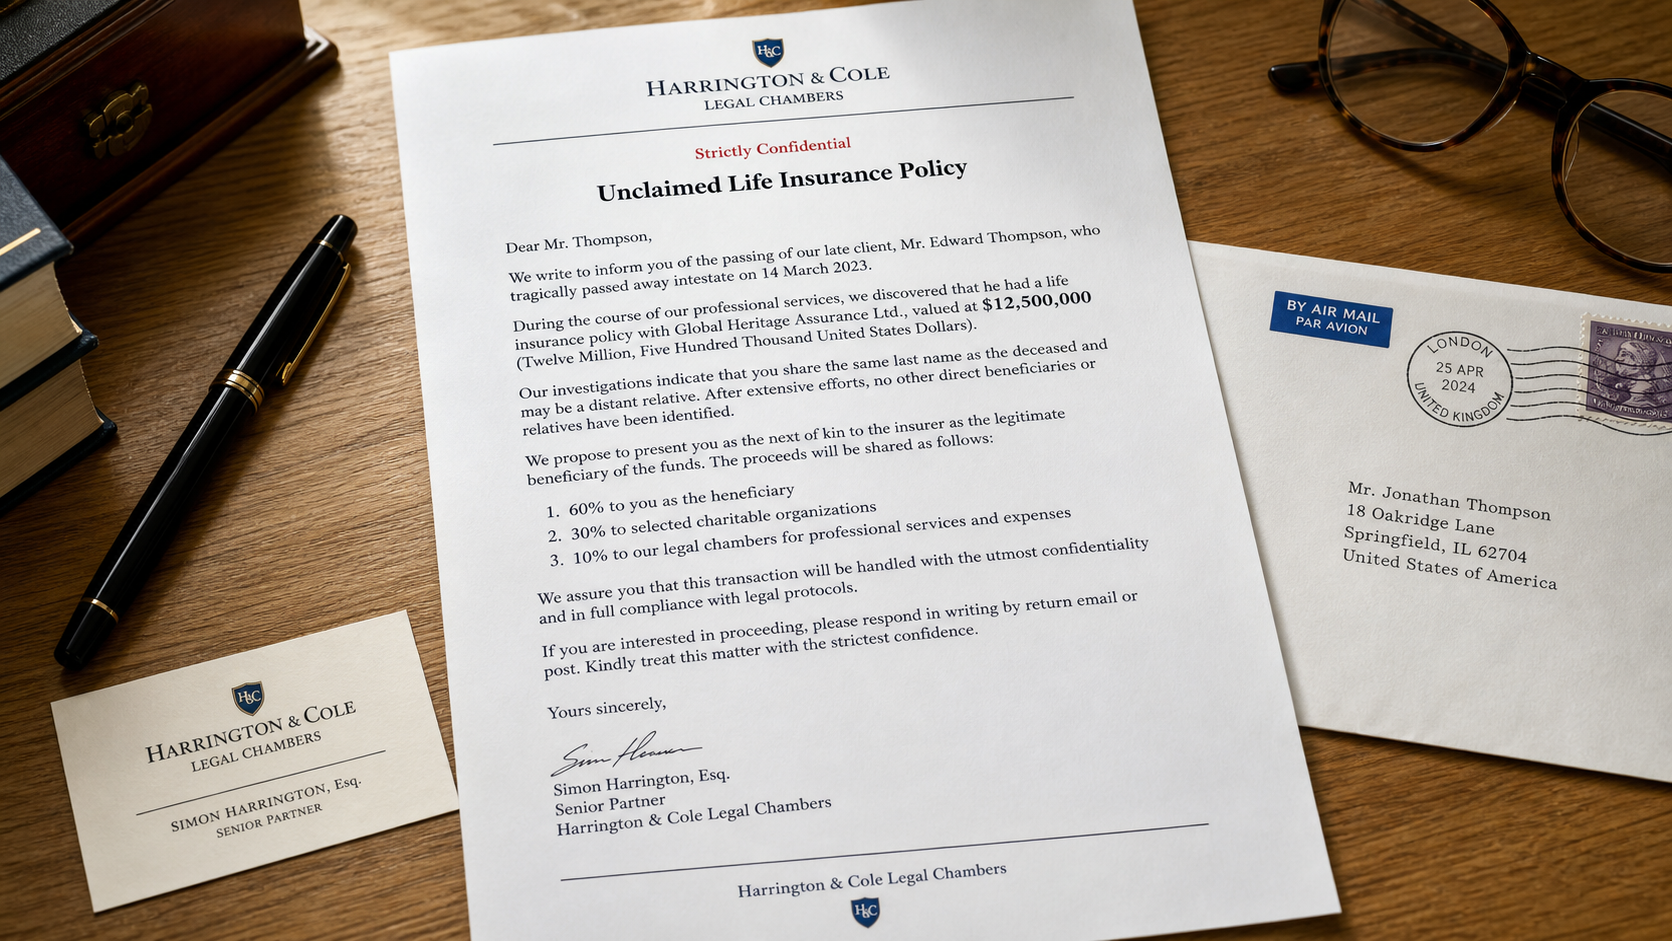
The FTC warned in July 2026 that these letters were circulating again. The supposed lawyer claims to have found the recipient because they share a surname with the deceased policyholder.
The proposal often divides the fictional proceeds among the recipient, charities, and the law firm. That arrangement gives the fraud an ethical cover while explaining why a stranger is being invited into the claim.
There is no lawyer, client, policy, or inheritance. Once the recipient responds, the sender requests identity and banking records, then invents taxes, legal clearance, transfer, or insurance fees.
Overview
Replying seems harmless, but the letter is only the first page of a much longer extraction scheme.
The shared surname is used to manufacture a family connection
The letter does not need a real genealogy. It claims the firm exhausted its search for heirs and can present the recipient as next of kin because the last name matches.
A common surname and a personalized postal address are enough to create curiosity. Neither establishes a relationship to a deceased person or a valid policy.
Legal detail makes an impossible proposal sound procedural
Letterhead, case references, policy values, signatures, confidentiality language, and charity allocations make the arrangement feel reviewed by professionals.
The basic proposal remains fraudulent: a stranger cannot lawfully become beneficiary of someone else's policy because a supposed lawyer offers to manufacture a connection.
The imaginary fortune unlocks real identity and fee demands
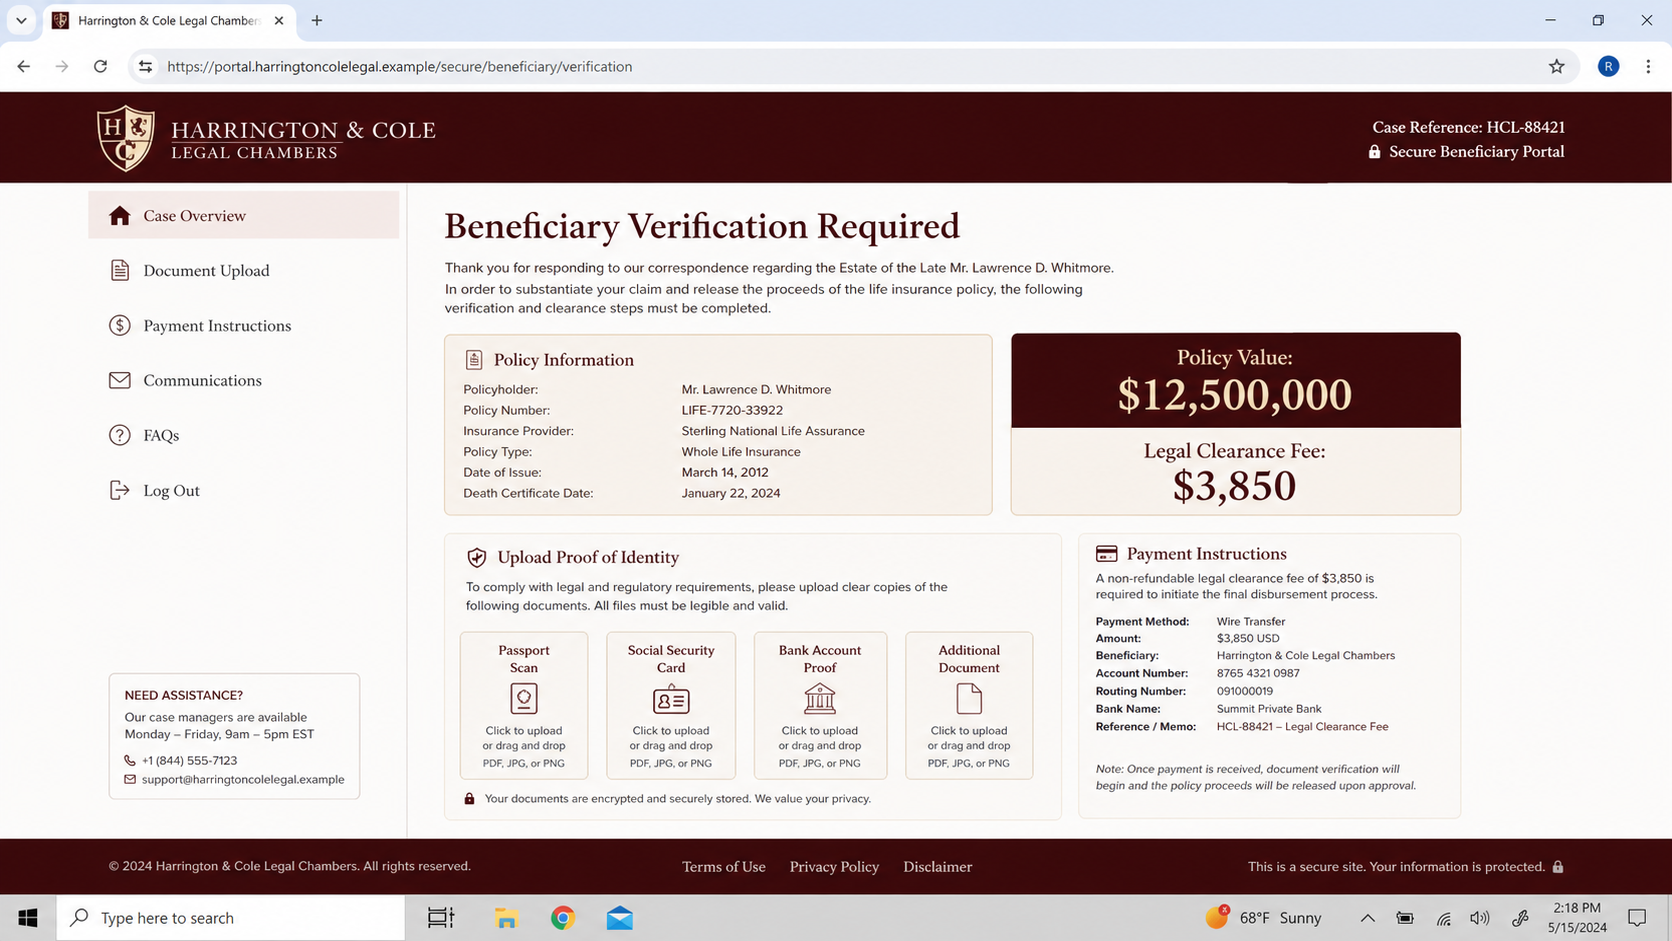
The first reply confirms an interested target. Follow-up forms request a passport, Social Security number, bank proof, signature, and address under the label beneficiary verification.
A clearance or transfer fee follows. Once paid, more obstacles appear because the policy exists only as leverage for repeated payments.
- A law firm claims a deceased client shared your surname.
- No genuine family relationship or policy evidence is provided.
- The proceeds are supposedly split with charities and the firm.
- Secrecy and a rapid reply are presented as legal requirements.
- Identity documents and bank information are requested.
- Taxes or clearance fees grow while the payout never arrives.
- A fake insurer or banker joins to confirm the same story.
- Policy certificates are supplied through channels controlled by the sender.
- Payment instructions lead to unrelated people, accounts, or crypto wallets.
- A recovery agent later offers to retrieve the lost fees.
- The supposed lawyer discourages verification with relatives or local counsel.
- The insurer cannot be confirmed through independent regulator or company records.
- A new certificate appears whenever the victim questions the previous demand.
- Payment recipients change across countries while the case number remains unchanged.
- The promised release date moves again immediately after every completed transfer.
Why a Printed Letter Can Feel Safer Than an Email
Physical mail has weight and cost, so people often treat it as more deliberate than spam. Modern printing and bulk mailing make professional-looking fraud inexpensive.
The recipient's name and address may come from public records, marketing databases, directories, property records, or breaches. Personal delivery proves only that the sender obtained an address.
An international firm can be harder to check, and unfamiliar legal terminology makes delays or special fees sound plausible. The distance also discourages an in-person visit.
The charity split solves a moral problem created by the pitch. The recipient is told that accepting the arrangement helps good causes, even though the process requires misrepresenting heirship.
Real life insurance benefits begin with a known deceased person, insurer, policy, named beneficiary, estate representative, or official unclaimed-property process. They do not begin with a stranger proposing secrecy and a fabricated relationship.
What the FTC Says About the Fake Lawyer Letter
The FTC said consumers reported letters from supposed law firms about unclaimed life insurance worth millions. The deceased client allegedly shares the recipient's last name.
The letter says no heir was found and proposes dividing the proceeds with charities and the firm. The FTC's conclusion is direct: the sender is not a lawyer and the policy does not exist.
Responding exposes the recipient to requests for Social Security numbers, bank details, money, or all three. A reply also confirms that the address and story reached a responsive target.
The agency advises recipients not to respond and never to send money or personal information to a stranger promising a large reward.
The same story has circulated across communities and countries for years. Names, amounts, firms, and insurers rotate, while the inheritance mechanism remains nearly identical.
How the Unclaimed Life Insurance Letter Scam Works
Step 1: A formal letter introduces a deceased namesake
The sender claims to represent an estate or life insurance matter involving someone with the recipient's surname and sometimes nationality.
A large policy value makes even a remote possibility feel worth exploring.
Step 2: The fake lawyer explains why no real heir is needed
The letter says extensive searches failed and suggests presenting the recipient as next of kin. The proceeds will supposedly be divided according to a prearranged share.
Confidentiality is emphasized because outside advice would expose the impossible legal premise.
Step 3: A reply confirms an interested target
The first requested action may be only an email or signed acknowledgment. That low-friction step feels safer than paying money.
It gives the criminal a live email, confirms interest, and opens a private channel for increasingly specific requests.
Step 4: A beneficiary file collects identity documents
The firm requests a passport, license, Social Security number, signature, bank proof, address, and family information for supposed compliance.
Those records can support identity theft, account fraud, forged documents, and future impersonation schemes even if no fee is paid.
Step 5: An advance fee blocks release of the fortune
A tax, legal clearance, anti-money-laundering certificate, insurance bond, transfer charge, or court filing suddenly becomes necessary.
The payment is small compared with the promised millions, which makes the victim feel unreasonable for refusing.
Step 6: Additional officials confirm the same fiction
A fake insurer, banker, government officer, or courier may join the conversation. Each role uses separate letterhead while remaining under the criminals' control.
These confirmations are circular. None comes from a channel the victim found independently.
Step 7: New fees continue until contact ends
Every payment reveals another obstacle. Currency conversion, inheritance tax, storage, notarization, and release fees may follow.
When the victim stops, the operation disappears or returns as an investigator offering to recover the fees for another payment.
Company, Address, and Fulfillment Checks
The law-firm letterhead does not prove a licensed lawyer
Search the lawyer and firm through the relevant bar or law-society directory. Use contact information from that directory, not from the letter.
Scammers may copy a real lawyer's name while changing the email and phone number, so a matching name alone is not enough.
The office address may be copied, virtual, or unrelated
Check whether the suite belongs to the claimed firm and whether official registry records match. A prestigious building can be used on letterhead by someone who has never occupied it.
An overseas postmark does not verify the return address or sender.
Every support channel may lead to the same criminal group
The lawyer, insurer, banker, and claims officer can use different accounts but share one script. Do not treat their agreement as independent confirmation.
Contact the insurer and regulator through independently found public channels and ask whether the policy, firm, and case exist.
A genuine policy must have a traceable insurer and beneficiary process
A real claim identifies the insured person, policy issuer, beneficiary basis, estate authority, and lawful documentation. It does not ask a stranger to invent kinship.
Fees should never be wired to personal accounts, crypto wallets, or unrelated companies. The money trail must match a verifiable legal proceeding.
How to Check for Real Unclaimed Benefits Safely
Begin with the person, not the promise. If you do not know the deceased and cannot establish a genuine relationship, do not submit documents to create one.
Contact a claimed insurer using its official public number. Do not rely on a logo, policy certificate, website, or representative introduced by the letter writer.
Search official unclaimed-property programs in the relevant state or country. Legitimate programs allow people to check without paying a secret intermediary upfront.
Verify the lawyer through the licensing authority and call the registered office. Describe the correspondence and ask whether the lawyer sent it.
Show the letter to a trusted attorney, family member, postal inspector, or law-enforcement contact. A confidentiality demand from an unsolicited stranger has no power to prevent verification.
Search the supposed deceased person's name, estate, and probate jurisdiction without using links from the sender. A real estate worth millions normally leaves records beyond one private letter.
Compare the firm's email domain with the licensing-directory address. A copied lawyer name paired with a free mailbox or newly created lookalike domain is not an official contact.
Call the insurer's fraud department and provide only the claimed policy number at first. Do not send identity documents until the insurer confirms the policy and lawful reason for contacting you.
Ask an independent attorney to explain the beneficiary proposal. Any plan that requires pretending to be related to the deceased is not a legitimate shortcut through inheritance law.
Treat confidentiality as a warning when it prevents verification. A real professional can protect sensitive facts while still allowing the recipient to confirm licensing, insurer identity, and legal authority.
Do not pay taxes or legal fees to a personal account. Legitimate obligations should be documented, attributable to an accountable entity, and reviewed independently before funds move.
Preserve the envelope, postmark, letter, email headers, attachments, and payment instructions. Those details can help postal inspectors, banks, regulators, and law enforcement connect related complaints.
Warning Signs to Watch For
- A stranger says a deceased namesake left millions.
- The recipient is invited to pose as next of kin.
- Charities are used to make the arrangement seem ethical.
- The matter must remain strictly confidential.
- The lawyer cannot be reached through a licensing directory.
- Identity documents are requested before verifiable policy proof.
- A clearance or transfer fee must be paid upfront.
- Payments go to personal, crypto, or unrelated accounts.
The problem is not a missing stamp or unusual grammar. The entire proposal depends on claiming money through a relationship the sender knows is not real.
What to Do if You Have Fallen Victim to This Scam
- Stop replying and do not pay another fee. Preserve the letter and messages, then end contact. A supposed final charge will not release a policy that never existed.
- Contact the bank or transfer service immediately. Report advance-fee and inheritance fraud. Ask whether a wire, card charge, payment-app transfer, or crypto purchase can be stopped or recalled.
- Protect identity documents already sent. Freeze credit, review reports, replace compromised documents when advised, and create an IdentityTheft.gov recovery plan.
- Secure email and financial accounts. Change unique passwords, enable multifactor authentication, sign out unknown sessions, and inspect recovery details and forwarding rules.
- Verify any real firm or insurer that was impersonated. Use licensing and official corporate directories. Warn the genuine organization that its identity may be appearing in fraudulent letters.
- Scan devices if files or remote tools were used. Delete suspicious downloads only after preserving evidence, remove unknown software, and run a full Malwarebytes scan.
- Block repeat malicious pages and ads. AdGuard can reduce exposure to known scam domains and malicious advertising while you secure accounts, but it cannot recover a payment.
- Report the correspondence. Send details to ReportFraud.ftc.gov and appropriate postal, police, or national fraud authorities. Include envelopes, headers, payment instructions, and account destinations.
- Expect a recovery scam next. Do not pay a private investigator, hacker, or lawyer who guarantees the return of inheritance fees. Recovery criminals often reuse the original victim list.
Frequently Asked Questions
Can I inherit because I share the deceased person's surname?
No. A surname alone does not create beneficiary rights or kinship. The proposal to manufacture that relationship is part of the scam.
Why does the letter mention charities?
The charity split makes the arrangement feel ethical and explains the firm's share. It does not prove any charity or policy is involved.
Can a real lawyer ask me to keep an estate matter confidential?
Confidentiality can exist in legal work, but an unsolicited demand must never prevent independent verification of the lawyer, insurer, deceased person, and claim.
Is a printed international letter harder to fake?
No. Professional printing, signatures, stamps, and envelopes are inexpensive. Authenticate the sender through official records.
What if I replied but sent no documents?
Stop contact and expect more targeted messages. Secure the email account and do not open follow-up files or links.
Where can I search for real unclaimed property?
Use official state or national unclaimed-property resources reached independently. Do not pay a stranger who contacted you first.
The Bottom Line
The unclaimed life insurance letter scam turns a shared surname into a fictional fortune. Formal paper, legal vocabulary, and a charitable split cannot repair the impossible beneficiary story.
Do not reply, provide documents, or pay a clearance fee. Verify any lawyer and insurer through licensing and official public channels that you locate yourself.
If you already engaged, protect money and identity records immediately and prepare for follow-up recovery offers. The fastest way out is to stop treating the sender as the source of verification.

Join the discussion
0 commentsShare your experience or ask a question about this article.
Discussion
Start the conversation
Have a question or something useful to share? Add the first comment.