

Your bank catches an unfamiliar card charge, and you deal with it. A little later, another caller says the problem has spread to your other accounts.
The bank fraud follow-up scam can interrupt the relief you feel after resolving a real alert. The second conversation deserves a fresh check of its own.
Overview
A real earlier incident does not authenticate the next caller
This is a bank impersonation scam. An unexpected caller presents a new security emergency as unfinished business from a fraud alert the customer already handled.
The earlier bank alert can be genuine. The second caller uses that context to make further account instructions feel like part of the same investigation.
The bank itself is not the scam operator. Verify the new claims through its established support route before sharing information or changing how you access money.
A recent report shows where the conversation changed
A September account describes a legitimate in-app card alert and card replacement. About an hour later, another caller alleged wider account problems and pushed Apple Pay setup.
The customer says an independent call to the real bank established that the second caller’s claimed account changes and attempted transfers were false.
The timing does not prove who initiated the first charge or how the impostor learned about it. It also does not establish that the bank’s systems were breached.
The FTC’s fraud-call warning confirms the broader deception: criminals claim your funds need protecting, then request transfers or security codes.
Treat the new request as a separate transaction
Do not carry trust from the first verified interaction into a call you did not initiate. Check the requested action, not just the background story.
- The caller refers to a recent fraud alert you recognize.
- They expand the issue from one card to several accounts.
- They ask for balances, approvals or an unfamiliar access setup.
- They discourage you from contacting the bank independently.
- They use a matching caller-ID number as their main proof.
A bank may genuinely contact customers about fraud. The safe response is to reconnect through a known bank channel and verify the specific new claims.
Why the Second Call Can Feel More Routine Than the First
After a fraud alert, you are already thinking about account security. An unfamiliar caller does not need to create that concern from nothing.
You have recently discussed a charge, perhaps canceled a card and planned around its replacement. Another security question can feel like a small extension of that work.
The caller may describe an apparent explanation for the interruption: the first agent dealt with the card, while this agent handles a broader problem.
That division sounds plausible because real institutions do have different teams. The existence of those teams does not prove the stranger belongs to one.
The conversation also builds on your own information. If you describe what happened earlier, the person can incorporate those details into their next explanation.
It becomes difficult to remember who supplied each fact. A reassuring detail may have come from you, rather than from a bank record the caller accessed.
Keep the verification simple. End the incoming call and contact the bank using a number or app you had before this person reached you.
You can say that you want to continue the investigation through an independently verified channel. You do not need to accuse the caller before leaving.
How the Bank Fraud Follow-Up Scam Works
Step 1: An earlier real alert makes security contact expected
The customer first handles a genuine card problem through the bank’s actual app or staff. The issue may end with a blocked charge and replacement card.
That is the context described in the recent report. It does not mean every follow-up scam begins with a verified card incident.
Nor does it establish that the second caller caused the original problem. There may be a connection, but the available account does not independently prove one.
The practical point is narrower: a person who has just handled fraud may reasonably expect more communication, which the impostor can exploit.
Step 2: The impostor claims to continue the bank’s investigation
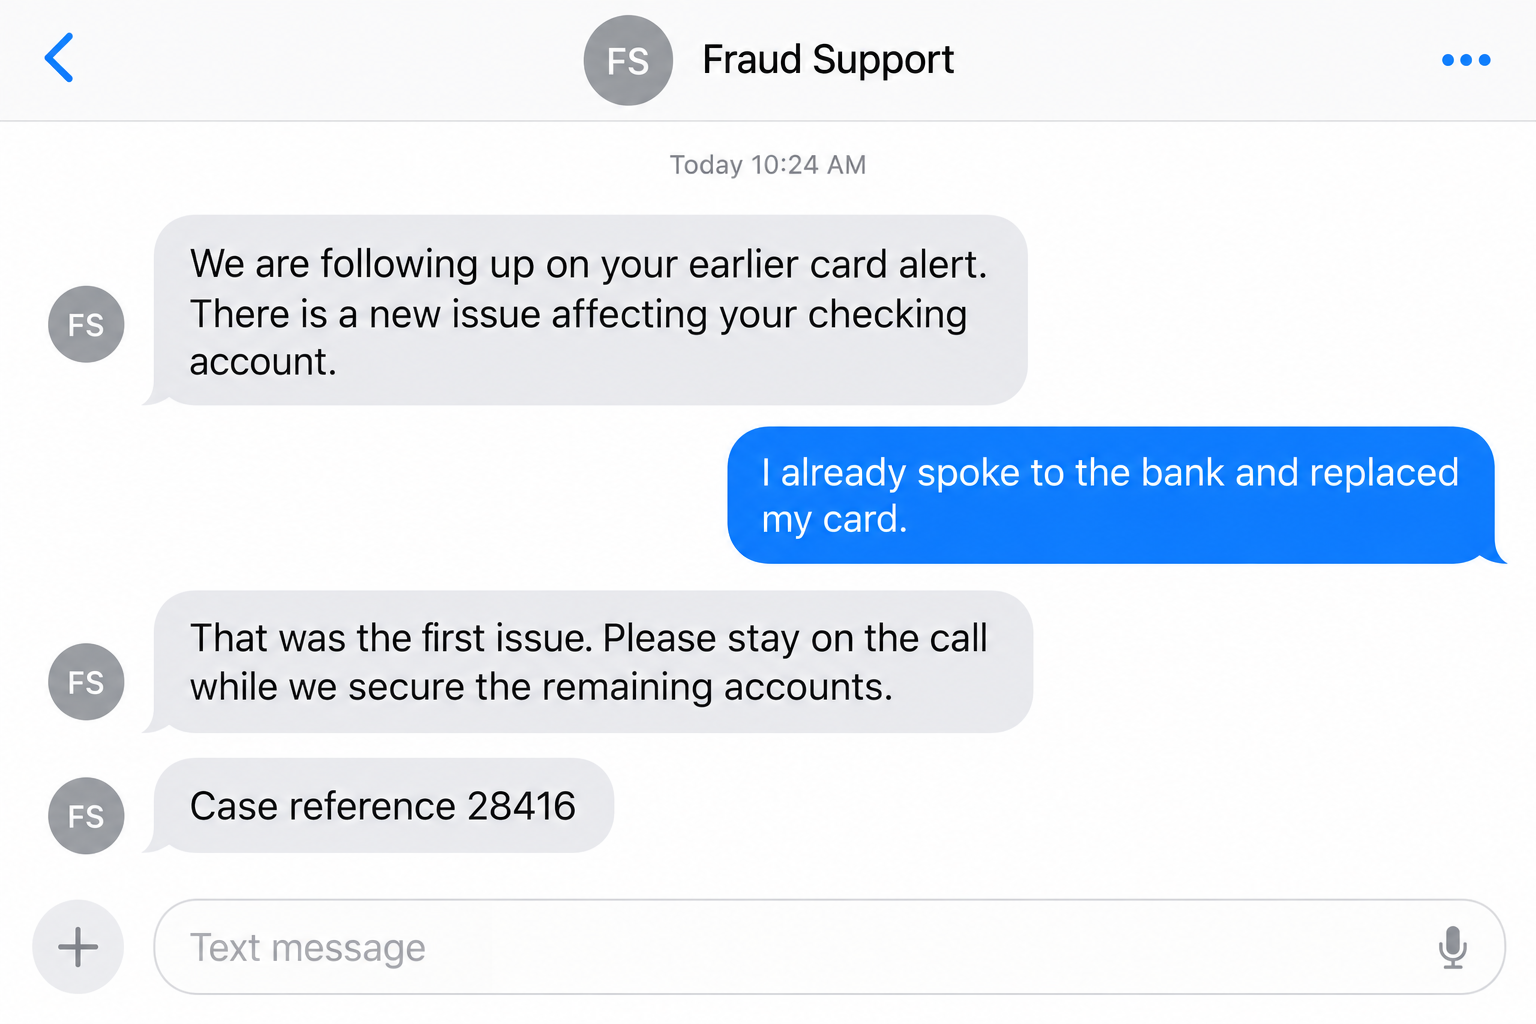
The new caller identifies themselves as fraud support and refers to the earlier problem. Their explanation turns an unexpected call into an apparent continuation.
They may know your name or the institution you use. Neither is a secret that proves they can see your bank’s internal records.
A confident manner can feel reassuring too. Experienced impostors can explain ordinary banking concepts and answer objections without reading an obvious script.
Do not judge identity from fluency, accent or friendliness. A direct connection through your bank’s own support channel is a better test.
Step 3: One card problem becomes a wider account emergency
The story grows. The person alleges another transaction, an unfamiliar device, an added account holder or a transfer you supposedly need to stop.
In the reported encounter, the caller expanded the concern to several accounts. The real bank later told the customer those alleged changes had not occurred.
Several alarming claims can leave you concentrating on denial: no, that was not me; no, I did not authorize that. Verification gets pushed aside.
Ask the bank you contact independently to check each claimed event. Do not assume that accepting one genuine alert means all subsequent claims are true.
Step 4: The proposed fix changes how you access money
The caller now supplies a task that appears to solve the wider problem. This can involve a transfer, an authorization code or a payment-related setup.
The recent customer describes pressure to set up Apple Pay while accounts were supposedly replaced. They stopped before carrying out the proposed arrangement.
Apple Pay is a legitimate service. Its name does not authenticate the person asking you to use it, and the report does not establish a completed wallet theft.
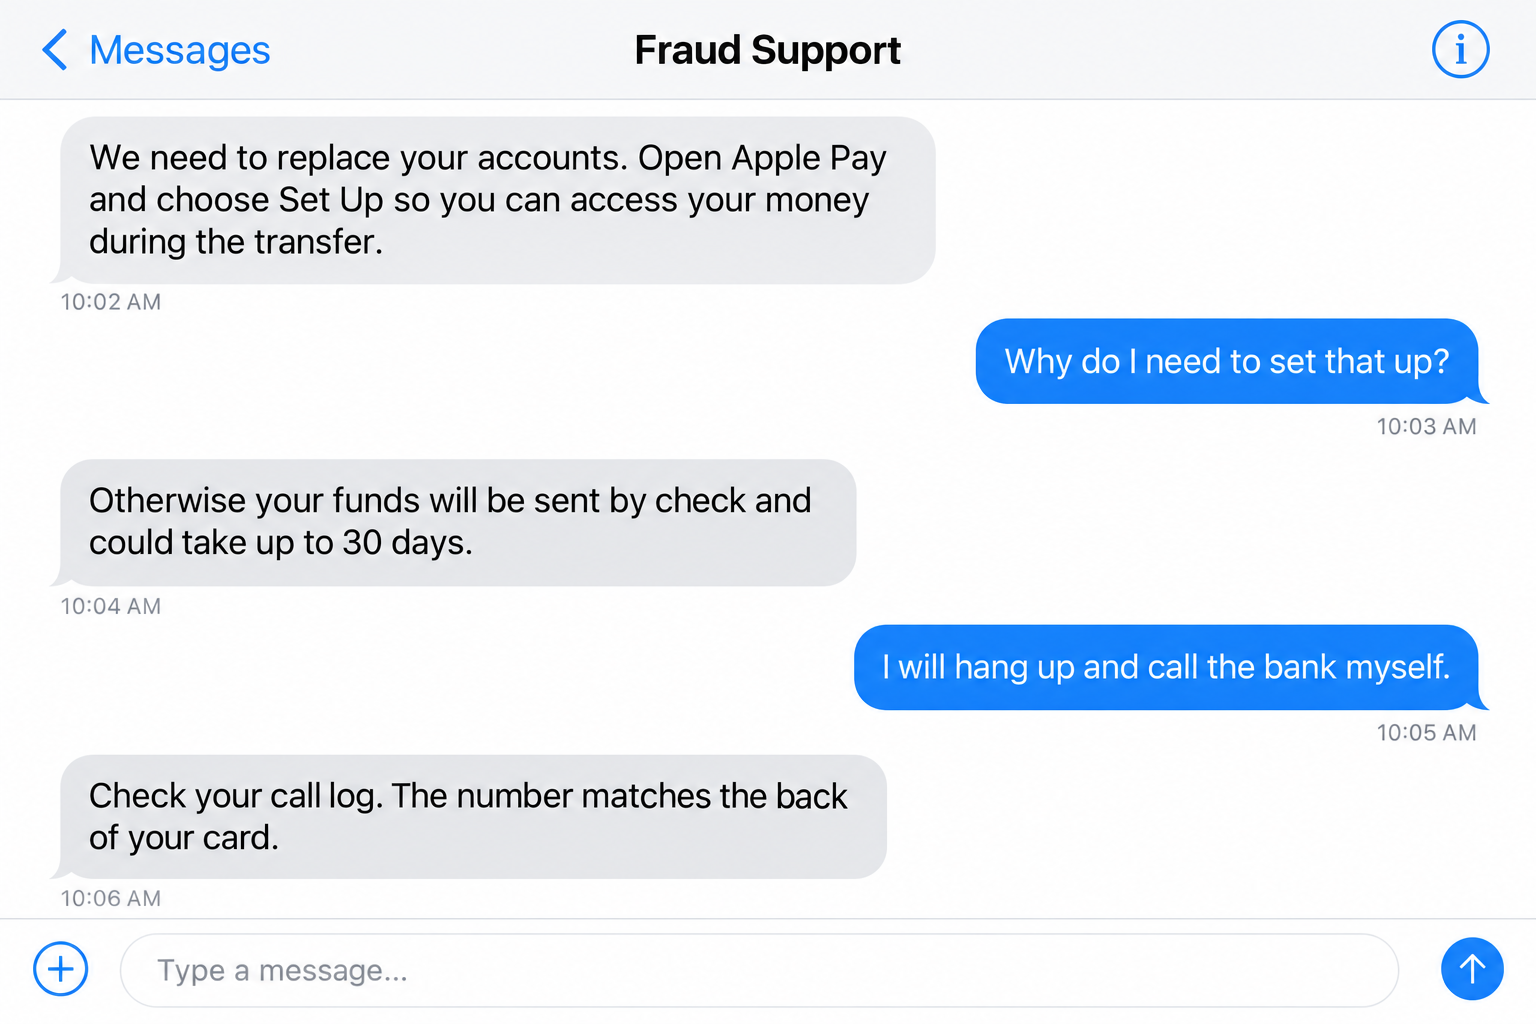
Our message-style images are fictional reconstructions of the caller’s claims. The underlying account describes phone conversations, not these exact text exchanges.
Step 5: A familiar number is offered as a substitute for verification
When questioned, the impostor can point to your call log. A displayed number matching the one on your card feels like a straightforward identity check.
The FTC explains caller-ID spoofing: scammers can make an incoming call display a trusted name or number. The display is not a verified bank connection.
Allowing the same person to hang up and call again repeats the incoming route. It does not give you an independent source of confirmation.
Choose the number yourself and place the call. Do not let the stranger replace that action with a supervisor, another inbound call or a screenshot.
Step 6: Pressure tries to make a pause feel financially dangerous
The caller can threaten inconvenience rather than arrest: locked accounts, delayed access or a long wait for money. That makes the unfamiliar task seem necessary.
The recent report describes a warning about waiting for a mailed check. The customer resisted that pressure and initiated their own call to the bank.
Any genuine restriction can be discussed through the bank’s verified channel. A threat that depends on staying with this particular caller deserves careful scrutiny.
The objective is to move your decision away from verification and toward compliance. Interrupt that transition before an apparent repair becomes a real authorization.
A Safe Callback Means You Place the Call
Use the bank’s official app, your card or an established statement to locate support. Choose information you already trust rather than contact details from the conversation.
Once the incoming call has ended, start a fresh connection. Explain that somebody claimed to be following up on the earlier card incident.
Ask whether the bank attempted that contact and whether its records show the specific events. Give the claims separately, rather than just asking if fraud is possible.
For example, an added account holder and a pending wire are different questions. The bank should understand which changes the caller said had happened.
Do not take a case number as conclusive proof. A real reference may be misused, and a fabricated one can sound perfectly ordinary.
If the first staff member cannot check the relevant issue, ask for the appropriate department through the connection you established. You control how that transfer begins.
A person on a landline who doubts the old call has disconnected can use another trusted phone. The goal is a connection independent of the original caller.
Keep the distinction clear: matching an incoming number is observation; contacting the genuine institution yourself is verification.
Read the Requested Action Before Looking at the Caller ID
A security conversation can include ordinary account checks. It should not become permission for an unknown caller to direct your money or capture a sign-in approval.
If a code arrives, read its purpose privately. It may relate to signing in, enrolling a service or authorizing something entirely different from the caller’s explanation.
Do not read a one-time security code back merely because the person says it cancels a transaction. Ask the bank through its known channel what the code authorizes.
Balance questions also deserve caution. An impostor can use the answer to size a later demand or tell a more convincing story about your available funds.
If you are told to transfer money to protect it, stop. Verification should happen before any proposed financial action, even when the earlier fraud was real.
If you are asked to set up a wallet or link an account, establish who controls the resulting access. A familiar application’s name does not answer that question.
Never hide the caller’s instructions from bank staff. A stranger who tells you to describe the transaction differently is obstructing the help you need.
You are allowed to slow down. The fastest safe action may be ending an unverified call, rather than racing through the task it supplied.
Keep the Real Card Incident Separate From the New Claims
Write down what the bank actually confirmed during the first interaction. Include the affected card, replacement arrangement and any genuine reference it provided.
Then record what the second caller alleged. That creates two lists instead of one alarming story with facts and invented details mixed together.
Do not cancel a verified card replacement because an impostor subsequently called. Continue the legitimate recovery through the bank while rejecting the new instructions.
Likewise, do not ignore genuine notices out of frustration. Review them inside your account and use the bank’s approved contact route if they raise another concern.
The original merchant name or charge amount does not identify the caller. Matching details can be copied, learned during conversation or obtained through other means.
The source report’s conclusion about deliberate timing remains unverified. We can explain the trust problem without claiming a particular criminal organized both events.
Keep speculation about bank insiders or data breaches out of your initial report unless you have evidence. Precise observations give investigators more useful starting points.
The bank can review access and transaction records. Your role is to describe what you saw, heard, disclosed and authorized as accurately as possible.
What to Do if You Have Fallen Victim to This Scam
-
Disconnect from the supposed fraud agent. Do not finish a setup, transfer or verification sequence to appease them or prevent a claimed delay.
Record the displayed number and any callback information, but obtain the bank’s contact route independently before acting on the account.
-
Contact the real bank immediately. Explain that an unverified person followed up after a genuine card incident and supplied additional account instructions.
Distinguish the original card alert from the later claims. Tell the bank what the first verified agent confirmed and what the second person asked you to do.
-
List what you disclosed or approved. Include passwords, codes, account balances, personal information, wallet changes and any transfer made during the conversation.
If a code was involved, describe the purpose shown in its message. You do not need to give the secret to anyone outside the verified provider’s process.
-
Ask about stopping pending transactions and investigating completed ones. Give the exact payment route, amount, recipient, date and whether you authorized the action under deception.
Recovery and dispute options depend on those details. Do not accept a stranger’s promise that everything is refundable or that another payment will reverse it.
-
Review account access through the bank’s guidance. Replace exposed credentials, check authorized devices and inspect any new payment or contact arrangements.
If wallet setup occurred, tell the bank exactly what was added or approved. Do not assume removing something visible on your phone settles every related authorization.
-
Preserve genuine bank notices and the scam contact records separately. Save relevant messages, call times and any written instructions you received.
Note which allegations the bank later disproved. That helps distinguish attempted fraud from transactions or account changes that actually happened.
-
Escalate identity exposure when relevant. If documents or sensitive identifiers were supplied, ask the appropriate institution about protective monitoring or identity-theft reporting.
Simply answering a call does not prove identity theft. Match your response to the information or permissions that actually left your control.
-
Report the impersonation through ReportFraud.ftc.gov for a U.S. incident, and contact local law enforcement if money was stolen.
Tell someone you trust about the event. Decline follow-up recovery offers that depend on more transfers, secrecy or a caller’s claim to know your case.
If You Hung Up Before Making Any Changes
Verify the account and note the attempted contact. You do not need to assume all your funds disappeared because the caller described a frightening set of problems.
The recent customer ended the conversation before accepting the wallet instructions. Their independent bank call was the turning point in separating false claims from the earlier genuine issue.
Follow the bank’s guidance about the information you discussed. Giving an account balance is different from supplying a password, code or payment authorization.
If you are unsure what a prompt did, say so. The bank can help identify the action from its records rather than relying entirely on your memory.
Do not call back to see whether the person admits the scam. You already have a useful reporting route and do not need another conversation.
Continue checking genuine notifications through the bank’s app or known contact channel. A scam attempt should change how you verify contact, not stop legitimate account monitoring.
Frequently Asked Questions
Can the first fraud alert be genuine while the second call is fake?
Yes. The verified earlier event does not authenticate a separate caller. Check every new request through a bank contact route you choose yourself.
Does this prove scammers caused the original card charge?
No. Timing alone does not establish that connection. The reported second call was identified as false, but the first transaction’s operator remains unverified.
What if the caller’s number matches my debit card?
Caller ID can be spoofed. End the incoming call and dial the bank’s established number yourself instead of accepting another inbound call.
Is Apple Pay itself the scam?
No. It is a legitimate service. The danger is following an impostor’s unverified financial or access instructions merely because they mention a familiar application.
Will a real bank ever call me about fraud?
It may. You can still end an unexpected call and reconnect independently. That lets the genuine bank verify the issue without relying on caller ID.
Am I safe if I never transferred money?
That avoids one exposure, but review any credentials, codes or permissions shared. Tell the bank what occurred and let it assess the relevant account changes.
The Bottom Line
The bank fraud follow-up scam borrows credibility from a problem you already handled. The second caller’s identity and instructions still require their own verification.
End the incoming conversation and contact your bank independently. A real earlier alert is no reason to surrender control of the next financial decision.








