


A structural warranty can decide whether a lender funds a new house, so we looked at what CMLC Ltd actually sells.
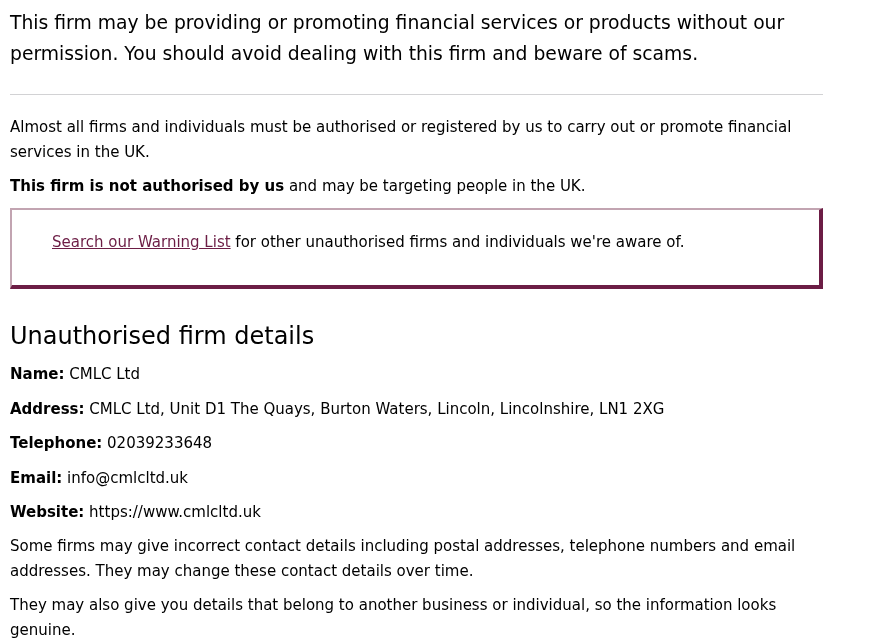
The Financial Conduct Authority listed the firm as unauthorised on November 2, 2026, and we followed that warning through company records, lender guidance and the firm’s own cover handbook.
Overview
What CMLC Ltd offers
The site at cmlcltd.uk sells a 10 year structural warranty for new builds, self builds, barn conversions and projects that are already under way.
It promises savings of up to 50% against other providers, acceptance by mortgage lenders and checks by RIBA and RICS surveyors, yet it shows no price anywhere.
A quote comes only through a form that asks for a site address and planning reference, and the other services listed are structural design, party wall work and legal advice.
What we found behind the offer
The FCA Register lists one firm called CMLC, marked Unauthorised, at the registered office of a real company that Companies House shows as active since 2016.
So the warning concerns an existing building company, not a copy of an authorised firm, and no page on the site names the insurer that would pay a claim.
The firm’s own handbook leaves the builder responsible for two years, then points owners to their own buildings insurer, and the site gives three different addresses.
What we could and could not verify
Here is where the evidence stands after our checks:
- Verified by us: the FCA entry and Register result, the company filings, the domain dates, the archived history, the handbook wording and the lender guidance pages.
- Not found: a named insurer, a policy number, a price, a surveyor’s name or membership number, or any lender that publicly accepts the product.
- Not verified: whether any certificate has ever paid a claim, what the FCA had in mind, and what the firm would say in reply, because we sent no message.
Our advice is to get any cover and lender acceptance confirmed in writing before you pay CMLC Ltd, and to read the response section below.
What the FCA Warning Says and Where It Points
We opened the warning on the FCA’s own site and read it in full: the entry is titled CMLC Ltd and was first published on November 2, 2026.
Its headline warns that the firm may be providing or promoting financial services or products without permission, and that you should avoid dealing with it.
The entry leaves the product unnamed, because it lists no activity at all, and it never calls the firm a clone of any authorised business.
The entry prints a Lincoln address, the telephone number 02039233648, the email info@cmlcltd.uk and the website https://www.cmlcltd.uk, and the last three match what the site itself shows.
We then searched the FCA Register for CMLC, and it returned exactly one firm, CMLC Ltd, marked Unauthorised, with the postcode LN1 2XG.
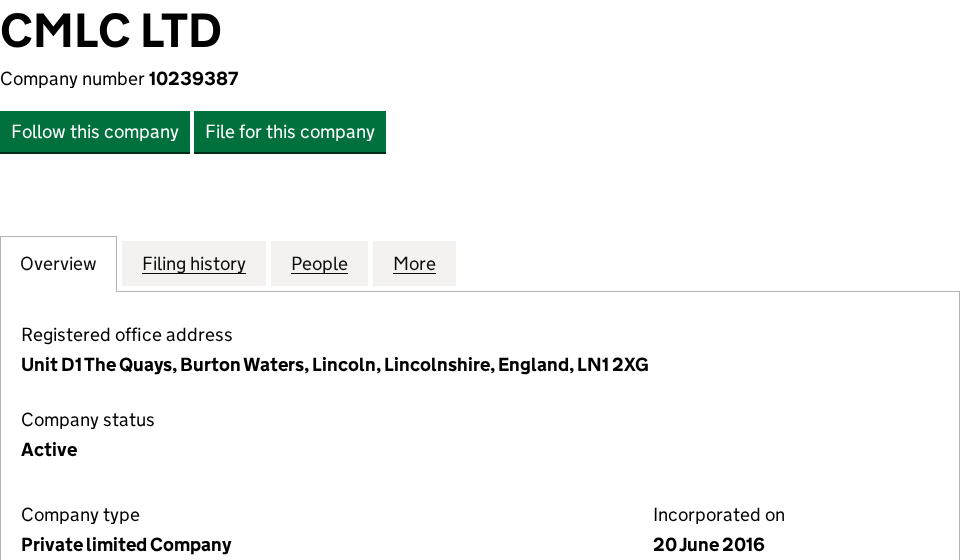
That postcode matches the registered office that Companies House shows for CMLC LTD, company number 10239387, so the warning concerns the real company and not a lookalike.
That matters because the usual clone advice does not apply here: there is no authorised CMLC on the register to compare the website against.
The warning spells out the consequence for a buyer, who would have no access to the Financial Ombudsman Service or the Financial Services Compensation Scheme if things go wrong.
A warning is not a finding that anyone broke the law, and we make no such accusation. It tells you to check before you pay.
A Certificate Sold as a Warranty
We opened the oldest archived copy of the site, dated November 1, 2020, and it described the product differently from today’s page.
That version presented a 10 year structural warranty delivered through professional consultants certificates, comparable in purpose to architects certificates.
It also stated that the firm’s professional indemnity cover reaches single unit values up to £1 million, a limit that no longer appears on the site.
Today’s home page uses the word warranty throughout and has dropped both the professional consultants wording and that limit.
The difference matters because a warranty and a professional consultant’s certificate are separate products, and lenders treat them separately.
The UK Finance page on these certificates sets out that lenders will generally lend on a new build only where a warranty scheme or a certificate covers the property.
The same page adds that a consultant who signs a certificate stays liable to first and later purchasers for 6 years and must keep professional indemnity insurance in force.
It adds that the consultant must belong to a listed professional body, for example as a fellow or associate of the Royal Institution of Chartered Surveyors.
CMLC offers 10 years, longer than the 6 years that page covers, so the final four years go beyond the standard certificate and depend on what CMLC itself promises.
We could not identify the person or body behind that promise, because the site names no surveyor, membership number or insurer that a buyer could look up.
What the Cover Handbook Actually Promises
The warranty page offers a handbook as a PDF, and we read its four pages as text, because that is where the real terms sit.
Its cover section is headed End of year 2 to 10, so the first two years are handled differently from the other eight.
During those first two years the handbook makes the builder responsible, so the owner tells the builder about defects while CMLC asks only to be told and record them.
From year 3 to year 10, the first instruction is that the owner should notify their own buildings insurer of any defect or damage.
Only then will CMLC pass the matter to its professional indemnity insurers, and the document never names those insurers, a policy number or a limit.
A £1,000 excess appears in that step, while the exclusions list at the end sets a warranty excess of £2,000 on each and every case.
So one document gives two different excess figures, and a buyer cannot tell from it which one would apply to them.
We counted 22 lettered exclusions, from a to v, including flooding, fire, storm-force weather, any reduction in a home’s value and any loss covered by another insurance policy.
Exclusion a deserves a second read: if another insurance policy covers the loss, CMLC does not pay, and the earlier steps already send the owner to their buildings insurer first.
A caveat on page 4 adds that only a CMLC registered developer’s work is covered, and cover may not apply fully or at all if someone else finishes the house.
The wording also shifts between a professional consultant certificate, an insurance certificate, a warranty excess and CMLC’s insurance liability, and never makes clear which the buyer is purchasing.
That is not a small drafting quirk, because each of those labels carries different rights, and the vagueness leaves open who exactly would pay and under what rules.
A Comparison List That Admits What Is Missing
The comparison list on the warranty page sets CMLC against NHBC or similar in 21 rows, with one question about UK coverage repeated twice.
CMLC answers No on only three of them: it asks for no security bond, covers no purchaser’s deposits and requires no financial accounts before work starts.
The list presents these as selling points, but on its own terms they also mean that nobody tests the builder’s finances before cover begins.
The missing deposit cover matters to anyone who pays a reservation to a developer, because by the list’s own answer that money sits outside the cover.
Every other row reads Yes, including that the policy transfers to new owners, that cover can start after building has begun and that surveyors are fully insured.
The home page adds that its warranties save up to 50% against other structural warranties, but no page gives a price, a fee or a sample quote.
The only route to a figure is the quote form, which asks for a name, email, telephone number, site address and planning reference.
The home page also promises no premium element, a phrase that does not tell a buyer what the fee is or what it buys.
The footer lists Terms and Conditions, Privacy Policy and Cookie Policy, but all three links point to nothing, so no document can be read before the form is sent.
Without a number the 50% saving cannot be tested, and without terms a buyer cannot tell what rights the quote leads to.
The Lender Claim We Could Not Test
The home page presents the warranty as recognised by mortgage lenders, as detailed within the UK Finance Mortgage Lenders handbook, and as accepted by high street lenders.
We followed the handbook address given in the archived 2020 page and met a login wall that tells visitors they lack permission to view the page.
The public front page of that handbook makes clear that it is voluntary for lenders and that not all of them choose to use it.
Its warranty guidance page leaves each lender to decide whether a warranty provider is acceptable, and meeting every requirement does not guarantee acceptance.
The public pages we could read do not name CMLC as an approved provider, and the site names no lender that has accepted it.
The word compliant fits badly too, because UK Finance frames its guidance as the information members typically require, not as a certification that a provider can hold.
The consequence is simple: only your own lender can confirm that a CMLC certificate will satisfy your mortgage, and it should do so in writing before you pay.
A builder who relies on the website’s wording and learns at completion that the lender refuses the certificate faces delay, a second policy and possibly a failed sale.
Three Addresses for One Company
The footer of every page we opened gives 48 Warwick Street, London W1B 5AW, next to the company registration number 10239387.
The contact page gives a different address, CMLC Ltd, NFU Building, Camelgate, Spalding, PE12 6ET, with a map that points at the Warwick Street address.
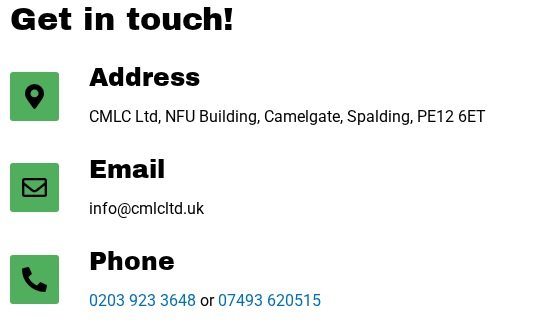
Companies House shows that the Spalding address was the registered office until June 21, 2024, when it changed to Unit D1 The Quays, Burton Waters, Lincoln.
That Lincoln address is the one the FCA printed, so the contact page still carries an office the company left more than two years ago.
The London address does not appear as a registered office in the filing entries we read, and we cannot tell what sits there.
A business may legitimately use a serviced or mailing address, so the point is not that it is false but that a buyer cannot tell which one reaches the company.
The telephone number 0203 923 3648 is a London number and the site adds a mobile number, so none of the contact numbers is tied to the Lincoln office.
Anyone who posts plans or a deposit to the contact-page address would be writing to a place that the Companies House record shows the company moved away from.
Who Runs CMLC Ltd?
The company named in the documents
The footer and the FCA entry both lead to CMLC LTD, company number 10239387, a private limited company incorporated on June 20, 2016.
Companies House lists it as active, with the nature of business given as development of building projects, SIC code 41100, which is not an insurance or warranty classification.
The officers page lists one director with no resignations, and the filing history shows accounts for the year to June 30, 2025, filed in March 2026 as total exemption full.
Earlier years were filed as micro company accounts, the smallest filing category, which suggests a very small company, though we did not read the figures inside them.
The first accounts, for the period to June 30, 2018, were filed as dormant on August 5, 2019, a month after Companies House suspended a compulsory strike-off action.
That strike-off action, which usually follows overdue filings, was discontinued on August 6, 2019, but it shows the company’s early years left little public trace.
Where the registration and address lead
The registered office in Lincoln is Unit D1 The Quays, Burton Waters, the same address the FCA printed and the same postcode the FCA Register returned.
We did not visit it or contact the company, so we draw no conclusion about what the unit is used for.
Companies House does not check the accuracy of what companies file, as its own pages remind visitors, so the record shows what the company filed and not what we verified.
Nothing in the record connects the company to insurance, and the FCA entry draws no such link, which leaves the activity behind the warning unexplained.
The domain, platform and tracking
The registry record shows cmlcltd.uk was registered on August 14, 2018 through 123-Reg, about two years after the company was incorporated and a month after its first accounting period closed.
The four name servers belong to stackdns.com and the site resolves to a shared hosting address, which tells us about the web host and nothing about who owns the business.
The first archived copy, from November 2020, was built on Wix, and by November 2021 the archive shows a rebuild on WordPress with Elementor, which the live site still uses.
The footer credits a digital agency for the site and shows a copyright year of 2021, which fits the rebuild we saw in the archive.
The page source carries one Google Analytics measurement ID, G-X9HF24K64Q, and one Meta pixel ID, 241072677888172, which we record so that others can compare them.
We did not search for other sites that carry those IDs, so we draw no conclusion about shared setups.
What we could not confirm
We could not find which insurer, if any, stands behind the certificates, because the policy document that the site mentions is not public.
We could not tell what activity the FCA had in mind, or whether CMLC has ever issued a certificate that a lender accepted.
The site names no surveyor and no RIBA or RICS membership number, so the boast that all surveyors belong to those bodies is untested.
We did not call, email or submit the quote form, so the price, the insurer and the firm’s answers to these questions remain unknown.
What to Do Before You Pay or After You Paid
-
Check the register. Search the firm’s name in the FCA Register and read any warning before you send plans, personal details or money.
-
Ask your lender first. Send the lender or its conveyancer the provider’s name and ask in writing whether that exact certificate or warranty is acceptable for your mortgage.
-
Ask for the insurer. Request the insurer’s name, the policy wording, the limit of cover, the excess and the route for making a claim before you agree to pay.
-
Check the surveyor. Ask for the name and membership number of the person signing, then look them up with RICS Find a Member or the relevant register.
-
Read the handbook twice. If a document gives two excess figures or sends you to your own buildings insurer first, ask for the contradiction to be fixed in writing.
-
Compare with other schemes. Get a quote from a provider your lender names in its own instructions and compare price, excess, exclusions and the length of cover.
-
Pay traceably. Use a card or another method with a dispute route, and keep every email, quote and PDF with its date.
-
Report it. If you already paid, tell the FCA using the contact details on its warning page and tell your lender and solicitor.
Frequently Asked Questions
Is CMLC Ltd a scam?
We found no proof of fraud, but an FCA warning, no named insurer and conflicting terms and addresses are enough reasons to hold back your money.
Is CMLC Ltd authorised by the FCA?
No. The FCA Register shows CMLC Ltd as Unauthorised, and the FCA’s warning of November 2, 2026 confirms the firm is not authorised by the regulator.
Is CMLC Ltd a clone of another firm?
We found no sign of that. The FCA’s postcode matches the registered office of the real CMLC LTD, and the register shows no authorised firm of that name.
Will a lender accept a CMLC certificate?
Only the lender can confirm it. UK Finance leaves each lender to decide, and the site names no lender that has accepted the product.
What is the difference between a warranty and a professional consultant’s certificate?
A warranty scheme backs a house with a provider’s promise, while a certificate rests on a named professional who must carry insurance and stays liable for 6 years.
Is it safe to send my planning reference through the quote form?
The form works without any privacy document, because the site’s privacy link goes nowhere, so share only what a lender or builder would already see.
The Bottom Line
Do not pay CMLC Ltd for structural cover until the insurer, the lender’s acceptance and the excess are confirmed in writing, because the public documents settle none of the three.
We cannot prove wrongdoing, and the company is real, but if you need a warranty, use a provider your own lender names and compare at least two written quotes.
If you already paid, keep every document, ask the firm and your lender for written confirmation of cover and dispute the payment promptly if the answers do not arrive.

Join the discussion
0 commentsShare your experience or ask a question about this article.
Discussion
Start the conversation
Have a question or something useful to share? Add the first comment.