

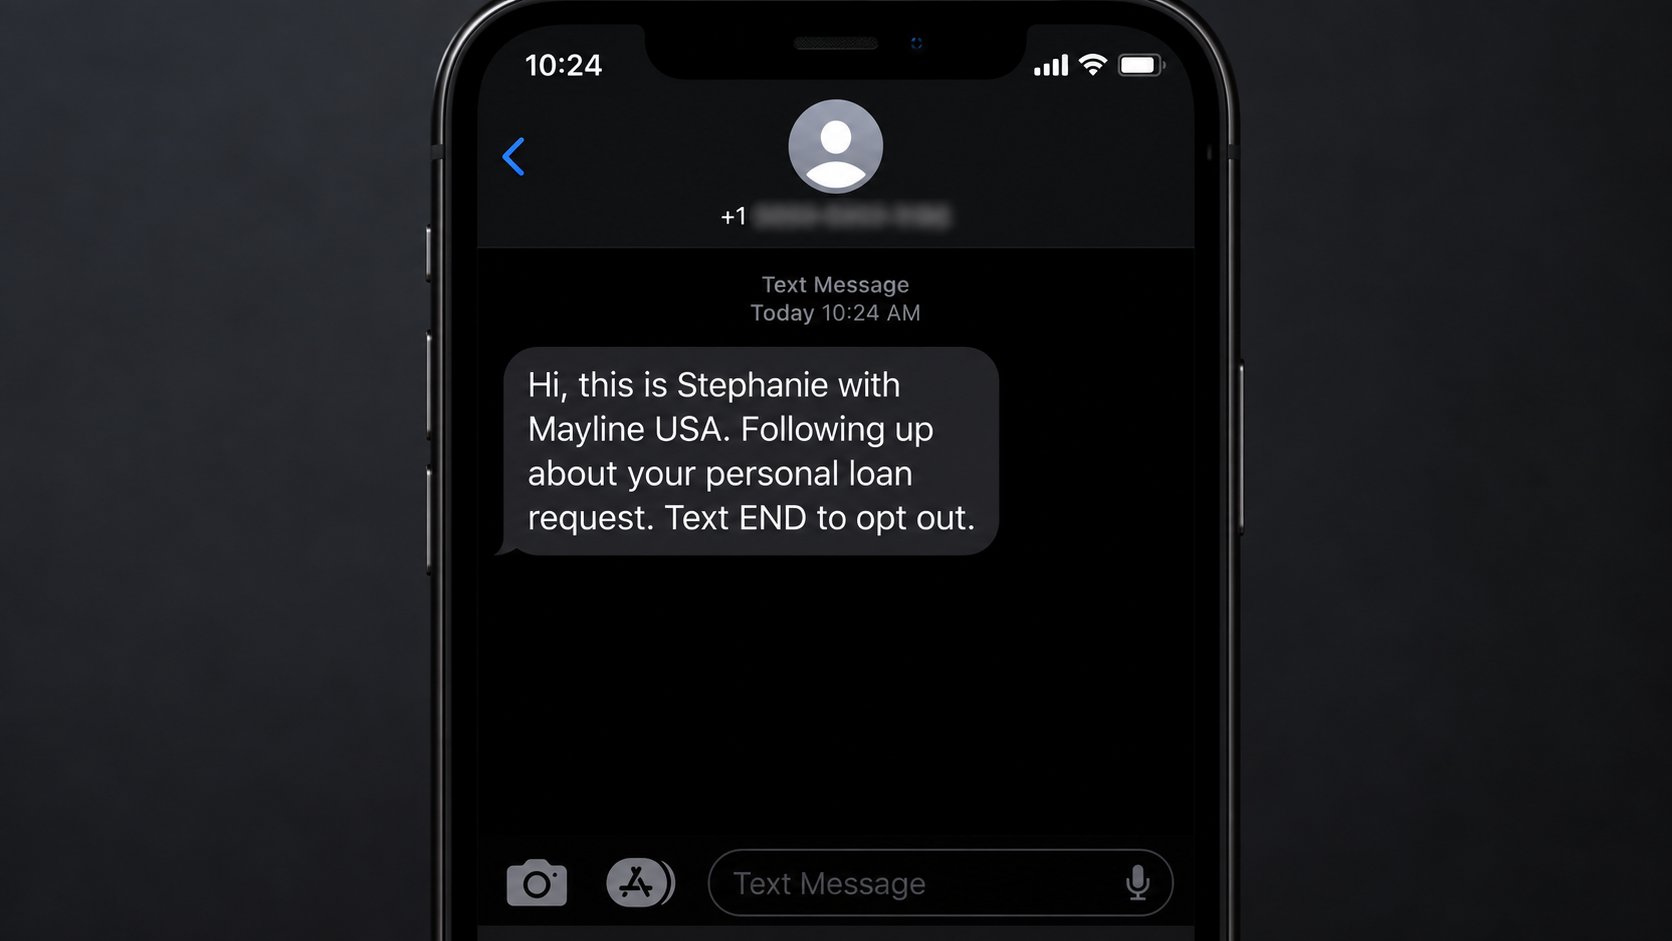
A message from “Stephanie with Mayline USA” may sound like a routine follow-up. The unsettling part is simple: many recipients never requested a personal loan.
That mismatch is the reason to stop, preserve the message, and investigate before replying, calling, or confirming any personal information.
Overview
What the Mayline USA message says
A reported version begins with the recipient’s name, introduces “Stephanie with Mayline USA,” and claims to follow up about a personal-loan request.
It tells the recipient to text “END” to opt out or call a supplied number if they have a few minutes.
The wording is deliberately ordinary. There is no dramatic threat, prize, or urgent payment demand in the opening message.
Why an unrequested loan follow-up is dangerous
A legitimate lender should not pretend you submitted an application when you did not. The false premise is the central warning sign.
Replying can confirm that your number is active. Calling can expose you to a sales script, identity questions, advance fees, or repeated transfers.
The name Mayline USA does not establish who sent the communication. Scammers and lead generators can insert borrowed, invented, or rotating business names.
What investigators can verify
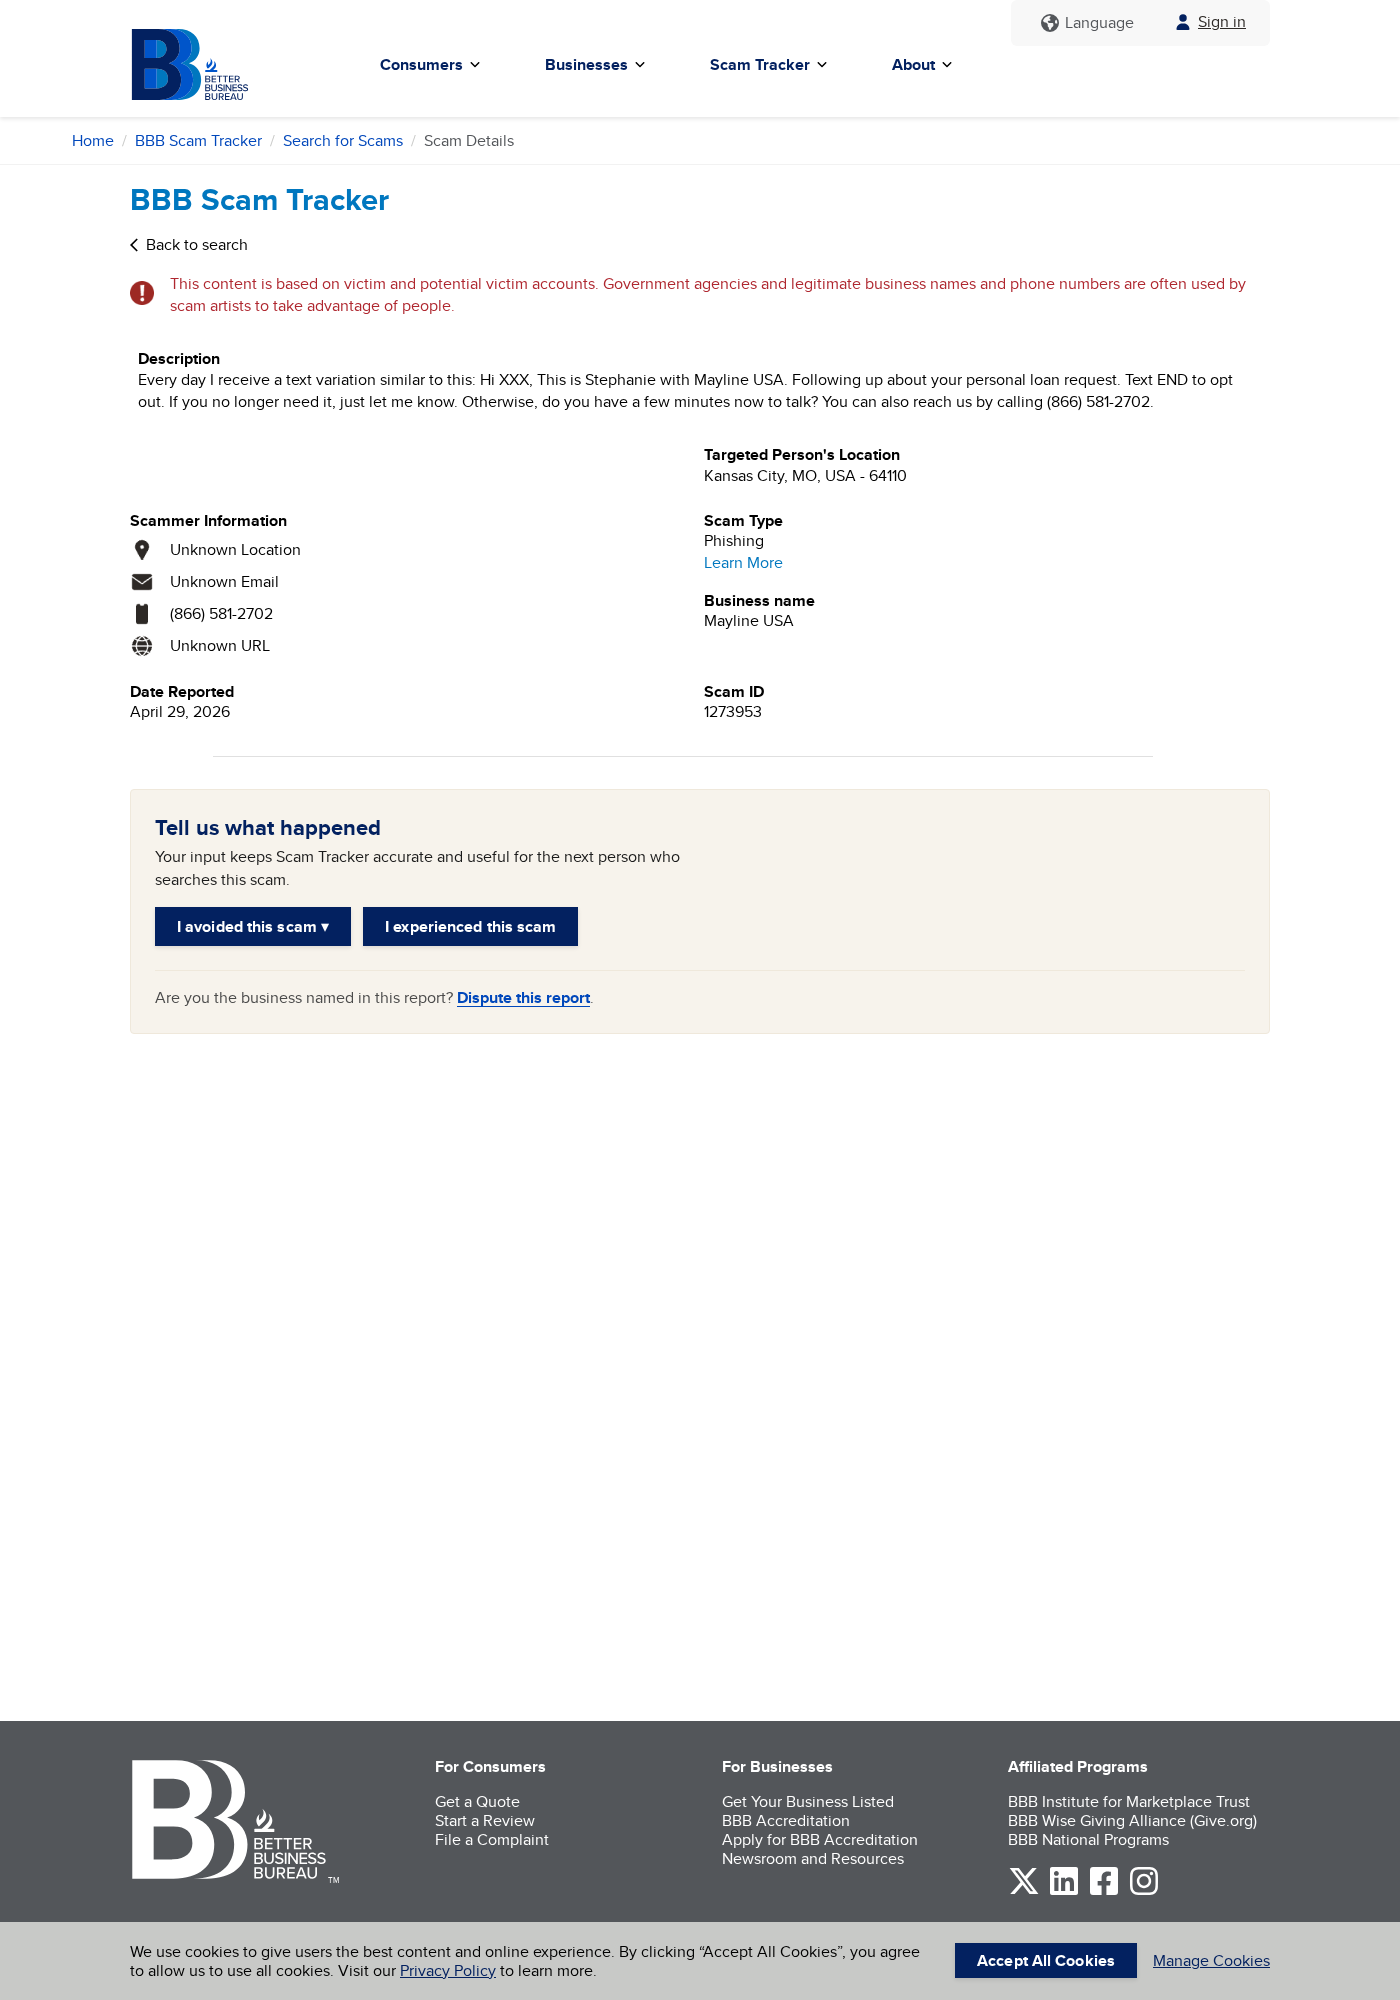
A BBB Scam Tracker report dated April 29, 2026 describes recurring texts using this language and lists `(866) 581-2702` as the callback number.
BBB classifies that report as phishing, while warning that Scam Tracker entries are based on victim or potential-victim accounts.
That report is useful evidence of the message pattern. It is not proof that every communication using the same name has one operator.
- The recipient reported never requesting the loan mentioned in the text.
- The message asks for engagement through a reply or callback.
- No lender, application date, amount, or account reference appears in the reported wording.
- The sender identity cannot be authenticated from the display name alone.
- The safest verification channel is one located independently, not the message itself.
Is the Mayline USA Loan Message a Scam?
If you never applied for a personal loan, treat the text or call as fraudulent or abusive lead generation until independently proven otherwise.
The sender begins with information only you should supposedly know, then asks you to correct the story by replying or calling.
That reversal is useful to scammers. A confused recipient may volunteer a full name, address, birth date, employer, income, or Social Security number.
We cannot conclude from one public report that a genuine business named Mayline USA sent the message.
Names and caller ID values are easy to copy. The warning concerns the unsolicited loan narrative and contact path, not an unsupported accusation against an unrelated company.
The FTC advises ignoring unexpected loan calls and texts when you did not apply. Consumers should not use the callback details supplied by the sender.
Even when the operation is technically selling leads rather than directly stealing money, the false application claim remains deceptive and risky.
How the Mayline USA Loan Text Scam Works
Step 1: Your number enters a marketing or fraud list
The sender may obtain numbers from data brokers, breached databases, old web forms, sweepstakes entries, affiliate leads, or randomly generated dialing lists.
Knowing your name does not prove access to a real loan application. Names and phone numbers are widely traded and frequently exposed together.
Some campaigns use accurate details to create familiarity. Others send generic messages at scale and wait for recipients to identify themselves.
Step 2: The message invents prior consent
“Following up” makes the communication feel like part of an existing conversation. The phrase quietly assumes that you initiated the relationship.
Recipients may wonder whether a spouse applied, whether they forgot a form, or whether someone stole their identity.
That uncertainty creates engagement. The sender needs only a reply, callback, or link click to move the contact forward.
Step 3: The opt-out instruction tests your number
“Text END to opt out” resembles legitimate compliance language. In an untrusted message, replying also confirms that a person reads the number.
An active number can become more valuable for additional calls, resale, or future scams tailored to the recipient’s reaction.
Use your phone’s spam-reporting controls instead. In the United States, suspicious texts can also be forwarded to 7726.
Step 4: A callback opens the sales or phishing conversation
The person answering may say an application is incomplete, preapproved, matched with lenders, or eligible for unusually favorable terms.
The script can request identity data under the pretext of locating the supposed application or checking eligibility.
A dishonest operator may also request an application fee, insurance payment, processing charge, tax, deposit, or gift-card payment.
Real lenders do not guarantee loans before reviewing creditworthiness, and legitimate fees are not paid through gift cards or cryptocurrency.
Step 5: Your information becomes the real product
Some callers may be lead generators seeking to sell your details to lenders or other marketing companies rather than offering a loan themselves.
That does not make the false opening harmless. You can lose control of sensitive information and receive a wave of new solicitations.
More dangerous groups use the same conversation to prepare identity theft, account takeover, synthetic identity applications, or targeted impersonation.
Step 6: The names and numbers rotate
Once complaints accumulate, campaigns can change the representative name, business label, local caller ID, toll-free number, and opening script.
This is why blocking one number is useful but incomplete. The durable defense is recognizing the invented loan-request story.
Search results for a phone number can help, but a clean result does not make a new number trustworthy.
Why You May Receive Dozens of Similar Calls
A sudden cluster does not necessarily mean dozens of separate companies independently selected you. One lead can be distributed repeatedly.
Comparison sites and affiliate forms sometimes state that information may be shared with marketing partners. Consent language can be buried near a submit button.
A malicious form can collect the same data without meaningful disclosure. Stolen datasets can also circulate among unrelated operators for years.
If you recently entered information on a loan, debt-relief, insurance, job, prize, or credit website, review exactly where the form appeared.
That investigation may explain the timing. It does not mean every later caller is authorized, licensed, or connected to the original website.
If you submitted nothing, consider whether an identity thief attempted an application. Check credit reports and lender inquiries rather than trusting the caller’s explanation.
How to Tell a Real Lender From an Impostor
Start with your own records. A legitimate follow-up should correspond to an application you can locate, including the lender, date, website, and disclosures.
Find the institution’s official website independently. Do not use links, numbers, or search advertisements supplied by the unexpected sender.
Check state licensing requirements and the Nationwide Multistate Licensing System when applicable. A claimed representative should connect to a verifiable company.
Ask for a written notice identifying the legal lender, physical address, license information, loan amount, annual percentage rate, fees, and privacy practices.
Refusal, pressure, guaranteed approval, or insistence on secrecy strongly indicates that the conversation should end.
Never provide an online banking password, debit-card PIN, remote computer access, or one-time security code to someone offering a loan.
Could the Message Signal Identity Theft?
One spam text usually means your contact information is circulating. It does not automatically prove that someone opened an account in your name.
Additional signs increase concern: unfamiliar hard inquiries, lender letters, new accounts, password-reset notices, or calls referencing accurate application details.
Review reports from all three major credit bureaus. A single bureau may show an inquiry or account that another has not yet recorded.
Consider a free credit freeze if your identity data may be exposed. A freeze can restrict new creditors from accessing your file.
Also secure the email account tied to financial services. Email access can let a criminal intercept alerts and reset passwords.
What Not to Say During an Unexpected Loan Call
Do not confirm your full legal name, birth date, address, employer, income, bank, or the last digits of an identification number.
A caller may already possess fragments and ask you to “verify” the rest. Each confirmation improves the profile they can reuse.
Never answer security questions about relatives, previous addresses, vehicles, mortgages, or credit history for an unsolicited caller.
Do not read a code delivered by text or email. That code may authorize a password reset, account login, or financial transaction.
Avoid saying which bank you use or how much credit is available. That information helps criminals design a more believable second approach.
If the caller claims a deadline, ask for written disclosures sent through the verified lender’s official domain. Then end the call.
Do not let the caller transfer you to a supposed credit bureau, attorney, police officer, or fraud department.
Scam teams often pass calls between roles. Multiple convincing voices can still belong to the same operation.
Call trusted institutions yourself using numbers printed on cards, statements, or verified government pages. Never accept a warm transfer as verification.
If the contact becomes threatening, save the voicemail and report it. Owing money does not give a caller authority to arrest or intimidate you.
Company, Address, and Fulfillment Checks
The displayed name may be borrowed or invented
“Mayline USA” is a label inside a reported message, not authenticated proof of the sender’s legal identity.
Search corporate registries, lending licenses, official domains, and archived pages. Match the exact legal name rather than accepting a similar phrase.
Do not blame a same-named business without evidence linking it to the phone campaign. Impersonation is common in financial fraud.
An address must match the licensed lender
A genuine lender should provide a verifiable business address that matches regulatory records, disclosures, and the official website.
Virtual offices, residential properties, empty lots, unrelated businesses, and mailbox stores are poor substitutes for transparent licensing information.
Loan scams may use a real building address copied from another company. Verification requires matching several independent records, not merely locating the street.
Phone and email behavior reveal the operation
A rotating series of numbers, prerecorded messages, vague representatives, and refusal to send disclosures indicates a low-trust operation.
Legitimate support should identify the legal lender, explain how consent was obtained, and honor a clear request to stop contacting you.
Do not trust a toll-free prefix by itself. Internet calling services make professional-looking numbers inexpensive and disposable.
There should be no product fulfillment story
Unlike a supplement or gadget purchase, a loan contact should not involve a warehouse, shipping center, or package-return address.
If the caller pivots to buying gift cards, depositing a check, forwarding money, or receiving equipment, the arrangement has departed from normal lending.
Those instructions are hallmarks of advance-fee fraud, fake-check scams, money-mule recruitment, or account laundering.
What to Do if You Have Fallen Victim to This Scam
- Stop communicating. Do not reply further, call back, click links, or send additional documents. Block the number after preserving evidence.
- Save the full message trail. Capture numbers, dates, voicemails, names, links, promised terms, requested payments, and transaction receipts.
- Contact your financial institution. If you sent money or card details, explain that the transaction involved a suspected loan scam and ask about recovery options.
- Protect your identity. Change exposed passwords, enable multifactor authentication, review credit reports, and consider fraud alerts or credit freezes.
- Report the contact. Forward suspicious texts to 7726 and file reports with the FTC, your state regulator, and relevant financial authorities.
- Reject fake recovery help. Anyone promising guaranteed money recovery for an upfront fee may be targeting victims a second time.
- Check every device used. If you opened a link or installed software, scan with Malwarebytes and remove unfamiliar apps, profiles, or browser extensions.
- Reduce repeat exposure. Use AdGuard to block malicious advertising and tracking, then silence unknown callers without disabling legitimate account alerts.
If you shared a Social Security number, file an identity-theft report and follow its recovery plan. Keep a dated log of every protective step.
Frequently Asked Questions
Why does the text know my name?
Name-and-number pairs are widely available through data brokers, breaches, public records, old forms, and previously shared marketing leads.
Should I text END to opt out?
Not when the sender is unknown and the message is false. Use spam-reporting controls and forward the text to 7726 instead.
Does the message prove someone applied in my name?
No. It may be a fabricated opener. Check credit reports and official lender correspondence for independent evidence.
Is `(866) 581-2702` always fraudulent?
The number appeared in one public Scam Tracker report. Numbers can be reassigned or spoofed, so evaluate the message and verify independently.
Can a legitimate lender make an unsolicited offer?
Marketing offers exist, but a sender should not falsely claim to follow up on an application you never made.
What information should I never provide?
Never disclose passwords, PINs, one-time codes, full banking credentials, or identity documents to an unverified loan caller.
The Bottom Line
An unexpected “Mayline USA” loan follow-up should be treated as dangerous when no application exists. Its ordinary tone is part of what makes it effective.
Do not engage through the supplied contact details. Preserve the evidence, verify through independent channels, and protect your credit if sensitive information was exposed.

Join the discussion
0 commentsShare your experience or ask a question about this article.
Discussion
Start the conversation
Have a question or something useful to share? Add the first comment.