

A caller says an old debt has reached the courts. A document follows, headed “Notice of Enforcement,” and the conversation suddenly feels much more serious.
Before you arrange a payment, there is one important distinction to make: a document can mention a real institution without coming from it.
Overview
The reported debt-collection impersonation
HM Courts and Tribunals Service, or HMCTS, warns about callers claiming to collect money owed to “Media Services UK Ltd.”
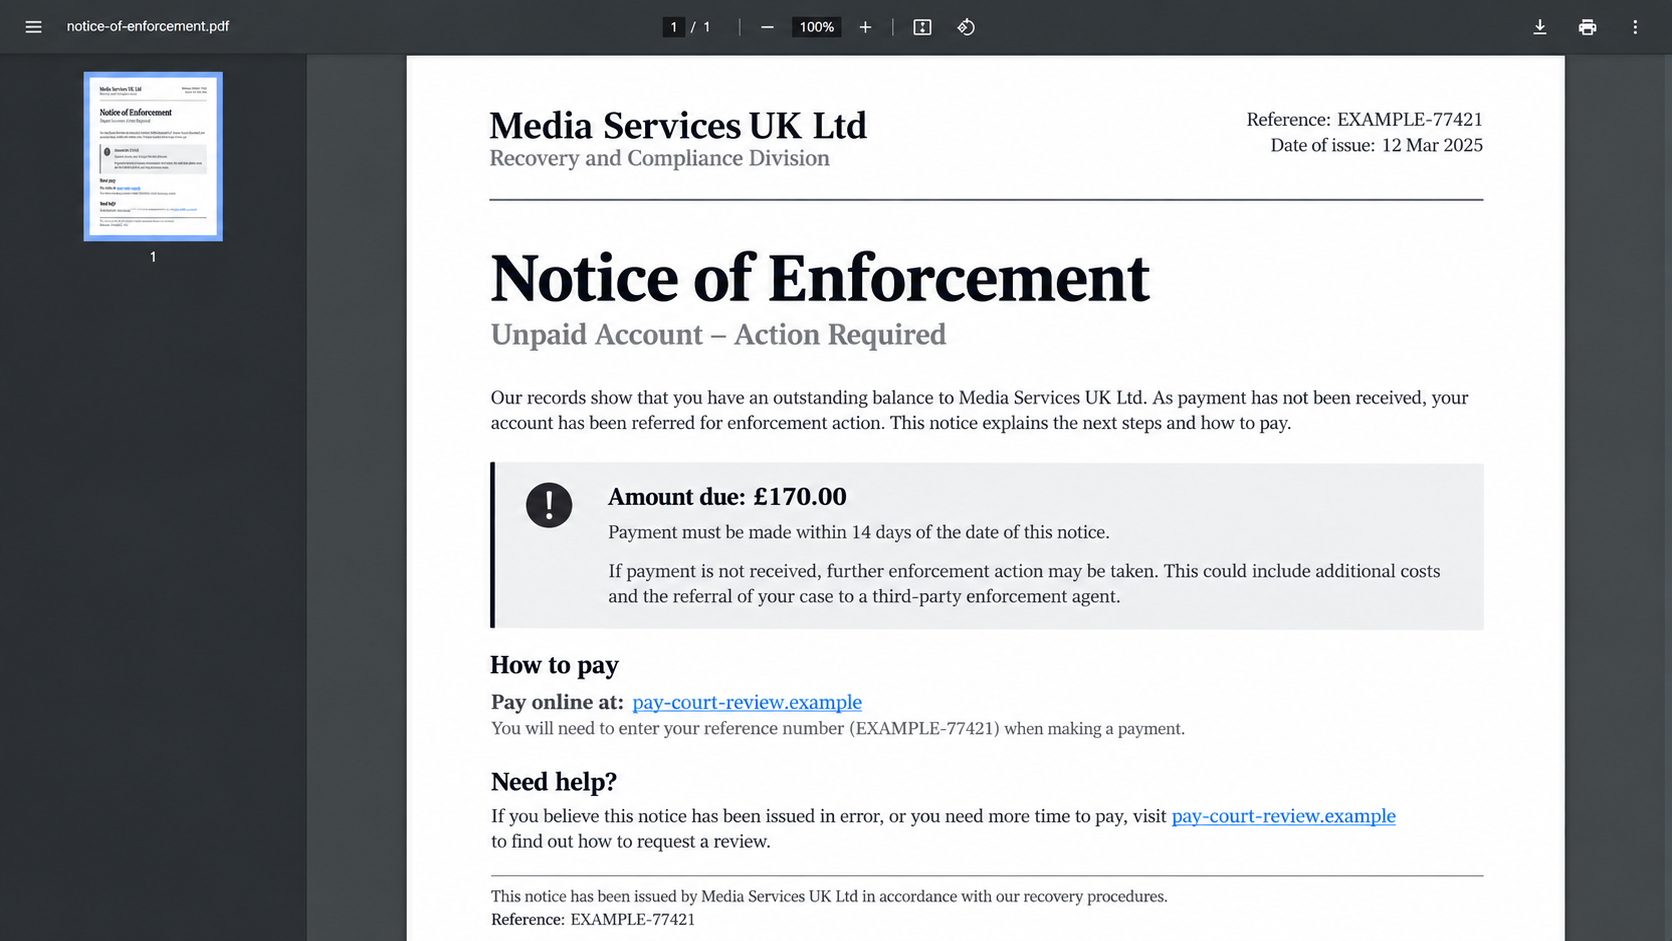
According to HMCTS, some targets also receive fake Notices of Enforcement that claim to have been issued by the court service.
The agency explicitly treats this as a scam. The warning concerns the people making those claims, not a finding that every debt linked to a similar name is fictitious.
Why the document changes the conversation
A cold call can be ignored. A formal-looking enforcement notice feels harder to dismiss, especially when it arrives after the caller has described a balance.
The two parts reinforce each other. The caller points to the document, and the document points back to a number or payment route controlled by the caller.
Neither is independent confirmation. A real court matter should be traceable through the court or tribunal using contact details found on GOV.UK.
The safest first response
Do not disclose bank information or transfer money while you are on the unexpected call. Save the details and end the conversation.
Find the relevant court through HMCTS’s official court finder. If the caller claims to be an enforcement officer, verify the named organization independently.
- Ask what case, court, and reference number the caller alleges.
- Do not use a callback number from the suspicious notice.
- Check whether any actual order exists through an official channel.
- Report the suspicious contact through the UK’s fraud-reporting route.
A real obligation can be dealt with after verification. Pressure to decide during one call is a reason to slow down.
How the Fake HMCTS Enforcement Notice Scam Works
Step 1: Open with a debt you did not expect
The scammer contacts someone by phone and says money is owed to Media Services UK Ltd. A surprise debt leaves the recipient trying to remember a transaction.
That uncertainty gives the caller room to supply their own explanation. They may invoke a service, an overdue account, or a case the recipient has never seen.
HMCTS’s published warning identifies the claimed creditor and the use of false enforcement notices. It does not provide a universal script for every call.
Step 2: Borrow the authority of a court
The caller may claim a court stage has begun or imply that an enforcement agent is involved. The reference to HMCTS is meant to make an ordinary question feel urgent.
Caller ID is not proof. HMCTS warns that phone spoofing can make a call appear to come from a trusted government number.
A threatening tone can also suppress questions. People may worry that asking for evidence will make the situation worse, even though verification is reasonable.
Step 3: Send a forged Notice of Enforcement
Some targets receive a document claiming HMCTS issued it. Headings, reference numbers, payment instructions, and court language can make the page appear official.
The notice is part of the claim, not evidence for the claim. A printed PDF or emailed attachment can be created without any court involvement.
Read the document for clues, but do not rely on its own contact section to check authenticity. That section can route you straight back to the impostor.
Step 4: Push for payment or financial details
The object is to make the recipient part with money or sensitive information before confirming the matter through a separate channel.
HMCTS says callers claiming to be its bailiffs or enforcement agents will not ask for bank details or demand a transfer using sort code and account number.
That does not mean every legitimate court payment is impossible by phone. HMCTS notes it may call about a warrant and offer card payments in appropriate circumstances.
The key is independent verification of who is calling and what case exists. Do not infer legitimacy from a smooth explanation or a familiar-looking number.
Step 5: Keep the victim inside the caller’s loop
If you challenge the debt, the caller may urge you to dial a number on the notice. That feels like checking, but it is still a self-contained loop.
Another message can arrive from a different name or email address. A second costume does not create a second source of evidence.
HMCTS separately warns about letters and emails naming Financial Data Management Limited. That is another reported pattern, not proof that both contacts are one operation.
Whatever name is used, step outside the supplied phone numbers and payment links. Look up the court, creditor, or enforcement firm yourself.
What Genuine Court Contact Can Look Like
People do receive authentic court documents and legitimate debt-collection messages. It would be unsafe to assume every unexpected notice is fraudulent.
A real enforcement issue should have a traceable basis: a case, an order, and a responsible court or authorized officer that can be independently confirmed.
HMCTS says it may contact people about a warrant of control. That nuance matters when checking a call; the warning is not a blanket claim that courts never phone.
Instead, examine the requested behavior. An unexplained bank transfer or demand for bank details during an unsolicited call is a clear reason to stop.
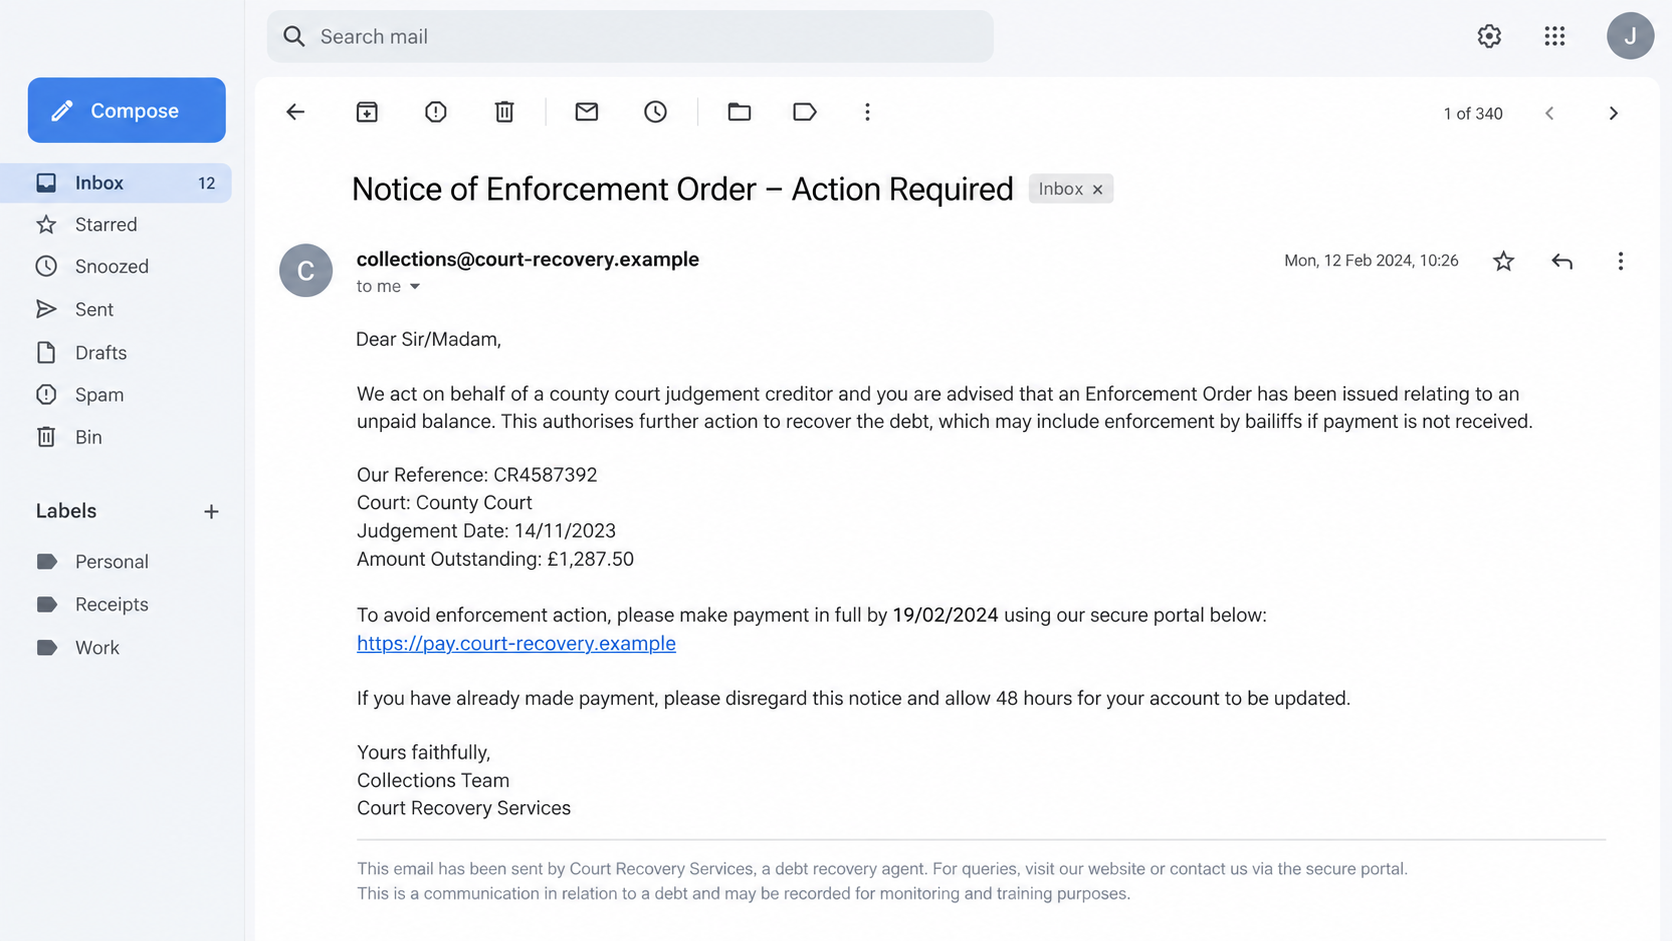
The second image is a fictional reconstruction of a suspicious email thread. It is not the actual document reported to HMCTS.
How to Verify a Debt or Enforcement Claim
Collect facts, not instructions
Before ending the call, you can note the alleged case number, court, creditor, amount, caller name, and claimed organization. Do not confirm personal details in return.
You are collecting a lead for verification, not accepting the story. A fabricated reference number is still possible.
Save the email or letter and, if feasible, the caller ID shown on your phone. Remember that displayed numbers can be spoofed.
Use a separately sourced court contact
Find the court or tribunal through GOV.UK’s official search tool. Ask whether the case reference and document correspond to a matter involving you.
If the caller says they work for a High Court enforcement company, find that company’s published contact information independently. Ask about the specific claim.
Do not use a search ad as your only route to a government service. Check the web address carefully before entering any identifying information.
Ask for a clear written basis
A legitimate creditor should be able to explain what the debt is for and how the amount was calculated. Compare the answer with your own records.
If you dispute a genuine debt, seek appropriate advice. Verifying a notice does not mean admitting liability, and a scam article cannot decide a legal dispute.
Warning Signs That Are Easy to Miss
- The caller refuses to let you call the court through a publicly listed number.
- The notice uses an email domain unrelated to the court service.
- Payment is demanded by direct bank transfer during an unsolicited call.
- The reference number cannot be confirmed through the alleged court.
- A deadline is so short that ordinary verification seems impossible.
- The caller threatens immediate consequences if you tell a family member or adviser.
One of these signs may justify a pause. Several together make the need for independent confirmation even stronger.
Do not focus only on spelling mistakes. Fraudulent documents can be well formatted, and legitimate documents can contain ordinary human errors.
Why “Just Call This Number” Is Not a Verification Method
When a caller gives you a second number, you have not escaped their information channel. Both numbers may reach the same group.
The same problem applies to QR codes and links printed on a letter. A document cannot validate itself by directing you to a website it supplies.
Use a phone number found on GOV.UK or in correspondence you already trust. Type the address yourself, then ask about the alleged case.
This simple separation is the difference between checking a claim and continuing a scripted conversation.
If the Caller Reaches a Relative or a Workplace
Debt language can be embarrassing. A fraudster may count on the recipient wanting the matter handled quietly before a family member or colleague hears more.
That pressure is especially strong if a receptionist takes the call or a letter arrives at a shared address. The target may rush to preserve privacy.
Tell staff not to confirm your schedule, bank, or personal details to an unsolicited debt caller. They can take a name and alleged reference without endorsing anything.
If a family member receives the notice, ask them not to pay on your behalf. A kind attempt to help can still send money into an account controlled by scammers.
Make one person responsible for verification, then share the result with those who need it. That prevents multiple relatives from calling numbers printed on the fake document.
What if the caller says officers are coming today?
Immediate consequences are meant to force a decision while you are frightened. Record the exact claim and ask an independently contacted court or qualified adviser about it.
Do not argue through the caller’s script. End the call and use a reliable number. If you feel physically threatened, contact local police through appropriate channels.
Separating fear from verification is difficult, but it is safer than paying a stranger to make the threat disappear.
Payments, Bank Details, and the Recovery Window
A bank transfer can move quickly. If you have already sent funds, the first call should usually be to your bank’s fraud team, not to the supposed collector.
Give the bank the transaction time, destination, reference, and any messages. Ask what can be recalled and whether additional payments are pending.
If you used a card, ask whether the merchant charge can be disputed and whether the card should be replaced. Follow the issuer’s guidance.
If you disclosed online banking credentials, tell the bank immediately. Changing a password matters, but the bank may also need to monitor or freeze activity.
Keep expectations realistic. Recovery is not guaranteed, and anyone promising to retrieve the money for an upfront fee deserves separate scrutiny.
How to Handle an Actual Debt After the Scam Check
Verification may reveal a real debt unrelated to the suspicious call. That does not validate the scammer’s payment request or the forged notice.
Ask the legitimate creditor or court for the written basis, current balance, and proper payment channel. Keep the two trails separate.
If you disagree with the debt, seek debt or legal advice from an appropriate UK service. Do not let a fraudster define your options.
A genuine issue may have its own deadlines, so do not discard it merely because an impostor contacted you first. Accurate records help you respond safely.
The objective is not to prove every caller wrong. It is to make sure that any payment or disclosure goes to the right organization for a real reason.
What To Do If You Fell Victim
- End contact and document the timeline. Save calls, messages, the purported notice, payment instructions, and the amount sent. Write down what the caller claimed before details fade.
- Contact your bank immediately if you paid. Say you may have transferred money after a false court-enforcement demand. Ask about a transfer recall, card dispute, and protection for the affected account.
- Check for a real case independently. Locate the court or tribunal on GOV.UK. Ask whether the case number and notice are authentic, and keep that answer with your records.
- Secure any information you shared. If you gave card details, request a replacement or block. If you entered passwords through a link, change them and enable multifactor authentication.
- Check devices if a file or link caused unusual behavior. Run an updated Malwarebytes scan where appropriate. Review browser notifications and consider AdGuard to reduce unwanted advertising and redirects.
- Report the attempt. HMCTS directs people to the UK’s Report Fraud service. Send the fake notice and details of the call.
Take the next step promptly, but without panic. A bank and an official court contact can help separate financial recovery from any genuine legal issue.
Frequently Asked Questions
Does HMCTS ever call people about enforcement?
Yes. HMCTS says it may call about a warrant of control. Verify the caller independently and reject requests for bank details or a direct transfer.
Is a Notice of Enforcement always fake?
No. The warning concerns forged notices in a particular reported debt-collection scam. Confirm an individual notice through the relevant court or authorized agent.
What is the role of Media Services UK Ltd in the warning?
HMCTS says scammers claim to collect money owed to that name. The warning identifies the claim used by callers; it does not establish every detail of the named entity.
Can I trust the phone number shown on the call?
No. Caller ID can be spoofed. Hang up and find a published number for the court or organization yourself.
Should I ignore the letter if I think it is fraudulent?
Do not pay or use its contact details. Verify the alleged case promptly through official channels, since a real matter should not be overlooked.
Where do I report a fake HMCTS notice?
Use the reporting guidance on GOV.UK’s HMCTS warning page, including Report Fraud for suspicious calls, emails, or payments.
The Bottom Line
The fake HMCTS enforcement notice scam uses a frightening phone call and official-looking paper to make an unverified debt feel immediate.
Save the evidence, end the call, and check the alleged case through a court contact found independently. Pay only after you know what is real.








