

The caller knows your name. A law enforcement warrant is supposedly coming unless you stay on the line and settle a problem before the office closes.
That is a frightening thing to hear, especially when the number on your screen resembles a government office. The next few minutes deserve a pause.
Overview
The threat behind the call
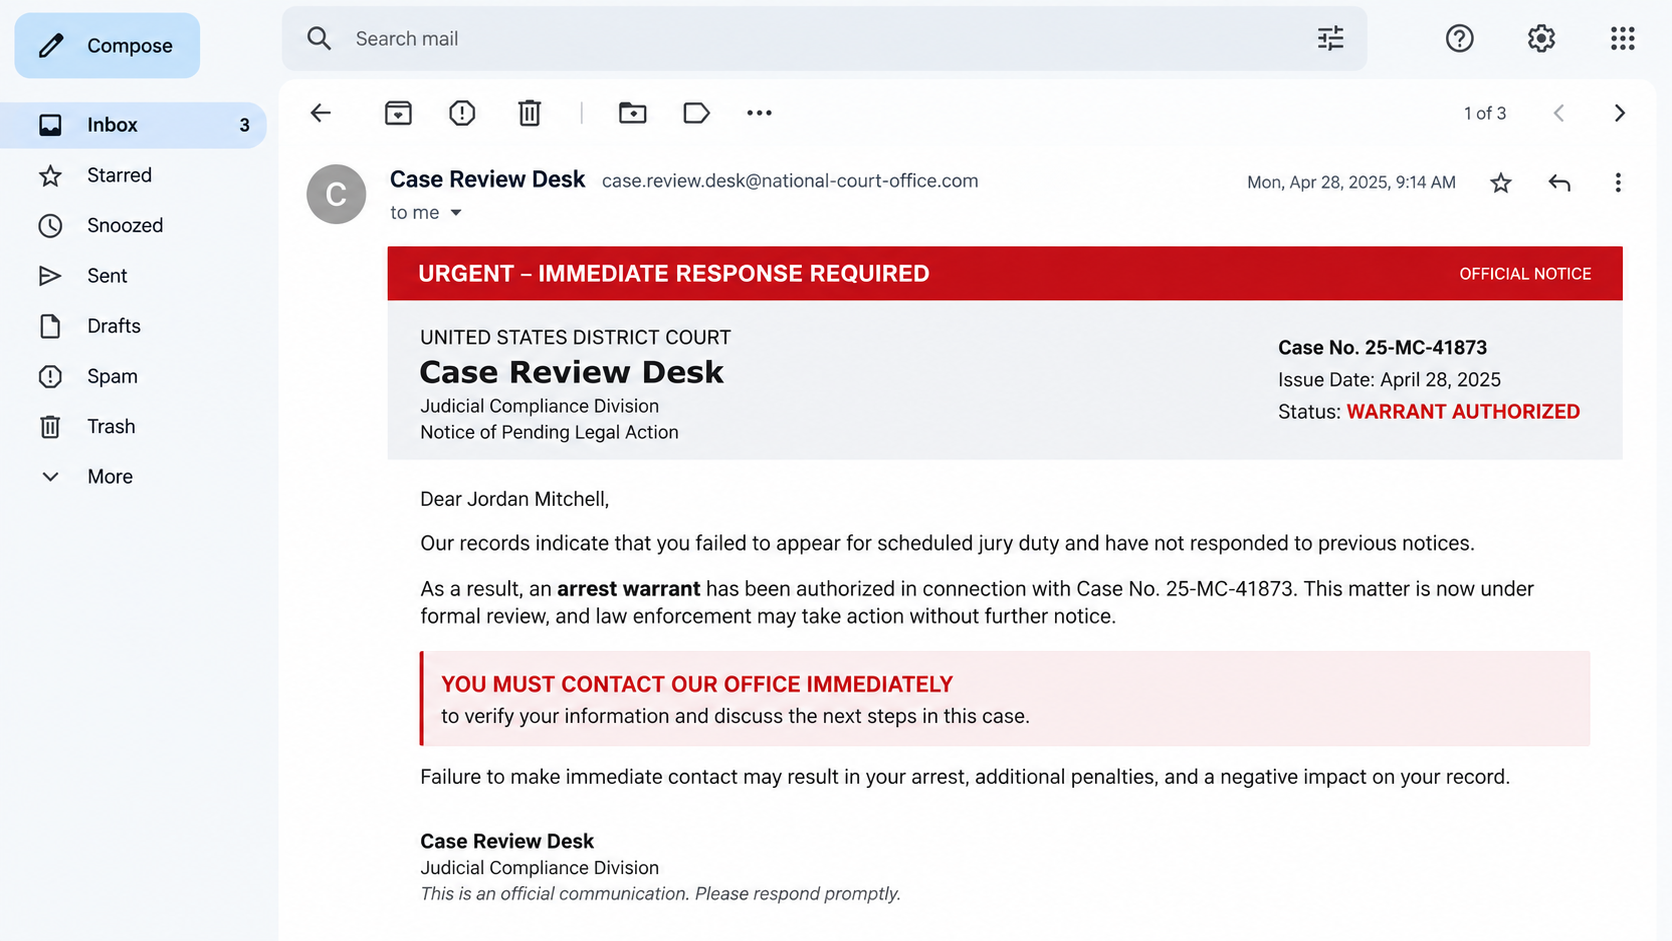
A fake law enforcement warrant scam begins with a claimed investigation, missed jury duty, or criminal allegation. The caller says a payment or confidential cooperation will prevent arrest.
The threat can arrive by phone, email, text, or video call. The exact agency changes, but the instruction to obey an unverified stranger remains central.
Some victims are told they must not speak with relatives, their bank, or local police. That secrecy is not a lawful investigative procedure; it protects the scammer.
What the FBI documented in 2026
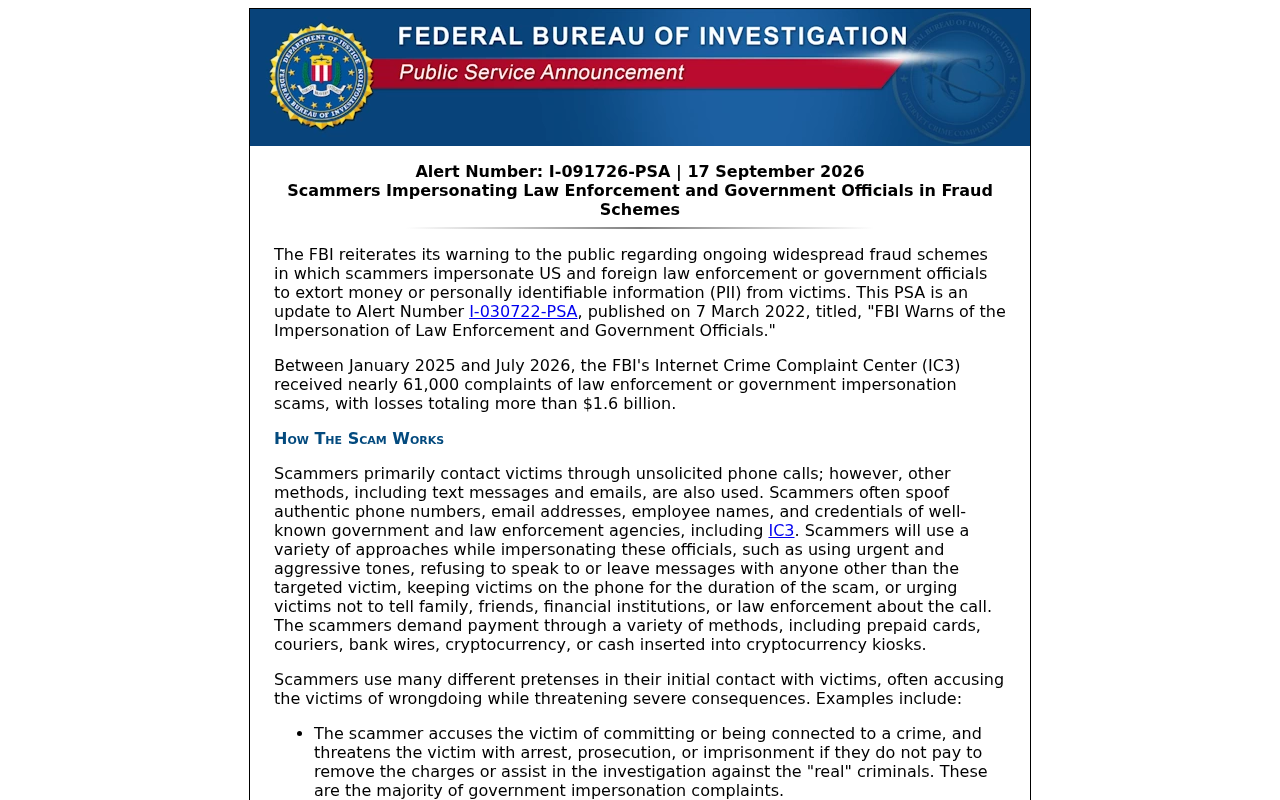
In a September 17, 2026 public alert, the FBI warned that scammers impersonate U.S. and foreign officials to extort money or personal information.
IC3 received nearly 61,000 government and law enforcement impersonation complaints from January 2025 through July 2026. Reported losses exceeded $1.6 billion.
Those are complaints across several variants, not proof that every caller uses a warrant story. The scale shows why a single threatening call should be treated seriously.
Several stories, one demand for control
The FBI alert describes common pretexts that can be tailored to the person reached:
- A supposed warrant after missed jury duty or a court date.
- An allegation that the recipient’s identity was connected to a crime.
- A claim that a passport, driver’s license, or professional license is expiring.
- A foreign-police warning aimed at an immigrant or international student.
Each pretext tries to replace verification with immediate obedience. A badge number, copied seal, or convincing video background can be fabricated.
Why a Spoofed Number Is Not Proof of Authority
Caller ID displays information provided through telephone systems. It is not a reliable identity document. Fraudsters can make a call appear to come from a real agency.
The FBI says scammers also spoof names, email addresses, and credentials. Some use artificial intelligence to look like officials during video calls.
A person who presents an employee name may be reading it from a public directory. An official-looking number only tells you what appeared on the screen.
Callers may prevent you from hanging up by warning that the arrest will happen immediately. Staying connected lets them guide every search, doubt, and payment decision.
The safer move feels counterintuitive: end the call while the alleged danger sounds urgent. Then find the real agency independently and ask whether it contacted you.
Do not use a callback number, website, or verification code supplied by the caller. That merely routes your check through the same operation.
The FBI’s alert includes examples involving professional licenses and foreign officials. Those threats are tailored because they strike at employment, immigration, and reputation.
They also explain why a calm, educated person might comply. Fraud is not a test of intelligence; it is an attempt to control decisions under stress.
How the Fake Law Enforcement Warrant Scam Works
Step 1: The caller creates a plausible official opening
A phone call may begin with the name of a police department, federal agency, court, or professional board. The caller offers a name and case number.
These details can be invented in seconds. Some scripts ask you to confirm your full name before explaining the accusation, gathering information while appearing procedural.
The call may be followed by an email with a seal-like graphic. The email’s purpose is to make a voice claim feel documented.
Step 2: The accusation becomes personal
The caller says you missed jury duty, ignored a summons, or were linked to a serious investigation. They may claim an arrest order has already been signed.
Professionals can be told their license will be revoked. Foreign nationals may hear that a passport will be canceled or that deportation is imminent.
The person is not expected to analyze the law. The script is designed to make them imagine the worst outcome before they can check anything.
Step 3: Verification is moved inside the scam
If you ask to verify, the caller may transfer you to a second “officer” or send a link to a matching page. Both can be controlled by the same group.
A fake video call can show a uniform or an office-like background. The FBI warns that synthetic media can deepen the illusion of official contact.
The caller may recite a real agency address. Knowing that address does not prove the caller works there, just as a forged letterhead does not prove authorship.
Step 4: The victim is isolated
A common instruction is to stay on the phone and tell no one. The caller may say the case is sealed or that a bank teller is under investigation.
This prevents the person from hearing a contradictory voice. It also reduces the chance that a financial institution will stop an unusual withdrawal.
Some callers insist on location updates or keep the call running while the victim travels. That is a red flag, not a feature of legitimate law enforcement.
Step 5: A payment is framed as protection
The scammer may call the money a fine, bond, verification deposit, or evidence-holding transfer. The labels change while the destination remains outside normal court payment channels.
The FBI lists prepaid cards, cash couriers, wires, cryptocurrency, and cash inserted into crypto kiosks among the requested methods.
A demand to move money into a “safe” account can be the same theft with different language. No legitimate official needs your assets moved to protect them.
Step 6: The operation may ask for more
Once a payment is made, the caller can invent another fee or insist a transaction failed. They may also ask for account logins or identity documents.
A victim who hesitates may be threatened again. The initial payment does not resolve the fictional case because the case was a tool, not a legal process.
After the call, another impostor may offer help recovering the money. Treat that contact as a new threat until independently verified.
Four Ways to Verify the Person Behind the Threat
The agency name is not a verified identity
Write down the agency, employee name, and case number. Then call a published switchboard number found through an official website, not the incoming call.
If the agency has no record of the case, report the attempted impersonation. If it does, ask how legitimate notices are served and handled.
Do not rely on a digital badge image or a uniformed video. Both can be copied, edited, or generated without any agency involvement.
An address can be copied from public records
A caller may give the correct courthouse address to sound credible. That address is useful only if you independently contact the court through its official directory.
Documents may list a payment location or courier pickup point. A genuine agency would not convert an alleged warrant into an unrecorded cash handoff.
Check the jurisdiction. A distant office claiming immediate local arrest deserves direct confirmation from that office and, if needed, your local police.
A callback number can lead to the same scam desk
Scammers can operate multiple numbers and transfer calls internally. A different voice on a callback does not make the office authentic.
Search for the agency’s official contact page, then dial the number yourself. Tell the switchboard you received a threatening call and want to verify it.
A real government office can explain how it communicates about jury service, warrants, or licenses. It will not demand a gift card to prove you are innocent.
The payment route exposes the claim
Ask for a publicly documented court or agency payment process, then verify it on the agency’s own site. Do not accept a private wallet or kiosk address.
The FBI states that law enforcement and government officials will not demand payment by prepaid card, cryptocurrency, or courier.
Even a bank wire should not be sent merely because the caller says it is official. Verify the case and payee independently before considering any payment.
Three Variants That Need Different Questions
The missed jury-duty story
The caller may say you failed to report and a judge issued a warrant. They might offer to suspend it if you pay a “bond” immediately.
The FBI counted 6,833 complaints involving missed jury duty or court-date pretexts from January 2025 through July 2026, with nearly $36 million in losses.
Call the actual court clerk using a number on the court’s official website. Ask whether a summons was issued and how missed service is handled locally.
Do not treat a caller’s refusal to let you hang up as evidence that the matter is urgent. It is evidence that they need your attention controlled.
The professional-license threat
A clinician or other licensed professional may hear that their credential was used in a crime or is about to expire. The threatened loss is their livelihood.
The FBI reported 3,322 complaints in this category during the same period and more than $37 million in losses. That figure concerns reported cases, not every profession.
Look up your licensing board and check your status directly. If the caller supplied a document, ask the board whether its format and case reference are genuine.
Also tell your practice manager or compliance contact when appropriate. A scammer’s demand for secrecy should not override your normal reporting procedures.
The foreign-official warning
International students and people with ties abroad can be threatened with passport cancellation, extradition, or immigration consequences by someone posing as foreign police.
The FBI recorded 1,809 complaints involving this form of impersonation and more than $140 million in reported losses across the same period.
These calls may use a language you speak at home or a video backdrop resembling an overseas station. Familiarity can make the message feel personal.
Contact the relevant consulate or agency through independently published details. If a U.S. immigration issue is claimed, seek qualified legal advice instead of following the caller’s payment route.
In every variant, the strongest question is the same: can the alleged case be confirmed without relying on a channel the stranger supplied?
What to Do if You Have Fallen Victim to This Scam
- End contact immediately. Hang up, stop responding to messages, and do not follow a request to remain on the phone while you seek help.
- Call your bank or card issuer. Tell the fraud team what was sent, when, and by which route. Ask about recalls, disputes, account monitoring, and replacement credentials.
- Contact the money-transfer or crypto service. Provide transaction IDs and destination details. A cryptocurrency transfer is difficult to reverse, but rapid reporting can still support tracing.
- Preserve evidence. Save call logs, screenshots, messages, receipts, wallet addresses, case numbers, and names the caller used. Do not edit the originals.
- Verify the claimed legal issue separately. Use an agency’s published phone number or visit a local police station. Do not assume the scam call settled anything.
- Protect accounts and devices. Change exposed passwords and enable multifactor authentication. If you installed software or opened a suspicious file, scan with Malwarebytes.
- Reduce repeat exposure. AdGuard can block known malicious ads and pages, but it cannot authenticate a caller. Keep using independent official contact channels.
- Report the fraud. File a local police report and an IC3 complaint. Include the contact details and financial information requested by the FBI.
Fear is the mechanism that made the call work. Once the call ends, you can take back time to document, verify, and ask for help.
If you shared a Social Security number or identity document, use IdentityTheft.gov to build a recovery plan and consider credit freezes.
Frequently Asked Questions
Can police really call about a case?
Agencies can contact people by phone, but the FBI says officials will not call or text to demand payment or sensitive information.
What if the caller ID showed a real police number?
Caller ID can be spoofed. Hang up and dial the agency’s published number yourself before discussing any case or payment.
Is a case number proof that a warrant exists?
No. A caller can invent a case number or copy one. Verify it directly with the relevant court or agency.
Why would a scammer ask me not to tell my bank?
Isolation makes unusual withdrawals less likely to be questioned. A bank’s fraud team may interrupt the payment before the money leaves.
Can I recover money sent through a crypto kiosk?
Recovery is difficult and not guaranteed. Report the transaction immediately to the operator, your financial institution, local police, and IC3.
Does a uniformed video call prove the person is an officer?
No. Uniforms, backgrounds, and even faces can be staged or manipulated. Independently verify the agency and the claimed case.
The Bottom Line
A fake law enforcement warrant scam turns a frightening accusation into pressure for secrecy, data, or payment. The displayed number and badge-like imagery are not verification.
End the contact and call the real agency through its own published channel. A genuine legal matter can be checked without handing money to a stranger.








