

Fun Coffee was presented as more than a cup of coffee. Promoters described a modern business, an investment app, and a community where ordinary people could earn unusually large returns while helping the network grow.
Then withdrawals stopped. The polished story gave way to police warnings, an arrest, and a second wave of people offering to recover the missing money for yet another fee.
Overview
Fun Coffee mixed a consumer brand with an investment pitch
The scheme wrapped its financial offer in the familiar language of coffee, technology, agriculture, and international expansion. That combination made it sound like investors were backing a real operating business rather than sending cryptocurrency into an opaque system.
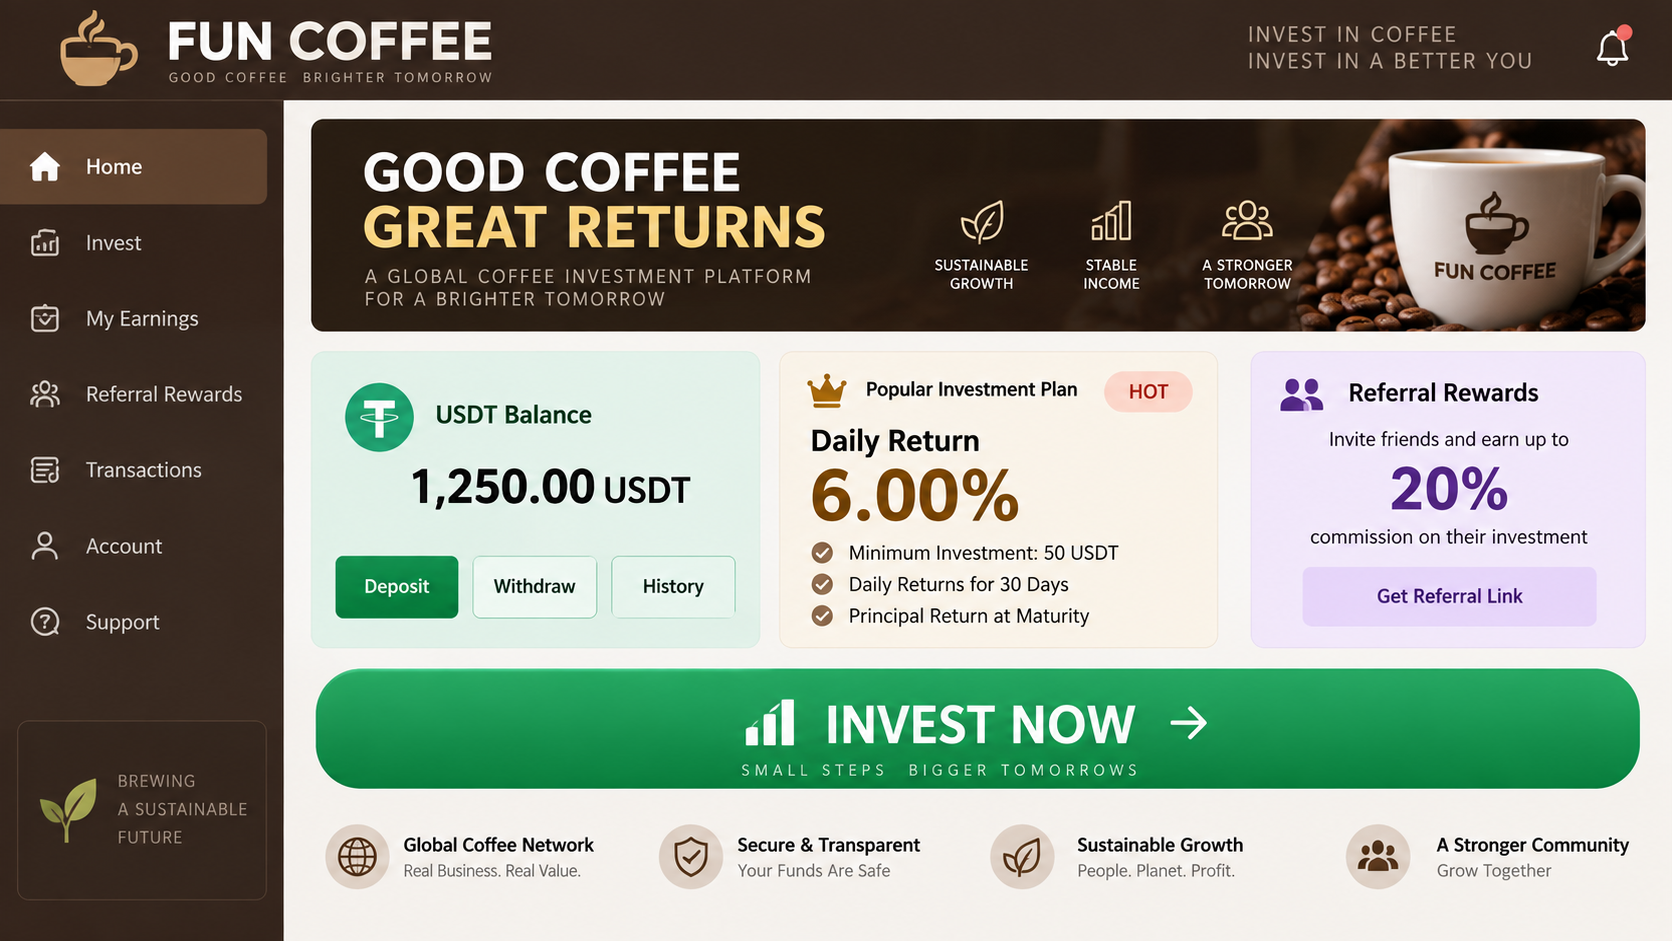
Promotional materials referenced projects, equipment, and a growing community. Yet the part that mattered most to participants was the app: deposit USDT, select a plan, watch the displayed balance rise, and receive more commissions by recruiting other people.
The official warnings are clear
Singapore Police said users were required to install the Fun Coffee application and transfer Tether, commonly called USDT, to wallet addresses provided through the app. The plans promised unrealistically high returns and offered extra commissions for recruitment.
Police also said participants in Singapore later became unable to withdraw their funds. Hong Kong’s Securities and Futures Commission separately listed Fun Coffee GCM Projects as a suspicious investment product, while Hong Kong’s Anti-Deception Coordination Centre included Fun Coffee among fraudulent investment apps.
The danger continues after the platform fails
When an investment platform stops paying, victims understandably search for a way to recover their savings. Criminals know this and may pose as recovery agents, lawyers, investigators, or Fun Coffee representatives.
Singapore Police issued a separate warning about people demanding deposits, tax payments, or service fees to recover Fun Coffee losses. Paying those charges does not restore the original investment. It creates a second loss.
- The opportunity was promoted through an app and a coffee-business story.
- Participants transferred USDT to wallet addresses supplied by the platform.
- Investment plans displayed unusually high promised returns.
- Recruiting more participants could generate additional commissions.
- Some users later reported that they could not withdraw their funds.
- Recovery scammers now target people who already lost money.
Why the Fun Coffee Pitch Looked Convincing
A sophisticated investment scam rarely begins with a crude demand for money. It starts by giving the target a story that feels complete. Fun Coffee used a recognizable product, a technology narrative, branded events, and a dedicated application to create that sense of completeness.
Coffee is easy to understand. Most people can imagine shops, packaged products, equipment, and international sales. A promoter can point to those visible ideas while avoiding harder questions about audited revenue, ownership of assets, and how investor returns are actually produced.
The app added another layer of credibility. A screen showing a balance, daily earnings, and successful transactions feels precise, but those numbers can be generated by the platform itself. A dashboard is not proof that assets exist outside the dashboard.
Early withdrawals can also make a scheme look legitimate. If new deposits are used to pay earlier participants, the first group may receive real money and enthusiastically recommend the opportunity to relatives and friends.
That social proof is powerful because the recommendation comes from someone the next investor trusts. The friend may be sincere and may have withdrawn funds, but neither fact proves that the underlying business can support the promised returns.
Cryptocurrency makes the structure harder to examine. USDT transfers can move quickly across borders, wallet addresses do not carry familiar consumer protections, and a completed blockchain transaction usually cannot be reversed by a bank.
Recruitment rewards create pressure to stop asking uncomfortable questions. Once a participant earns commissions for bringing in others, admitting doubts can threaten both income and reputation.
The result is a self-reinforcing network. App balances appear to grow, promoters repeat the same success stories, and each new member is encouraged to interpret visible activity as proof of a profitable enterprise.
How the Fun Coffee Investment Scam Works
Step 1: Promoters introduce a polished business opportunity
The target hears about Fun Coffee through a friend, social media post, seminar, private chat, or community event. The opening conversation focuses on innovation, coffee, wellness, technology, or expansion rather than risk.
Promoters may show branded presentations, storefront photos, equipment, or testimonials. These details can demonstrate that marketing exists, but they do not establish that investment returns come from genuine business profits.
Step 2: The victim installs the platform’s application
The participant is directed to download an app and create an account. A professional interface displays plans, balances, tasks, referral statistics, and projected earnings.
An app obtained outside a major official store deserves particular caution. Even an app found in an official store is not automatically a licensed investment product, because store review is not financial regulation.
Step 3: USDT is transferred to a supplied wallet
The victim buys USDT through an exchange and sends it to the address shown by the promoter or application. The payment may be described as a subscription, equipment purchase, project contribution, or investment plan.
Once sent, the cryptocurrency is controlled by whoever holds the receiving wallet keys. The app can credit an internal balance without proving that the same funds remain available for withdrawal.
Step 4: Artificial returns and small withdrawals build trust
The dashboard begins showing earnings. Some participants may be allowed to withdraw a limited amount, which makes the platform feel safer and provides a persuasive story to share with other people.
The displayed rate may be far beyond what a coffee business could reliably produce. Instead of explaining audited cash flow, promoters emphasize compounding, limited slots, or the cost of waiting.
Step 5: Recruitment becomes part of the return
Participants are offered bonuses, ranks, or commissions for adding new members. A team structure may reward deposits made further down the network.
This is a critical warning sign. When benefits depend heavily on continual recruitment rather than verifiable sales to independent customers, the system becomes vulnerable as soon as new deposits slow.
Step 6: Withdrawals fail and new fees appear
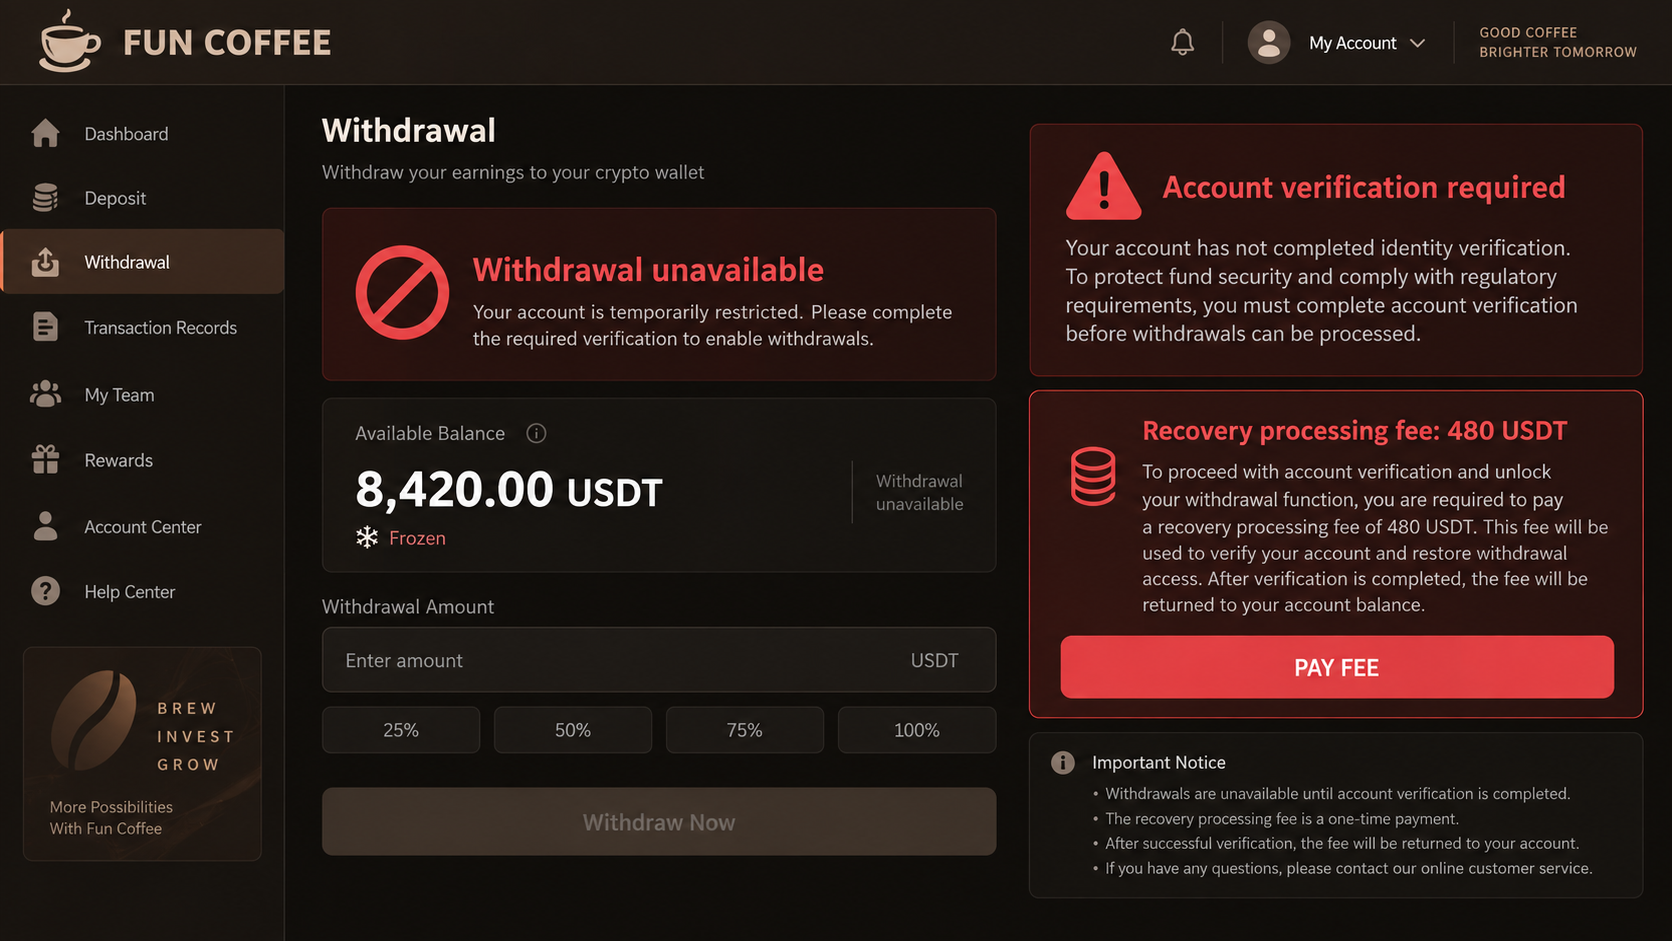
The application delays withdrawals, changes rules, goes offline, or says an account requires tax, verification, liquidity, or activation payments. Sending more money rarely solves the problem.
After public complaints begin, supposed recovery specialists contact victims. They claim to have inside access, legal authority, or tracing technology, then demand a deposit or tax before returning funds that never arrive.
The Red Flags Investors Should Not Ignore
Unrealistically high returns are the most visible warning. Every investment carries risk, and a business cannot honestly guarantee extraordinary profits without explaining the economic activity that produces them.
A referral program is not automatically fraudulent, but it becomes dangerous when recruiting deposits appears more important than selling a real product to customers who are not participating in the investment.
Cryptocurrency-only funding reduces accountability. A legitimate investment operator should be able to explain its legal entity, licensing status, custody arrangements, audited accounts, and investor protections before taking money.
A branded cafe or real product does not validate the investment. A physical location can exist while the financial offer remains unauthorized, unsustainable, or separate from the retail activity shown to potential investors.
Pressure to act quickly is another sign. Limited-time tiers, expiring bonuses, and warnings that a team position will be lost are designed to prevent independent research.
Vague language about artificial intelligence, robotics, agriculture, or global ecosystems should lead to concrete questions. What company owns the assets? Where are audited statements? Which regulator authorized the offer? How does product revenue cover the promised payout?
A balance that can only be viewed inside one app has no independent confirmation. Until funds reach a wallet or bank account you control, the number may be nothing more than an entry in the operator’s database.
Secrecy is also a warning. Promoters may tell members that critics do not understand the opportunity or that negative reports are attacks by competitors. Genuine investments should withstand scrutiny.
How to Check an Investment App Before Sending Crypto
Start with the regulator, not the promoter. Search official warning lists and financial institution registers in every country where the operator claims to conduct business.
Look up the precise legal entity. A brand name is not enough. You need the registered company name, registration number, directors, physical office, and the license covering the exact investment activity.
Ask for audited financial statements and read them independently. A marketing deck, app screenshot, bank-transfer image, or certificate created by the promoter is not an audit.
Trace the economic claim. If returns supposedly come from coffee sales or technology projects, the operator should be able to show ordinary customer revenue, costs, contracts, and a plausible margin.
Test whether recruitment is optional in practice. If the attractive return depends on building a team or if leaders earn mainly from member deposits, treat the structure as extremely high risk.
Check how deposits are held. A wallet address supplied in a chat does not reveal whether funds are segregated, insured, or controlled by a regulated custodian.
Read withdrawal rules before depositing. A platform that can change limits, add fees, or freeze accounts at its sole discretion gives users very little protection.
Search for independent reporting, but distinguish verified facts from promotional articles. Official police, court, and regulator records carry more weight than testimonials or paid reviews.
Never rely on a successful small withdrawal as the final test. Fraudulent systems often pay early users specifically because that proof encourages larger deposits and referrals.
If the offer still seems attractive, speak with a licensed financial professional who has no connection to the promoter. An independent person has no commission riding on your decision.
Company, Address, and Fulfillment Checks
Confirm the exact company and investment license
Company registration only shows that an entity was formed. It does not authorize the company to collect investments, promise returns, operate a cryptocurrency platform, or sell securities.
Search regulator databases for the legal name and representatives. The Hong Kong SFC’s warning and the Singapore Police investigation are more meaningful than a certificate shown by a recruiter.
Verify the people promoting the plans
Ask for the promoter’s licensed status and confirm it through the regulator’s own directory. A rank inside an app is not a professional investment credential.
Be wary when the person answering questions receives referral commissions. Their financial incentive may depend on your deposit, even if they believe the opportunity is genuine.
Inspect addresses, websites, and app distribution
Confirm offices through independent records and contact building management when necessary. Photographs, virtual offices, and temporary venues do not prove where investor funds are managed.
Check domain history, official app-store listings, developer identity, privacy terms, and permissions. Do not install an APK or configuration profile sent through a private message.
Demand a verifiable withdrawal and custody process
Find out who controls deposited crypto, how withdrawals are approved, and what independent protections apply if the platform fails. Vague answers mean you cannot measure the real risk.
No legitimate recovery process should require a surprise crypto payment to release frozen funds. Verify every recovery claim with police or the relevant regulator before responding.
What to Do if You Have Fallen Victim to This Scam
- Stop every new payment. Do not send tax, verification, unlock, liquidity, or recovery fees. A demand for one final transfer is usually an attempt to increase the loss.
- Contact your exchange immediately. Provide transaction IDs and receiving wallet addresses. Ask the exchange to flag the transfer and preserve records, although completed crypto transfers may not be reversible.
- Secure financial and crypto accounts. Change reused passwords, enable strong two-factor authentication, revoke unknown sessions, and move remaining assets if a seed phrase or private key was exposed.
- Remove untrusted software. Uninstall unofficial applications and profiles. Run a reputable scan such as Malwarebytes if you installed an APK, opened a suspicious attachment, or granted remote access.
- Block malicious follow-up pages. AdGuard can reduce exposure to known phishing and scam domains, but it cannot reverse a transfer or make an unlicensed investment safe.
- Preserve the complete evidence. Save chats, usernames, phone numbers, referral trees, plan descriptions, app screens, wallet addresses, transaction hashes, receipts, and failed-withdrawal messages.
- Report to authorities. Contact local police and the relevant financial regulator. Singapore residents can report to Singapore Police and use ScamShield guidance; Hong Kong residents can contact Police and the SFC.
- Warn people you recruited. Share verified information without promising recovery. They need time to secure accounts, save evidence, and avoid sending additional funds.
- Reject recovery agents who contact you first. Police have specifically warned about recovery-fee scams tied to Fun Coffee. Do not pay a deposit, tax, or service charge to an unsolicited helper.
If identity documents were supplied, monitor financial accounts and consider the identity-theft protections available in your country. The data may be used long after the investment platform disappears.
Frequently Asked Questions
Is Fun Coffee a legitimate investment?
Official warnings make the offer unsafe to treat as a normal investment. Singapore Police described an investigation, an arrest connected to promotion and recruitment, failed withdrawals, and unrealistically high promised returns. Hong Kong authorities also flagged the platform.
Why did some people receive withdrawals?
Early payments do not prove sustainable profit. A recruitment-driven scheme can use newer deposits to fund selected withdrawals, creating testimonials that attract larger sums.
Can a real coffee business still be linked to a bad investment?
Yes. A product, cafe, event, or registered company does not automatically validate a separate financial offer. The investment must be assessed through licensing, audited finances, custody, and realistic returns.
Can USDT sent to Fun Coffee be reversed?
Blockchain transfers are generally difficult to reverse. Contact the sending exchange immediately, provide the transaction hash, and file a police report so services can preserve or flag related records.
Should I pay a fee to recover my Fun Coffee funds?
No unsolicited recovery service should be trusted. Singapore Police warned that scammers are demanding deposits, taxes, and service fees from victims while failing to recover their money.
What evidence should I save?
Keep the application package or download link, account details, plan terms, referral messages, wallet addresses, transaction hashes, withdrawal attempts, support chats, and every recovery solicitation.
The Bottom Line
The Fun Coffee investment pitch used a familiar brand story, a polished app, USDT deposits, displayed returns, and recruitment rewards to create confidence. Official records now point to failed withdrawals, an investigation, and serious warnings from authorities.
Do not send more money and do not pay anyone who promises guaranteed recovery. Preserve the evidence, secure your accounts, report the loss, and rely on verified police and regulator channels rather than the people who promoted the platform.








