


A regulator’s name can make a difficult gold-contract decision sound settled. An explanation arrives, refers to the authorities, and presents the next step as unavoidable.
TGI AG’s dispute with Liechtenstein’s FMA shows why the actual documents matter. Approval, cancellation, a partial appeal, and a proposed transfer answer different questions.
Overview
The FMA corrected specific claims about its own actions
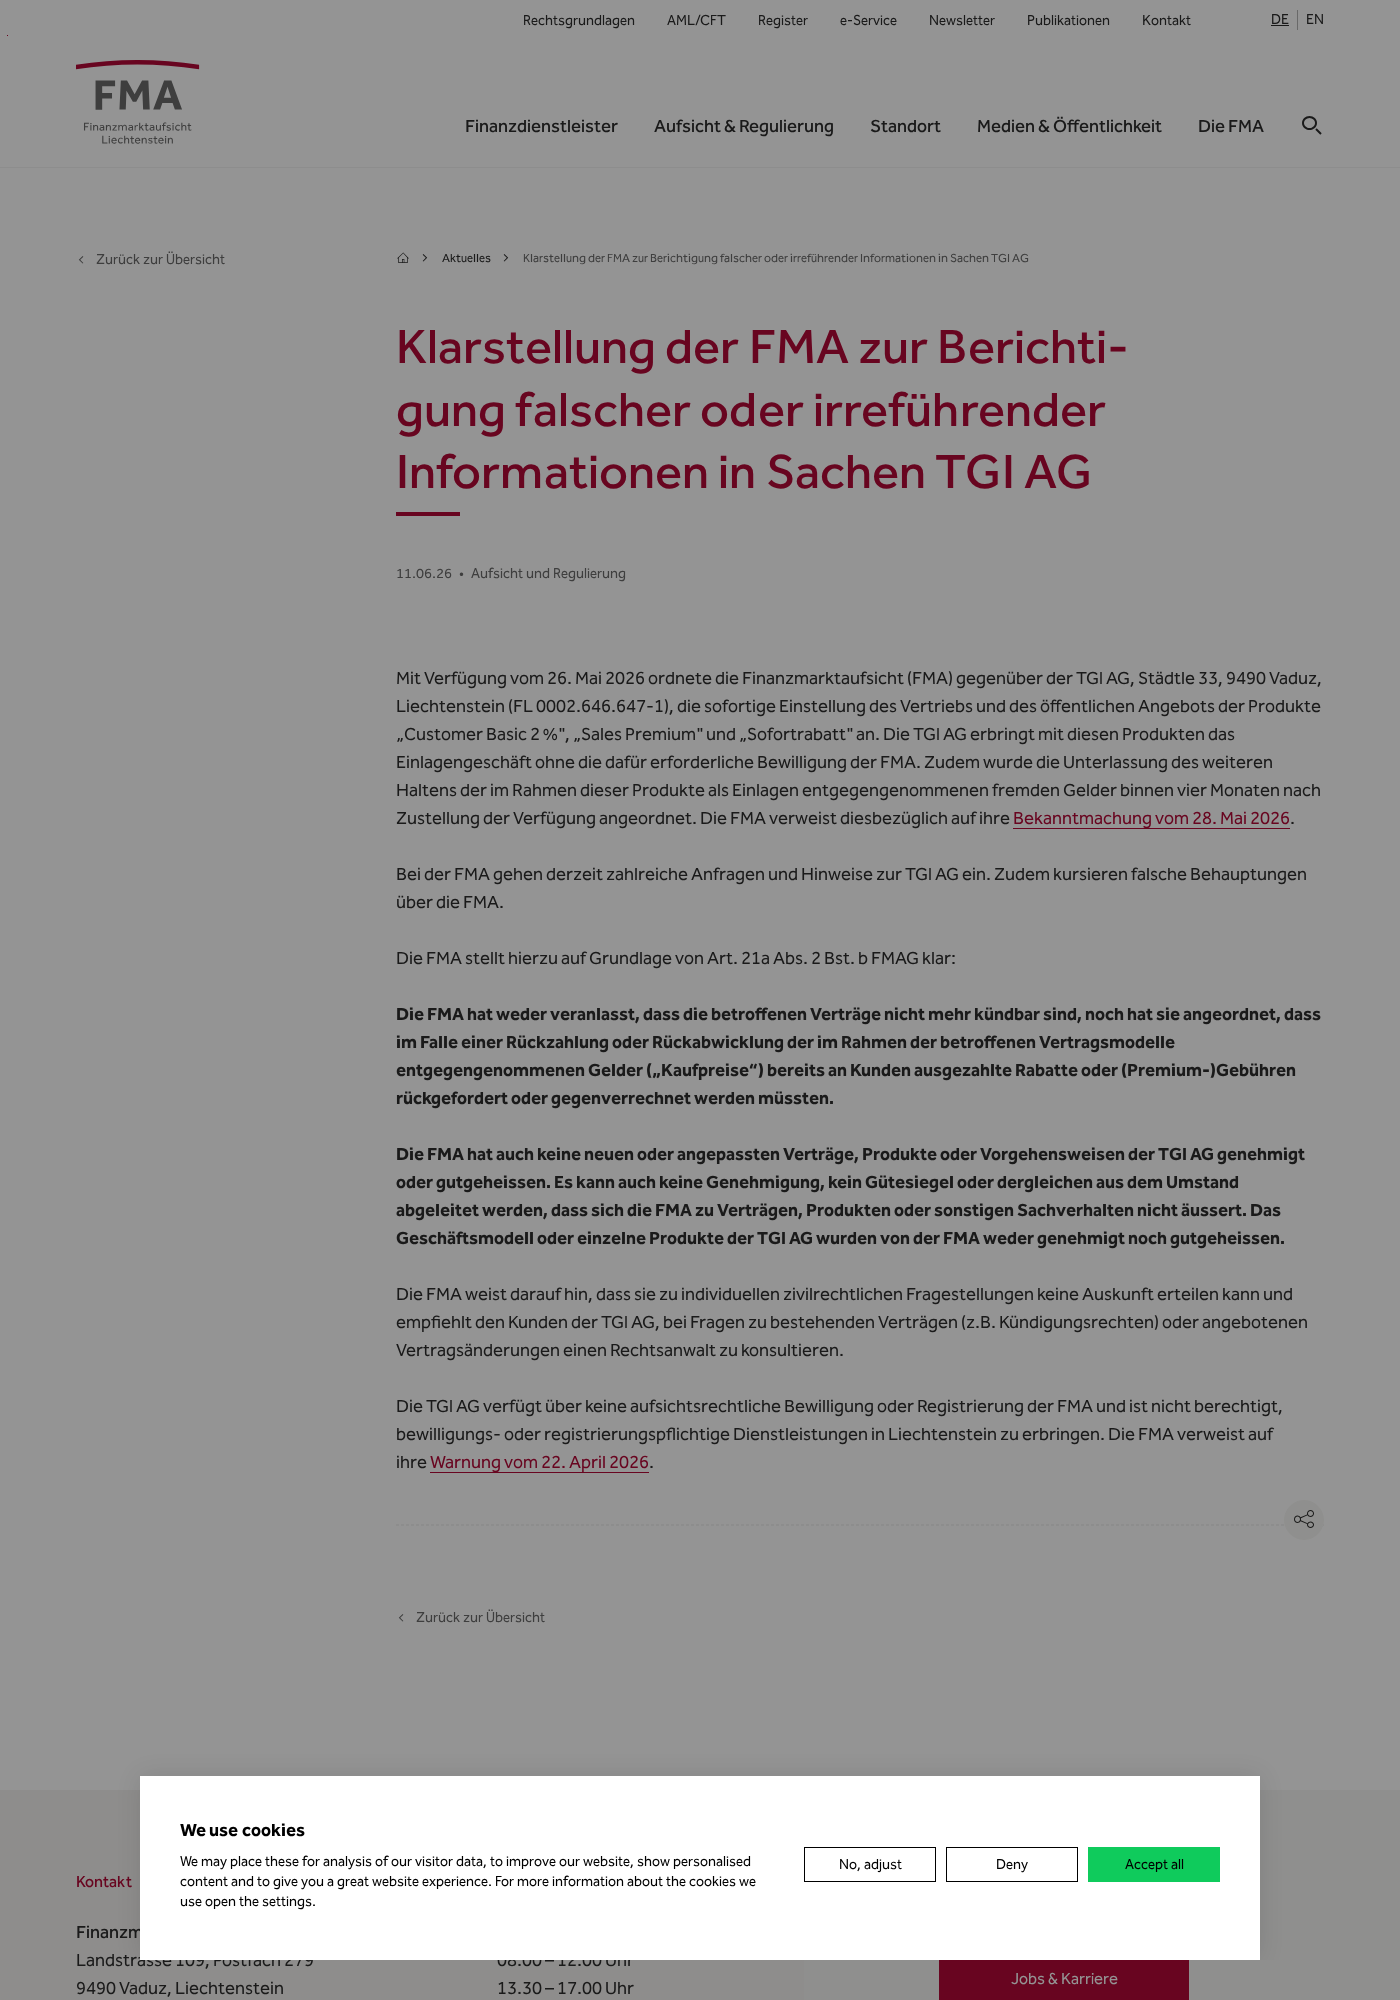
Liechtenstein’s Financial Market Authority published a TGI AG clarification on June 11, 2026. It addressed circulating claims about contract restrictions and regulatory approval.
If an explanation uses the regulator’s name, check it against that notice. A forwarded summary can leave out the qualification you need.
Keep a copy of the explanation you received. Mark the precise action it asks you to take, then gather the documents supporting it.
The appeal changed one measure, not the entire dispute
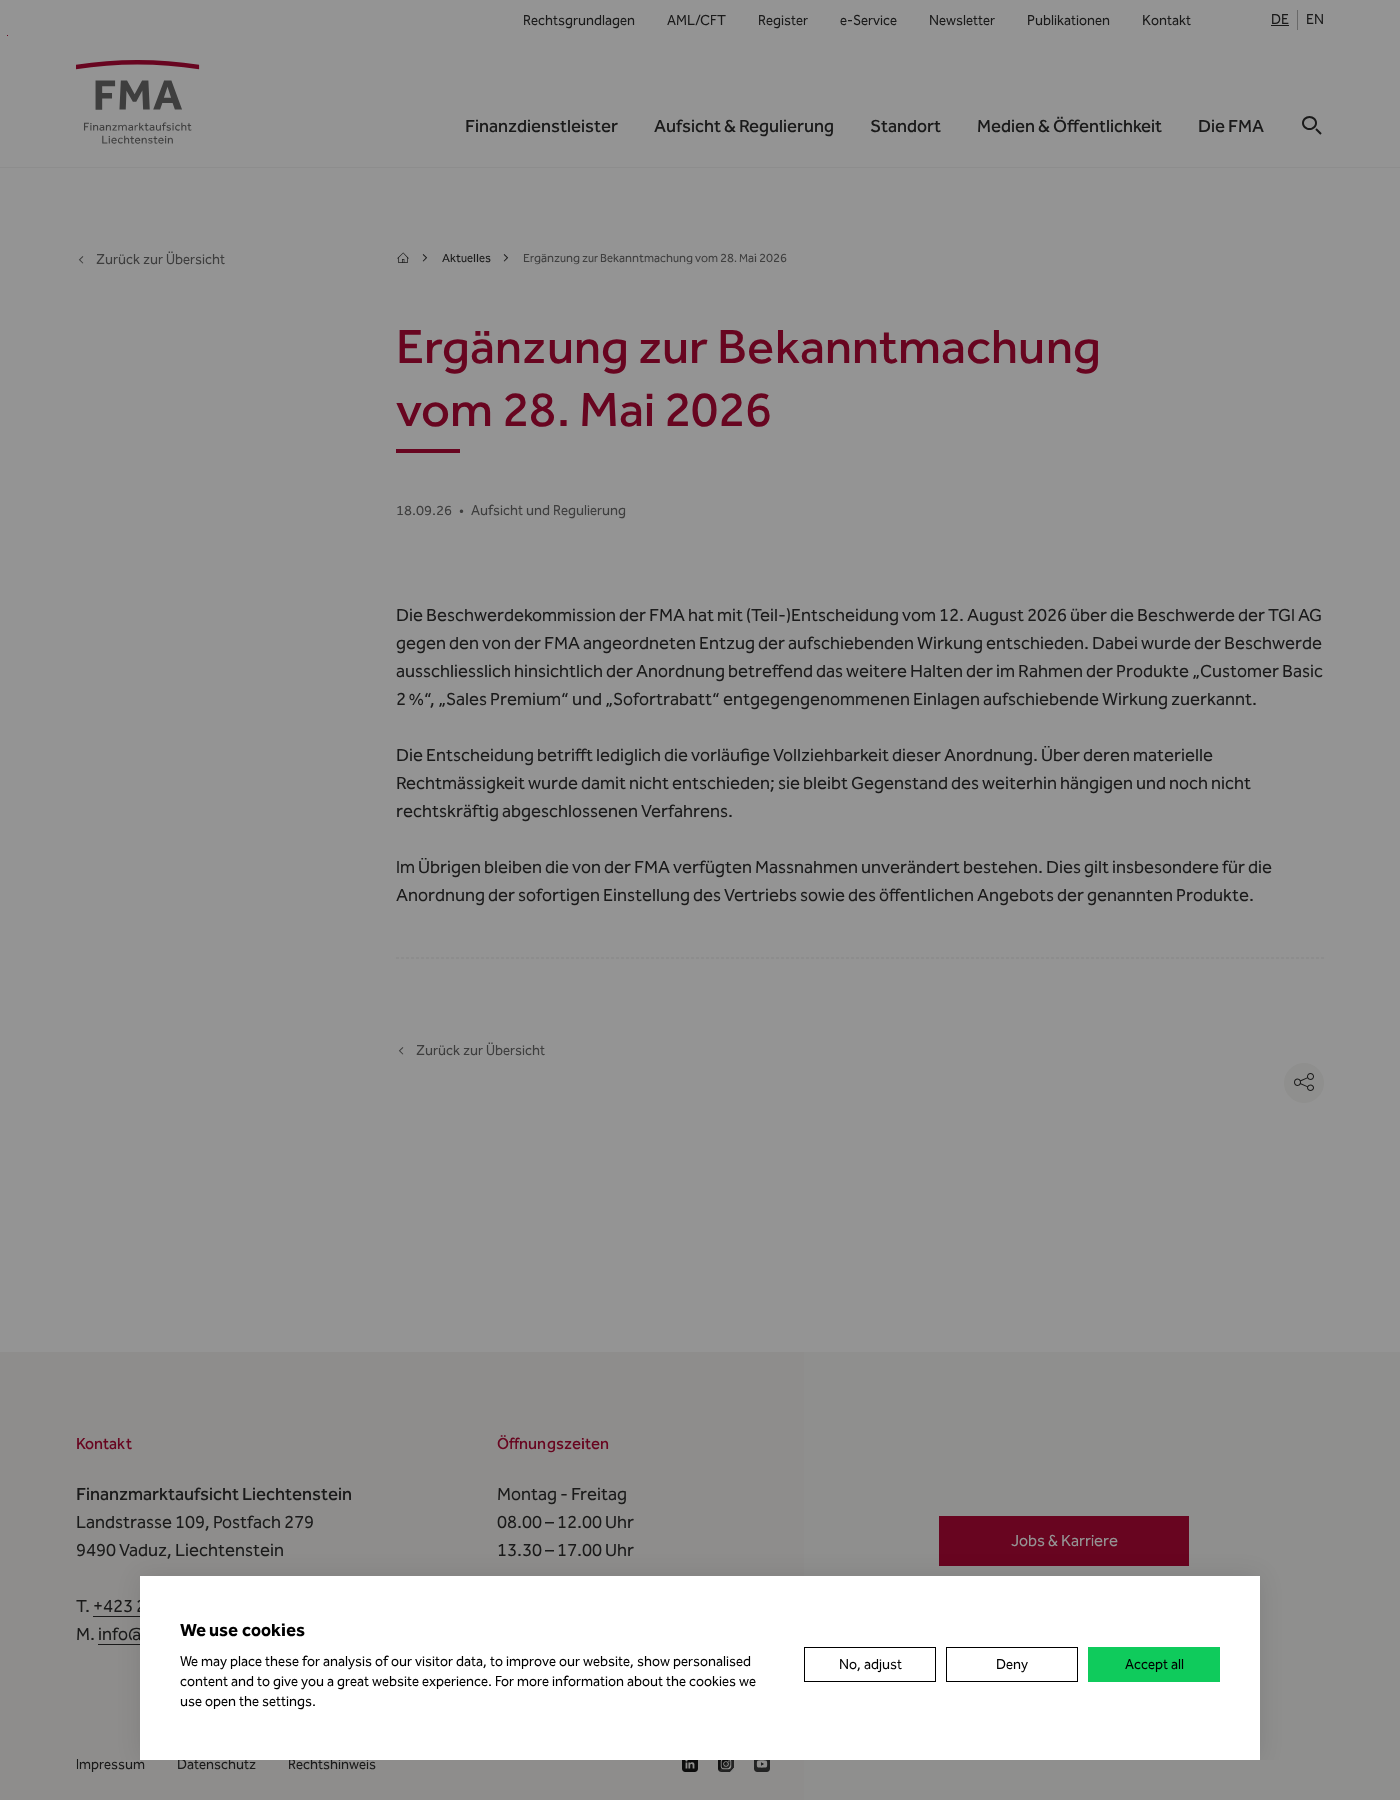
A September supplement explains that a partial appeal restored suspensive effect only for the order concerning continued holding of affected deposits. The sales stop remained.
A procedural pause is important, but its scope matters. It does not automatically authorize a replacement product or settle the merits of every disputed contract.
Keep the order, clarification, and appeal update together. Reading one paragraph without the later qualification can leave you with a materially different picture.
Existing customers need a decision tied to their own paperwork
TGI later announced that its Liechtenstein business would cease on July 31. Its notice presented settlement choices, including a possible transfer to another named company.
Do not commit more money or accept a replacement agreement simply because someone invokes FMA approval. Establish the proposal, contracting party, and effect on existing rights.
- Identify the product: Similar names can describe different arrangements.
- Identify the document: A company statement and an authority’s order serve different purposes.
- Identify the date: Later procedural changes can qualify an earlier enforcement announcement.
- Identify the decision: Keeping a claim, requesting payment, and authorizing a transfer are separate actions.
- Keep the evidence: Save the contract, amendments, payment records, gold-delivery documents, and actual communications.
What the FMA’s Clarification Does for a Customer
A claim about cancellation needs its real legal basis
The FMA says it did not cause the affected contracts to become non-terminable. Its name cannot substitute for the actual basis of a cancellation refusal.
If you receive that explanation, request the precise clause and document being relied on. Keep the complete reply rather than a shortened message passed between customers.
A contract may raise questions that an enforcement notice does not decide. Ask your adviser to distinguish the agreement’s terms from statements attributed to the regulator.
That distinction helps you describe the problem accurately. You are asking why a specific request was refused, not assuming that every contract can end immediately.
A discount adjustment needs more than an official-sounding explanation
The clarification also says the FMA did not order previously paid discounts or premium fees to be reclaimed or offset when affected arrangements are unwound.
If a settlement calculation deducts something, ask for an itemized explanation. Identify whether the deduction is described as contractual, agreed separately, or required by an authority.
Keep money paid in, money received, gold delivered, and proposed adjustments in separate columns. Combining them into one advertised balance can hide the issue you need assessed.
Do not assume the regulator’s denial determines every private calculation. It removes one asserted explanation; the remaining basis still needs to be shown and evaluated.
Silence is not an approval letter
The FMA explicitly rejects approval or endorsement inferred from its silence. It says it has not approved new or adapted TGI contracts, products, or practices.
A statement that documents were submitted does not show what an authority concluded. Neither does a conversation, a pending review, or a professional-looking presentation.
Ask for the actual decision being described, including its date and scope. Check whether it names the product and legal entity in your proposal.
A document can be genuine while the conclusion attached to it is too broad. Read what it permits or decides, rather than relying on the surrounding sales explanation.
Separate the May Order From the Later Appeal Update
The May 28 announcement describes an order dated May 26. It names Customer Basic 2%, Sales Premium, and Sofortrabatt.
The FMA required distribution and public offers of those products to stop immediately. It classified their operation as deposit business without its required authorization.
A separate measure concerned continued holding of the deposits, with a four-month period measured from service of the order. The announcement said the decision was not final.
The September 18 supplement reports an August 12 partial decision. Suspensive effect was granted exclusively for that continued-holding measure.
The supplement says this concerned provisional enforceability, with the substantive dispute unresolved. It expressly preserves the other measures, particularly the immediate sales and public-offer stop.
Do not turn the original four-month wording into your own guaranteed payment date. The service date, later procedural decision, and individual situation cannot be replaced by calendar arithmetic.
Likewise, a successful challenge to immediate enforcement is not automatically a successful challenge to every underlying finding. The exact part of the decision matters.
If you are shown a later order, retain the complete document. Have its operative wording checked against the earlier measures before treating a summary as decisive.
Read the Company’s Position Alongside the Official Record
On its May 28-dated response page, TGI rejects the deposit-business characterization. It presents the arrangements as purchases of physical gold with delivery obligations.
The company distinguishes a fourth product, Customer Basic 2% plus loyalty discount, from the three named in the Liechtenstein measure. It says its business was not entirely prohibited.
TGI’s response discusses potential financial disadvantages from unwinding contracts and says it would pursue legal remedies. Those are the company’s arguments, not findings adopted here.
Its August 15 statement describes the partial appeal result and also acknowledges that a final decision on the main appeal remained outstanding.
The June clarification does not identify who originated every circulating false claim. There is no basis here to assign all of them to a particular adviser or customer.
Preserve the precise message you received if someone attributes a restriction or approval to the FMA. Its wording is more useful than speculation about who started a rumor.
The July Announcement Makes the Contracting Party Especially Important
In its July 31 notice, TGI announced cessation of its Liechtenstein business. It offered bank payment or authorization of a transfer to TRUST GOLD International Ltd.
The announcement is evidence of what the company proposed. It does not independently confirm that a particular customer received payment or that a transfer was completed.
A promised settlement amount and a completed payment are different records. Save the proposal, your response, and any transaction confirmation as separate documents.
If another business is named, ask what you would be instructing TGI to do. Establish whether your money would be paid out or committed to a new purchase.
Do not assume a familiar presenter, back-office design, or similar trading name preserves the same contracting party. The paperwork should identify who owes each obligation.
More recent Handelsblatt reporting on November 4 describes delayed settlements and company explanations involving blocked accounts. That reporting is not a final ruling on an individual claim.
For your own case, establish what actually happened after the announcement. A stated processing estimate cannot replace evidence of receipt or resolve an overdue payment.
Company, Product, and Responsibility Checks
Match the legal entity to your agreement
The FMA identifies TGI AG at Städtle 33, 9490 Vaduz, with identifier FL-0002.646.647-1. Compare that identity with your actual contract and payment instructions.
A company name in a news report does not establish the party on every related document. Check amendments, settlement letters, and any new purchase agreement individually.
Record who signed each document and in what capacity. Keep the original file and accompanying message so the date and sender remain available.
A new company name needs a separate responsibility check
A transfer proposal should state the recipient’s complete legal identity and the obligation it would accept. A brand label is not enough to explain the transaction.
Ask whether the proposal changes the person you can pursue, the delivery commitment, the repayment arrangement, or the law and forum named in the paperwork.
Have those questions answered before authorizing instructions. Do not infer continuity, licensing, or customer protection merely because the new name resembles the old one.
The exact product and jurisdiction matter
The three products named in the Liechtenstein order should not be silently replaced with a similarly titled fourth product. Small wording differences can identify a different arrangement.
Write down the complete product name, purchase date, delivery schedule, and contracting entity. These details let an adviser compare the right documents.
The FMA’s notices concern Liechtenstein supervisory measures. A customer’s residence and applicable contract rules can matter separately when assessing private rights and remedies.
If another country’s decision is relevant, obtain that original decision too. Do not merge different authorities, products, and dates into one universal conclusion.
Get the proposed change and its consequences in writing
Request a complete copy of the replacement document before responding. Keep the version first offered as well as any revision after you ask questions.
Ask which existing obligations would remain and which would change. Identify any release, waiver, new delivery period, or transfer instruction that requires your agreement.
A short deadline in a message should prompt careful advice, not an assumption that the authority imposed it. Ask who set the deadline and what document supports it.
Build a Record That Shows Your Actual Position
Start with the original agreement and any incorporated conditions. Include schedules, purchase confirmations, subsequent variations, and the communications explaining them.
Keep the original payment currency and amount. If gold was delivered, retain the delivery record and the description of the bars rather than treating everything as an unpaid balance.
Prepare a short dated timeline: payment, promised delivery, communications, settlement choice, and any payment received. Use records rather than recollection where possible.
Keep a separate note of what is disputed. A disagreement over a deduction needs different supporting material from an instruction that was never carried out.
Store originals privately. When asking a public group for help, remove account identifiers, signatures, addresses, and other customers’ information.
What to Do If the TGI AG Dispute Affects Your Contract
-
Pause decisions based on alleged FMA approval. Do not send additional funds or sign a replacement agreement merely because someone says the regulator has endorsed it.
Request the actual authority document and compare the named entity, product, and action. Save both the assertion and the document supplied.
-
Identify the decision being requested. Establish whether you are being asked to cancel, accept a calculation, authorize payment elsewhere, or enter a new purchase.
Ask for the consequences of refusing or accepting in writing. A general explanation of the dispute does not answer what your signature would do.
-
Assemble the contract and payment trail. Keep the records described above together, including any gold already received and any amount actually returned.
Give your adviser an accurate position rather than the largest number visible in a dashboard. Flag missing documents so they can be requested.
-
Seek advice about your specific agreement. The FMA itself recommends a lawyer for existing contracts, termination questions, and proposed amendments.
Ask about your product, governing terms, deadlines, and available routes. Do not assume that another customer’s answer or a social-media template applies unchanged.
-
Ask for a written explanation of an unpaid amount. Identify the request date, amount, currency, proposed payment route, and any reason given for delay.
Keep company explanations as attributed statements. Your bank statement or transaction record is the evidence of whether money actually reached you.
-
Contact the relevant payment institution about actual transfers. Explain what you paid, when, and to whom, with supporting records.
Ask what options and time limits apply to that payment. A regulator’s notice does not automatically reverse a transfer or guarantee reimbursement.
-
Check new representatives independently. Verify anyone offering legal help or paid recovery through the appropriate professional directory and an independently obtained contact route.
A person’s knowledge of TGI does not establish authority to act for you. Review the engagement, fees, and proposed work before supplying private records.
Frequently Asked Questions
Did the FMA approve TGI AG’s revised contracts?
The June clarification says it did not approve or endorse new or adapted arrangements. It also rejects treating the authority’s silence as approval.
Did the FMA make every TGI contract impossible to terminate?
No. The authority denies causing the affected contracts to become non-terminable. Your own termination rights still require assessment of the relevant agreement.
Did the partial appeal cancel the sales stop?
The September supplement preserves the sales and public-offer stop. It describes suspensive effect only for the continued-holding measure, with substantive proceedings unresolved.
Does the original four-month period guarantee my repayment date?
No. Do not calculate an individual repayment promise from that wording. Service, subsequent procedural developments, and your contractual situation require separate consideration.
Does the July notice prove my funds moved to TRUST GOLD International?
No. It describes a proposed choice and authorization route. Your instruction and actual transaction records are needed to establish what happened in your case.
What should I do before accepting a replacement agreement?
Obtain the complete document, identify the contracting party and changed obligations, and seek advice on your existing rights before agreeing or transferring further funds.
The Bottom Line
Do not treat the FMA’s name, its silence, or a partial appeal result as approval to commit more money. Match every claim to its actual document.
If TGI AG’s dispute affects your contract, preserve the agreement and payment trail, identify the proposed decision, and obtain individual advice before surrendering rights or authorizing another transfer.

Join the discussion
0 commentsShare your experience or ask a question about this article.
Discussion
Start the conversation
Have a question or something useful to share? Add the first comment.