

A buyer likes your gift card listing but wants to verify the balance first. The gift card PIN scam hides inside that reasonable-sounding request.
You still have the card. No sale is complete. So why should sending one clearer photo make any difference?
Overview
The seller, not the shopper, is the target
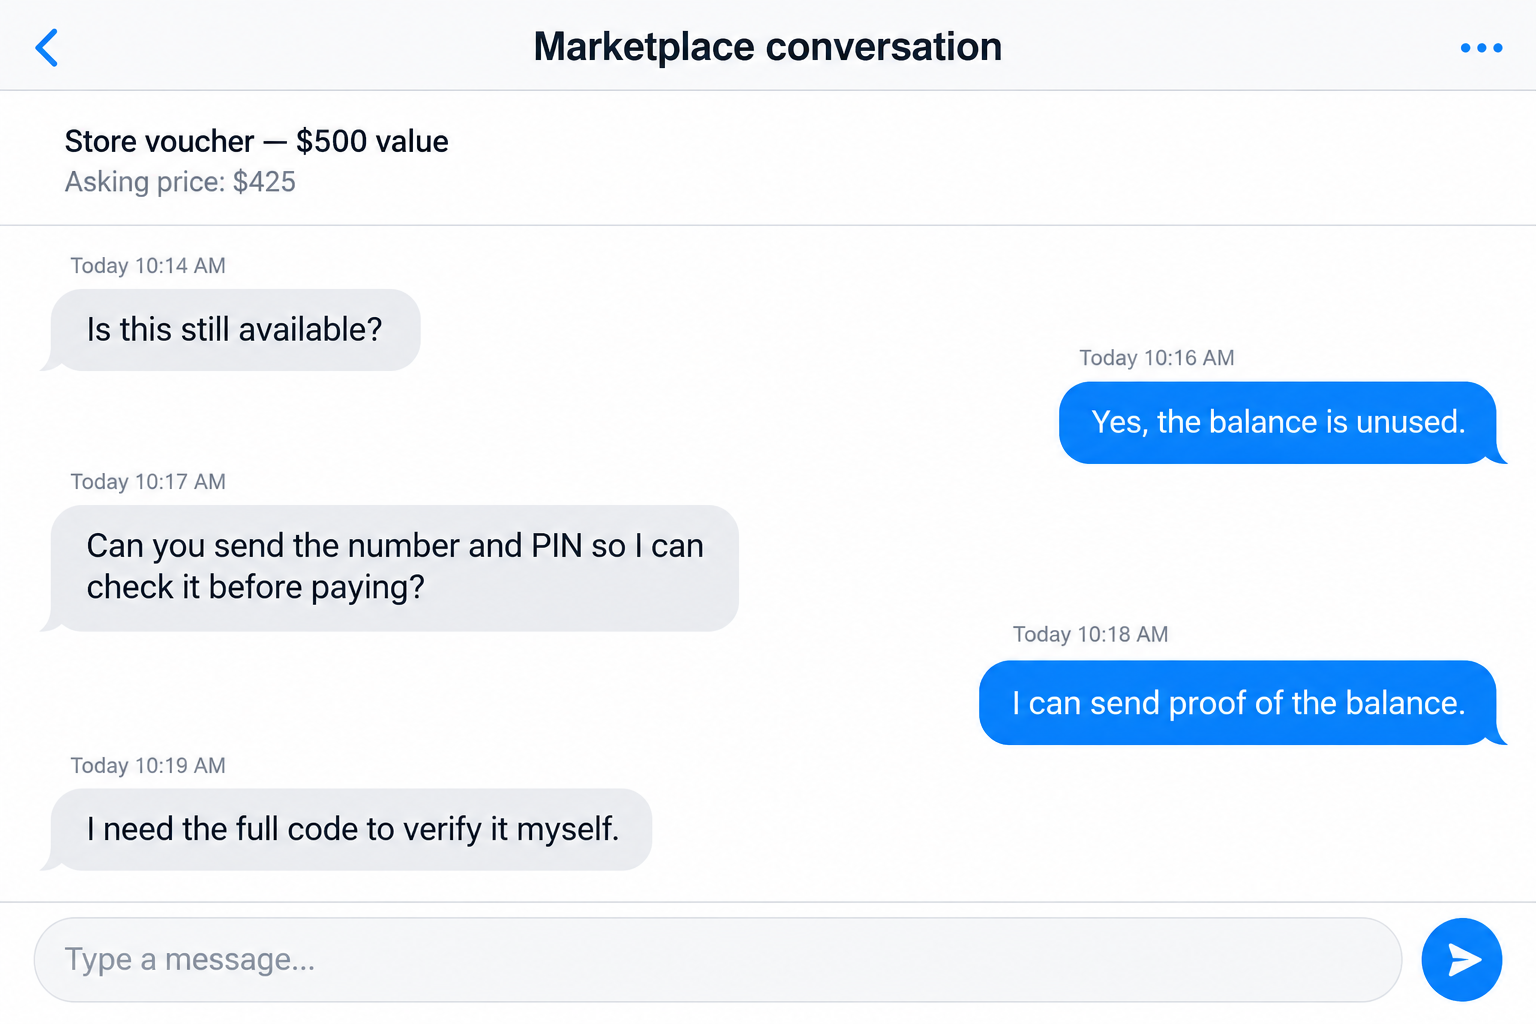
This scam targets people reselling their own gift cards or store vouchers. A supposed buyer asks for the information needed to spend the balance.
The request is framed as verification. The seller thinks they are proving the item exists, while the buyer may be obtaining usable value before paying.
A gift card number and PIN can matter more than possession of the plastic. Depending on the issuer, those details can enable remote redemption.
Federal warnings describe the resale-fraud mechanism
An FBI Internet Crime Complaint Center warning describes gift card resale fraud involving exposed PINs, redemption, and disputed payments.
The warning is older documentation of the mechanism, not a newly measured surge. Recent marketplace reports should not be used to invent victim totals.
The FTC explains why sharing gift card numbers and PINs is dangerous: someone can take the value without holding the physical card.
A balance check is not a reason to surrender spending details
- A stranger asks for the full card number, PIN, barcode, or redemption image.
- They describe the request as checking, reserving, authenticating, or preparing payment.
- They reject a redacted balance screenshot and insist on usable credentials.
- Payment has not arrived, or its protection and reversal rules remain unclear.
- The card balance becomes the seller’s risk while the buyer controls the next step.
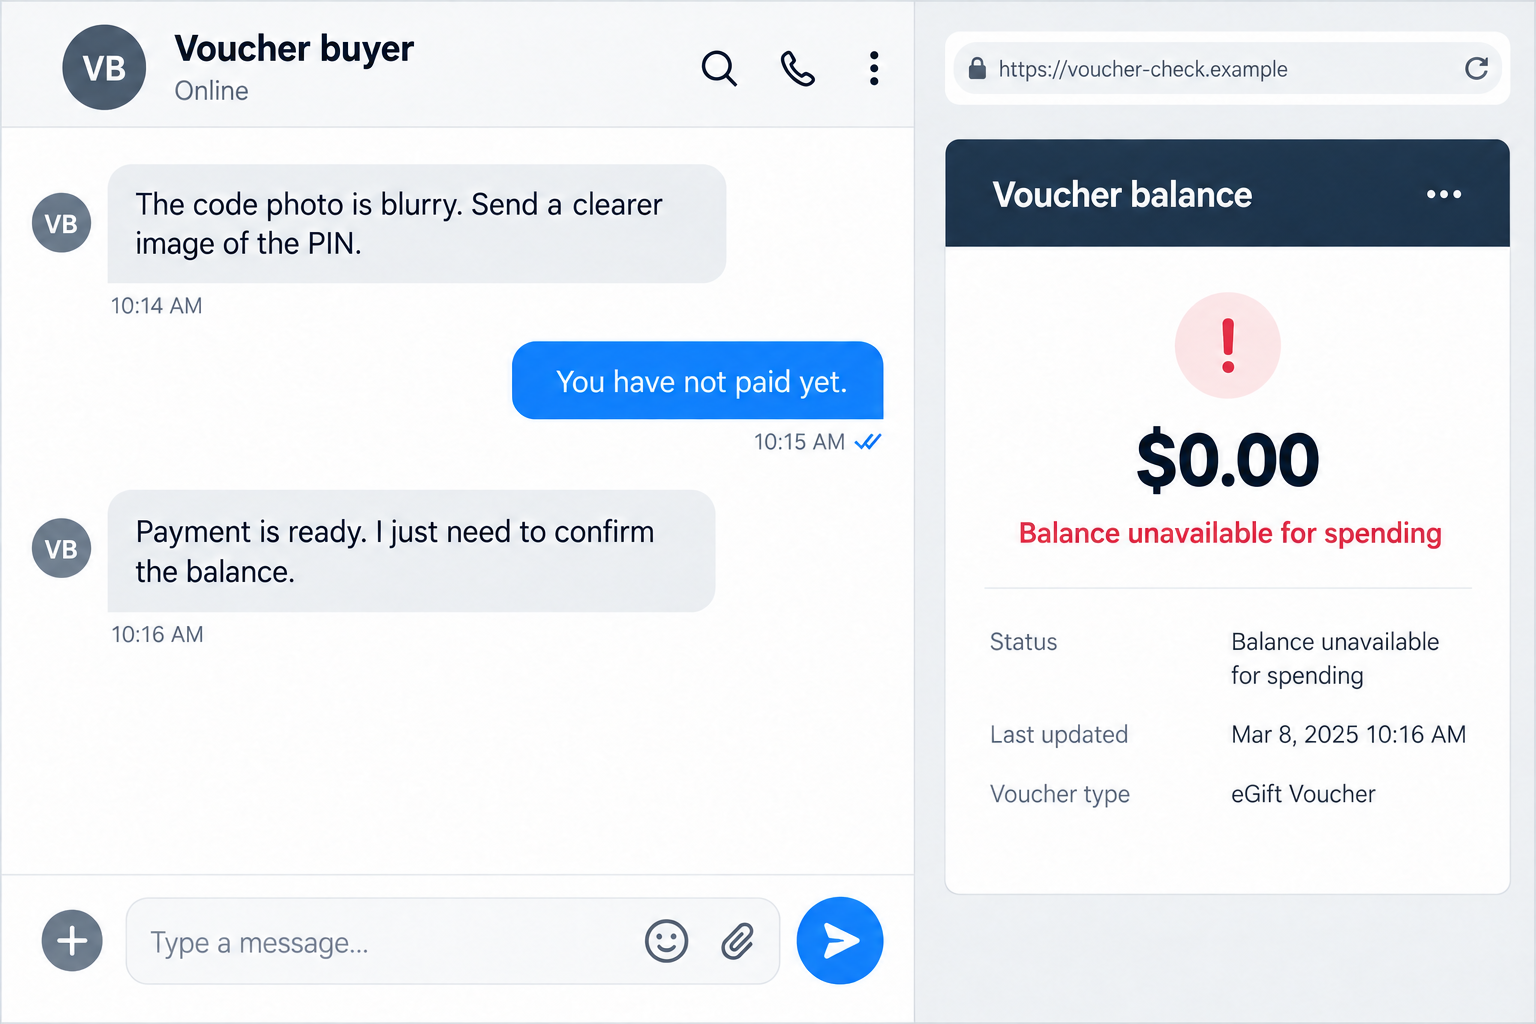
The example conversations are fictional reconstructions with invented amounts and addresses. They illustrate credential exposure, not a verified transaction involving a particular store or customer.
Why a Gift Card Photo Is Not Like a Photo of a Chair
When selling furniture, you can send detailed pictures without handing over the item. Gift cards are different because the information can be the item.
A photo may contain the exact details required to redeem a balance. Once those details leave your control, keeping the card does not necessarily preserve its value.
That is why a request for a sharper image deserves attention. The buyer may not need a better view of the product, only readable credentials.
A barcode or QR code can also carry useful redemption information. Do not assume that hiding printed digits makes the rest of the image harmless.
The precise redemption process varies by issuer. Check your card’s genuine terms rather than relying on the prospective buyer’s explanation of what can happen.
A legitimate buyer may reasonably want confidence that a voucher has value. That concern does not make every method of proving it safe for the seller.
When the only proposed verification requires giving a stranger spending access, the transaction structure is the problem. Politeness cannot fix that imbalance.
You can decline the sale without proving the other person’s intentions. Protecting an unused balance does not require a confession from the buyer.
How the Gift Card PIN Scam Works
Step 1: A buyer responds to an attractive resale listing
The seller may have an unwanted present, a return credit, or a voucher they cannot use. Offering it below face value attracts attention.
The opening conversation can be completely ordinary: availability, balance, asking price, and pickup or delivery. Nothing requires the first message to sound suspicious.
A profile with an apparent history does not guarantee the person currently using it is trustworthy. Judge the proposed exchange, not just the account’s appearance.
Keep the conversation in a channel where you can preserve the listing and messages. Moving elsewhere can make later reporting more cumbersome.
Step 2: Verification requires the secret part of the card
The buyer asks for the number and PIN to check the balance themselves. They may claim a screenshot is insufficient or that payment requires validation.
This is the pivotal request. The seller is being asked to disclose what may allow spending, before receiving a safely structured exchange.
A photo of the front may lead to a request for the back. A partially hidden code may lead to a request for an unobstructed version.
Do not keep negotiating which portion of the secret is safe to reveal. Consult the issuer’s rules and stop if the arrangement leaves you unprotected.
Step 3: A small objection becomes pressure to finish
The buyer may say the code is blurry, the balance page will not load, or payment is waiting for one last detail.
These claims shift attention toward completing a simple task. The larger question, why a stranger needs redemption access, gets pushed aside.
A seller may also feel uncomfortable appearing distrustful. That social pressure is not a good reason to reveal information that cannot be taken back.
If the buyer insists that everybody does this, that still does not establish protection. Ask what happens if the balance disappears before the sale is completed.
Step 4: The value can disappear without the card changing hands
Once usable details are exposed, the card may be redeemed remotely. The seller can discover the loss while still holding the original physical item.
How quickly this happens depends on the card and circumstances. Do not assume a delay means the disclosed credentials are safe.
Checking a positive balance after sharing the code is only a snapshot. It does not prevent someone from spending that balance later.
If you realize you disclosed redemption details, contact the issuer promptly. Ask whether the balance can be protected, frozen, or replaced under its procedures.
Step 5: A payment can create a second dispute
The IC3 warning also describes buyers redeeming cards and disputing payments. That means receiving a payment notification does not settle every resale risk.
Do not rely on a screenshot the buyer sends. Open your payment provider independently and review the actual transaction and applicable seller-protection terms.
Digital goods and stored-value products may have special restrictions. You need the provider’s rules for this transaction, not a general promise from the buyer.
If a payment is later challenged, preserve the full exchange. Never send a separate refund outside the provider’s process merely because the buyer demands it.
Proving the Balance Without Publishing the Keys
Use the real issuer’s balance-checking channel
Find the issuer through the card’s genuine materials or a website you independently trust. A link supplied by a buyer can introduce an additional phishing risk.
A balance-checking page can legitimately ask for card details. The important questions are who operates it and whether you reached it independently.
Never assume a familiar logo makes a buyer-supplied checker safe. You may be entering the same secrets into a page controlled by someone else.
Review every part of an image before sending it
Redact complete numbers, PINs, barcodes, QR codes, account details, and anything else that can authorize redemption. Check that edits are permanent in the exported image.
Do not merely place a movable shape over sensitive data in an editable file. Share only the flattened result if you decide a screenshot is appropriate.
Even a redacted screenshot proves only a momentary balance. It does not create a protected transaction or guarantee that a buyer will pay.
Check whether resale is permitted and protected
Some vouchers have transfer restrictions or conditions. Read the issuer’s terms before listing rather than discovering a limitation after exchanging money.
If using a resale service, review its current fees, verification process, seller protection, and dispute rules. Do not treat an unfamiliar intermediary as automatically safer.
For a private exchange, consider whether the remaining uncertainty is acceptable at all. Keeping or using the voucher may be preferable to exposing its full value.
The Difference Between a Cautious Buyer and a Dangerous Request
A genuine buyer can worry about receiving an empty card. A genuine seller can worry about giving away a working code. Both concerns are understandable.
The scam exploits that tension by presenting unrestricted code disclosure as the only reasonable solution. It is not.
You do not need to label every person asking questions a criminal. Focus on whether the proposed process gives away value before its safeguards are established.
A stranger requesting a secret does not become trustworthy because they accuse you of being difficult. Refusing an unsafe exchange is not misconduct.
Similarly, a real store’s gift card being used in fraud does not mean the store organized it. Keep reports directed at the buyer and exposed transaction.
Do not publish an unverified person’s name, phone number, or profile photograph as proof of identity. Accounts and images can be copied or compromised.
A useful public warning describes the request and hides redeemable information. Posting the unredacted card while asking for advice can spread the exposure further.
If several people offer to test the card for you, decline. You need the issuer’s support, not additional strangers with the same credentials.
What to Do if You Have Fallen Victim to This Scam
- Contact the gift card issuer before negotiating with the buyer.
Explain that redemption details were disclosed during a suspected resale scam. Ask whether any remaining balance can be blocked or transferred.
Use an independently verified support channel. Keep the card and original purchase receipt if you have them, since the issuer may request proof of ownership.
Do not assume replacement is available. The issuer’s rules and the timing of redemption affect what assistance it can provide.
- Document the balance and redemption issue.
Save the listing, messages, time of disclosure, and any balance result you obtained from the real issuer. Note what information was visible in each image.
Ask support what transaction information it can provide. Do not invent the buyer’s location or spending history from a zero balance alone.
- Handle payment disputes through the actual provider.
Open your account directly and check whether a payment exists. A buyer’s receipt image or email is not enough.
If a dispute has started, respond through the provider’s case process with the complete evidence. Describe the card as a gift card, not another product category.
Do not make a separate repayment because the buyer claims the original payment is stuck. Verify the provider’s instructions first.
- Report the account and listing conversation.
Use the marketplace’s reporting tools and preserve the report reference. Explain that the supposed buyer sought redemption credentials under a verification pretext.
In the United States, you can also report gift card fraud through the FTC guidance linked above and relevant law-enforcement channels.
- Address extra exposure if a verification site was involved.
If you entered account passwords into a buyer-supplied page, change them on the real service. Review sessions and enable available account protections.
If you downloaded a supposed checking tool, a Malwarebytes scan can help assess software exposure. Seek further assistance if the device behaves unexpectedly.
AdGuard may help reduce encounters with deceptive ads or pages. It cannot restore a redeemed voucher or make sharing its PIN safe.
- Do not pay a recovery fee.
A stranger claiming they can reverse redemption may ask for another card, a deposit, or account access. Stop rather than layering another loss onto the first.
Keep working with the issuer and payment provider. Be skeptical of unsolicited helpers who arrive after you post about the incident.
If the Buyer Has Not Redeemed It Yet
A remaining balance is a chance to contact the issuer, not a reason to continue the sale. Explain that someone else now has the redemption information.
Do not test whether the buyer is honest by waiting. You cannot control what they do with a code once it has been copied.
If the issuer offers a replacement or another protective option, follow its instructions through the official channel and keep the resulting case details.
Remove exposed images from your listing or public post, but remember that removal cannot erase copies already saved by other people.
Tell anyone helping you not to forward the unredacted material. Evidence can be preserved privately without giving more people access to the balance.
Most importantly, do not feel obligated to finish the exchange because the buyer has invested time in it. Your remaining funds take priority.
Frequently Asked Questions
Can someone spend a gift card without the physical card?
Depending on the issuer, the number and PIN can enable online redemption. Physical possession alone is therefore not a reliable safeguard after those details are shared.
Is a balance screenshot safe to send?
Only consider it after removing every redeemable code and personal detail. Even a carefully redacted screenshot does not create payment protection or establish the buyer’s trustworthiness.
What if the buyer sends proof that payment is pending?
Check your payment account independently. Their screenshot cannot establish settlement, seller protection, or whether a later dispute could reverse the transaction.
Does a positive balance mean the code was not stolen?
No. It shows the balance at that moment. Someone holding valid credentials may attempt redemption later, so contact the issuer about the exposure.
Should I reveal only the barcode instead of the PIN?
Do not assume that is safer. Machine-readable codes may contain redemption information. Verify the issuer’s process before sharing any portion of a usable voucher.
Will the store refund a card drained by a fake buyer?
Recovery is not guaranteed. Contact the issuer quickly, preserve the purchase receipt, and ask what protection or investigation is available for the specific card.
The Bottom Line
The gift card PIN scam works because verification sounds harmless. But a request for usable redemption details can be a request for the money itself.
Keep those details private until you understand the exchange and its protections. A buyer’s impatience is not worth sacrificing the balance you are trying to sell.

Join the discussion
0 commentsShare your experience or ask a question about this article.
Discussion
Start the conversation
Have a question or something useful to share? Add the first comment.